Tech's Valuation Premium Has Gone, but the Discount Is an Analyst Estimate
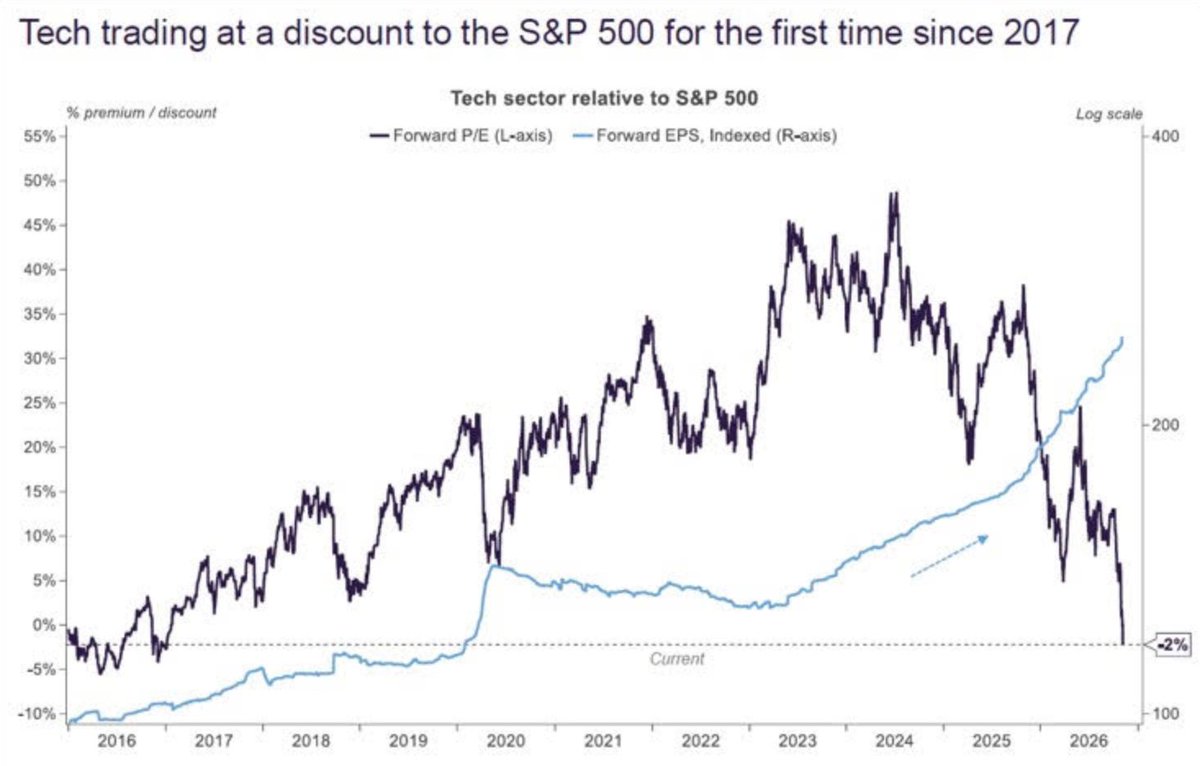
Two years ago the US technology sector traded at a forward price-to-earnings ratio almost 50% above the broad market. This week some measures put it slightly below the market, the first time since 2017.
That discount is the result of two things happening at once, and only one of them is the share price.
In the numerator, tech shares have been sold down hard from their highs. In the denominator, analysts are still raising their profit forecasts for these companies. The pale line on the chart has kept making new highs through the selloff. Falling prices and rising estimates push the ratio down quickly.
The denominator is the weak point. Forward earnings are a guess about the next twelve months, not money already booked, and a large part of this cycle's estimates assumes that spending on artificial intelligence keeps expanding. Cut that assumption and the cheapness disappears on its own, without the share price moving at all.
Providers also disagree. Some show a small discount, others still show a premium of a few percentage points. What is clear is that most of the premium has been squeezed out, not that it has precisely crossed zero.
Source: Forward P/E estimates from several research providers (Image: @BrianSozzi)