From the Texas grid and a federal order to a 50-company supply chain: where the AI power bottleneck actually sits
Monthly · September 2026
The interconnection requests waiting to join the Texas grid add up to more than five times the highest load that grid has ever carried.
So the governor of Texas told them all to stop.
This happened on August 3. He wrote to the state's two power authorities and asked for a case-by-case review of every data center in the queue. Until that review is done, nobody moves forward.
The volume held up is 474 GW. Eleven days earlier, on July 22, the Texas grid had just set an all-time peak demand record of 91.1 GW, 6% above the previous record set in 2023.
About 90% of the requests in the queue come from data centers.
Texas has been the most welcoming place in America for data centers. Cheap power, light regulation, plenty of land. It hitting the brake first does not mean Texas changed. It means the scale of this thing has outgrown what the existing process can handle.
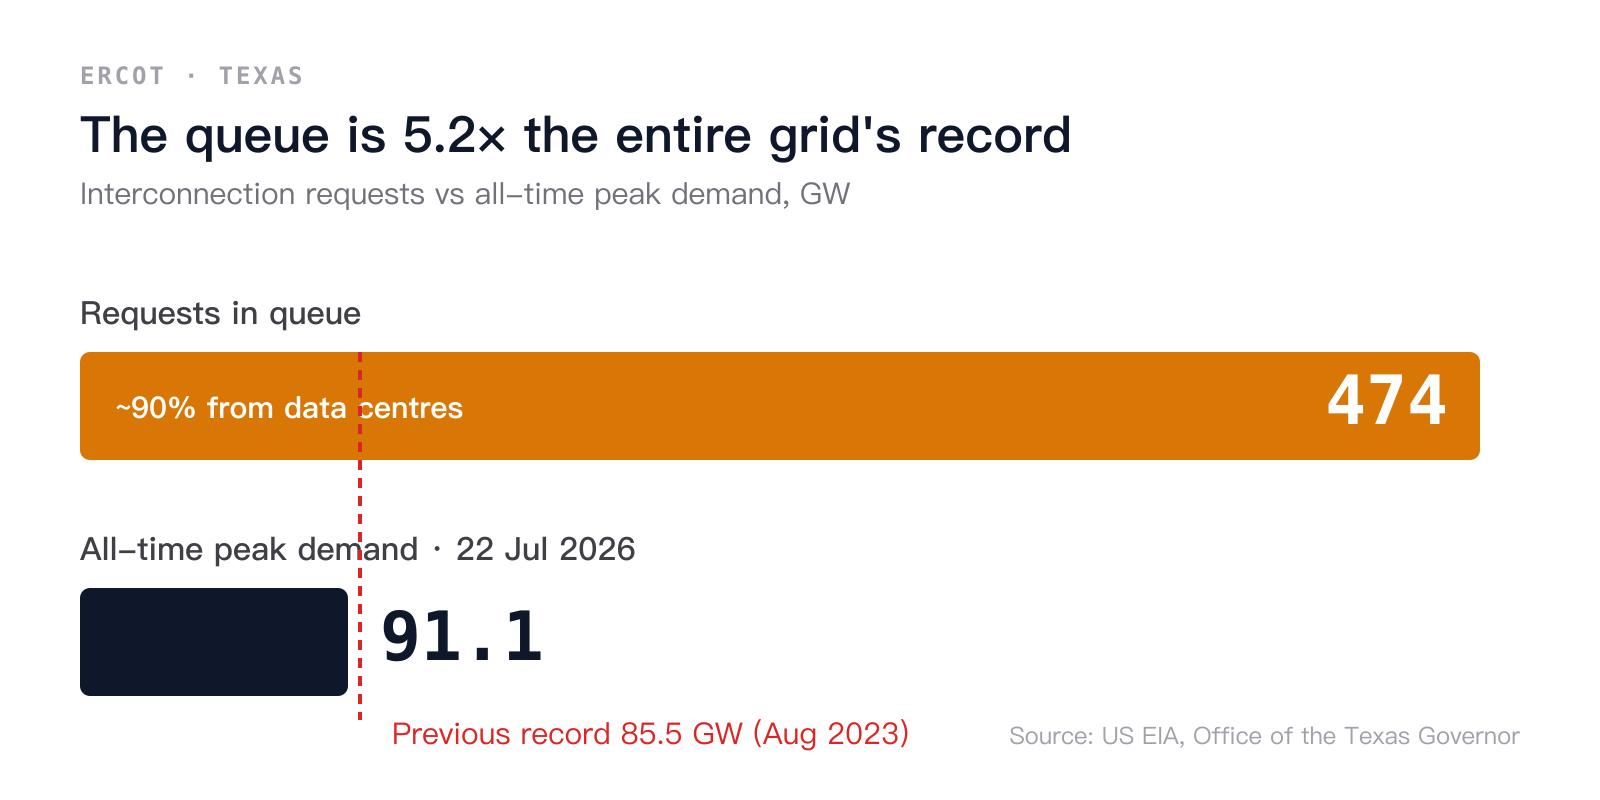
Figure 1 | The queue is more than five times the highest load in this grid's history, and roughly 90% of it comes from data centers. (U.S. Energy Information Administration, Office of the Texas Governor / LearnInvest)
▋ Eight Questions This Monthly Report Answers
The subject this month is power, but the point is not a shortage of electricity. A handful of things that happened in August turned AI's power problem from a procurement problem into a queueing problem. The first four questions are free to read; from the fifth on, it is member content.
- Q1 | Why did Texas tell everyone to stop?How much of the 474 GW is real, what the review checks, and when it finishes.
- Q2 | Even if you are allowed to connect, can you buy the equipment?Lead times for transformers, gas turbines and gensets, and why capacity cannot expand.
- Q3 | What does a 1 GW data center actually have to buy?Racks, transformers and lead times, worked through line by line.
- Q4 | What does the August 26 executive order actually reach?Which equipment it covers, when the rules arrive, and whether installed equipment is exposed.
- Q5 | Why do I think the market is looking in the wrong place?Everyone is watching transformers. Which link actually has no substitute?
- Q6 | Where is this money being borrowed from, and what changes now that rates are rising?Corporate bonds, off-balance-sheet financing, two sets of books, and who feels the September 16 hike first.
- Q7 | Which two kinds of money does Taiwan earn?Inside the rack and on the grid side: where each position comes from and how long it lasts.
- Q8 | Once the equipment arrives, will it actually run?Three problems AI data centers hit in commissioning.
At the end there are three predictions with verification dates, five numbers you can track yourself, and a full map of the supply chain: eight links and about 50 companies.
One more thing. July's report was about the pricing-power argument in AI infrastructure. August's was about a fund that went from adding capital to cutting risk in six days. This month is power. The three subjects look unrelated, but they are three faces of the same thing: the AI story is running ahead of the AI economics. July was pricing power not yet settled, August was leverage that could not survive the path, and this month is the gap between physical delivery and financing. I will keep writing this line.
▋ Why Did Texas Tell Everyone to Stop?
Because most of these requests are not real.
To keep their options open, developers routinely file at several sites at once, then decide which one to build after financing, land or a customer firms up. For a developer this is sensible risk management. It costs very little and it is worth a lot.
For a grid planner, it means the list on the desk cannot be used. You do not know how much transmission to build over the next decade, or how much substation capacity to prepare, because you cannot tell which requests are real.
The review is broader than it first sounded. ERCOT is surveying 461 data centers in total, 247 large ones at 75 MW or more and 214 medium ones between 25 and 75 MW. The questionnaire runs to about 130 questions covering local financial assistance, whether the site can generate its own power, water and cooling, community impact, and who ultimately owns it.
Water is the item most often underestimated. Lawrence Berkeley National Laboratory estimates that US data centers together use about 48 million gallons of water a day on site, but the electricity they buy uses about 578 million gallons a day at the power plant, twelve times as much, and that sits on the electricity sector's ledger. The same data center carries a very different water footprint depending on whether it is supplied by a gas plant or by wind and solar. It is no surprise the review gives water and cooling a category of its own.
The target is to finish by December 10. ERCOT officials have already said publicly that a related study originally due in April 2027 cannot be completed on schedule, and that a new timeline is still under discussion. The deadline for the first 231 large loads to respond is September 23, and the full questionnaire is due by mid-October.
Only 362 large-load projects, totalling 191.8 GW, made it into the first study batch. Another 373 projects, asking for more than 300 GW, did not make the first batch at all. The large loads that have actually finished stability assessments and are due online later this year number just 17, mostly data centers, with a combined peak of about 6.6 GW over five years.
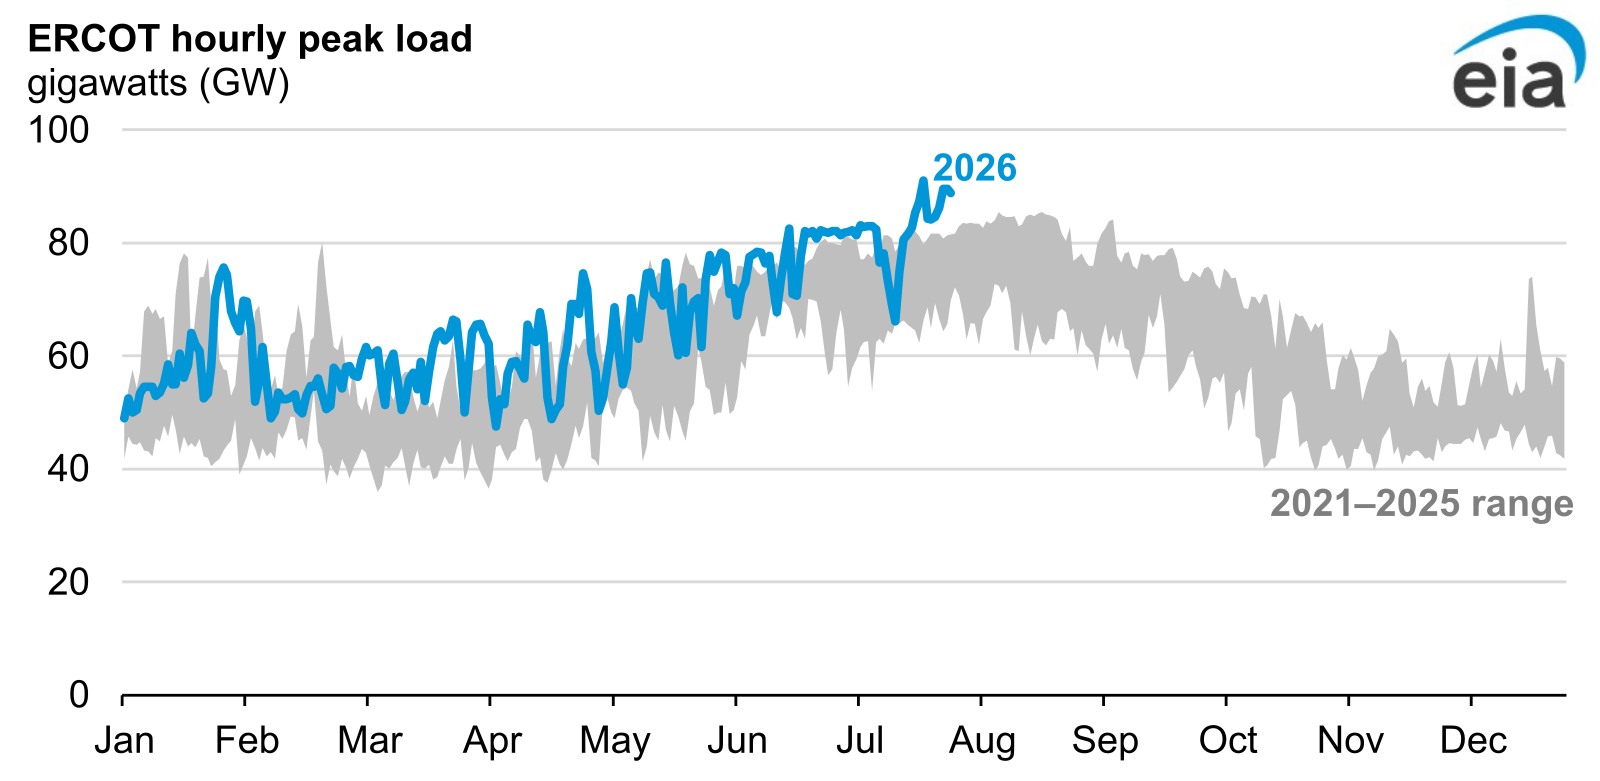
Figure 2 | The official version of the same event. The July 22 peak lifted the previous record by 6%. (U.S. Energy Information Administration, Today in Energy, August 2026)
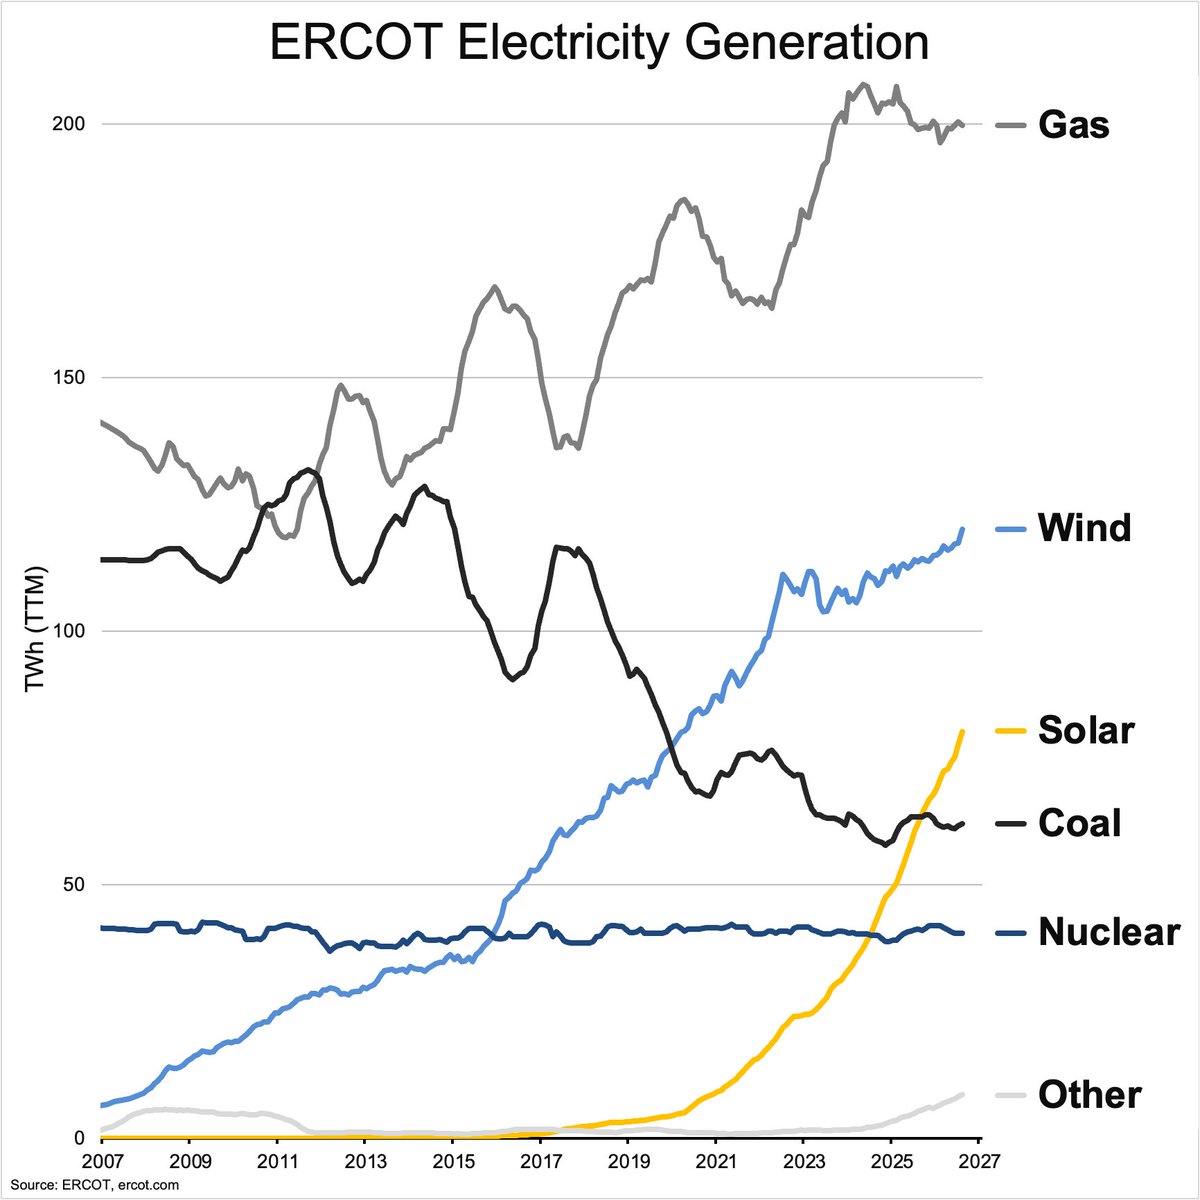
Figure 3 | Twenty years of generation on the Texas grid. Wind and solar grew fastest, but natural gas still carries this grid today. (ERCOT)
▋ Even If You Are Allowed to Connect, Can You Buy the Equipment?
No.
The average lead time for a large power transformer is 128 weeks. Order today and it arrives in 2029. Generator step-up transformers take longer, 144 weeks. Switchgear is faster, and still starts at 44 weeks.
This is not a price problem. Since 2019, power transformer prices are up about 77%, step-up transformers 45%, and some classes of distribution transformer close to 95%. Over the same period, U.S. demand for power transformers grew 116% and demand for step-up transformers grew 274%.
Prices up almost 80% and the lead time is still two and a half years. That tells you capacity genuinely cannot expand.
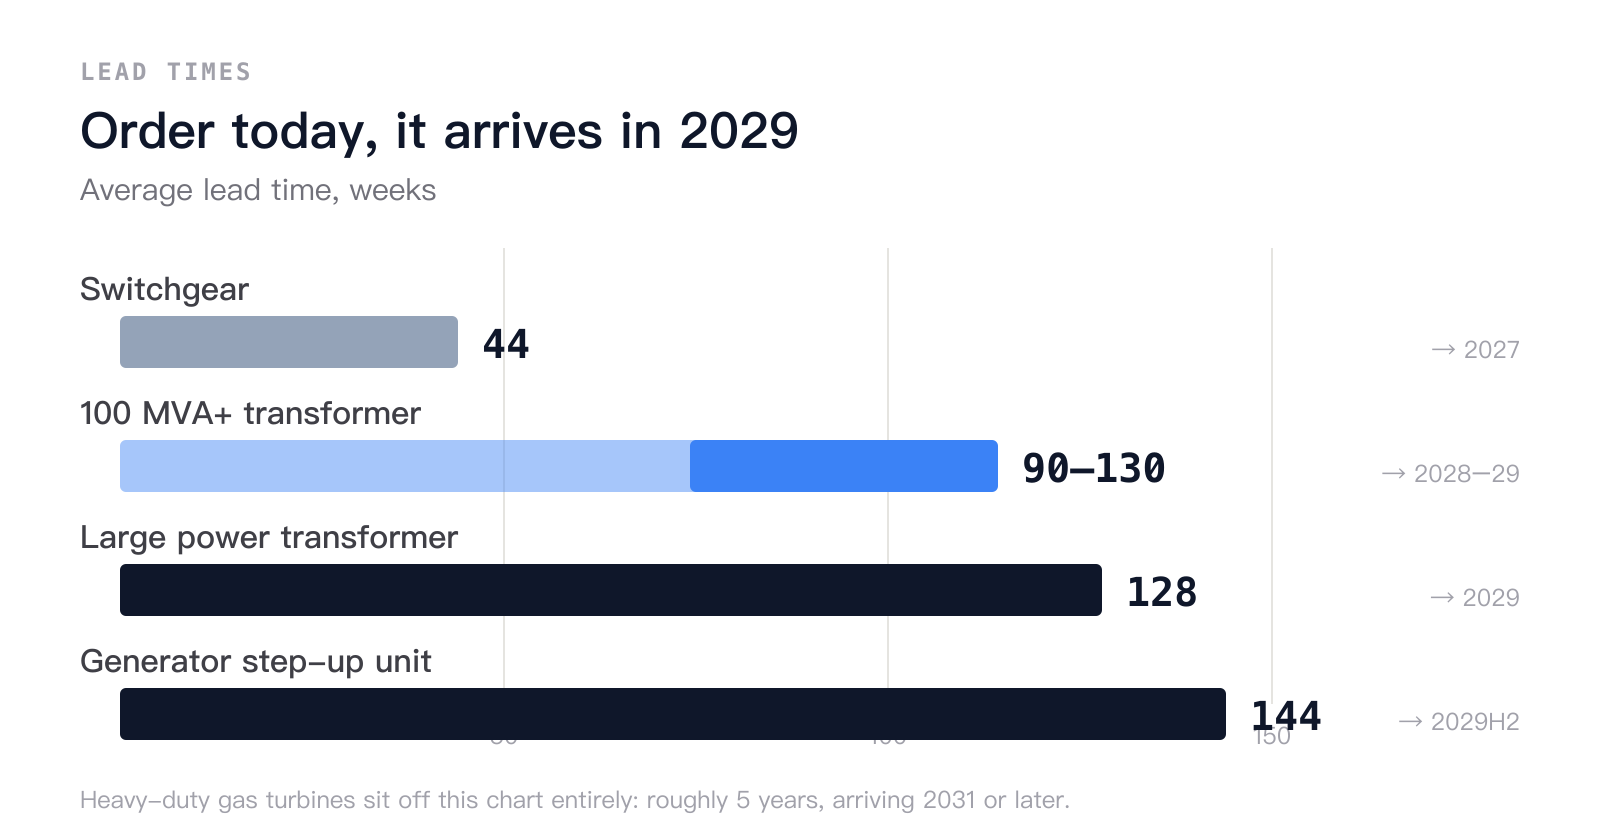
Figure 4 | Lead time, not price, is the real unit of account in this cycle. Heavy-duty gas turbines run about five years and are already off the right edge of this chart. (POWER Magazine, U.S. Department of Energy / LearnInvest)
Three Reasons Capacity Cannot Expand
First, America cannot make them. According to a Department of Energy report to Congress, more than 80% of new large transformer units above 60 MVA depend on imports.
Second, the upstream bottleneck is a type of steel. Transformer cores need a special grain-oriented electrical steel, and the thinnest grade is produced in the United States at a single plant, Cleveland-Cliffs' Butler Works in Pennsylvania. It has a $170 million expansion, but that will not be finished until 2028. Imported electrical steel faces a 50% tariff, and in 2025 the scope was widened to cover cores and laminations, which closes off the substitute route as well.
Third, and hardest to fix, transformer coils are still wound by hand. About 15,000 skilled workers in the United States do this work. You cannot solve that by building a production line. It takes years of training.
What About Generating Your Own Power Instead?
That route is also a queue, and a shorter one with fewer places in it.
Only three companies in the world build heavy-duty gas turbines. GE Vernova's gas turbine backlog has reached 116 GW, with delivery slots sold into 2030. Mitsubishi Heavy Industries said publicly in July that turbine delivery takes five years, that its order book is full through 2030, and that it is now signing slots for 2031 to 2034. Siemens Energy's gas backlog is 69 GW, with annual capacity of 35 large units and another 15 to be added in 2027, against an annual market of roughly 120 GW.
The diesel and gas genset side is the same. Caterpillar's generator orders are booked into 2030, and Cummins' large unit allocation has slipped into 2028 with lead times of 40 to 107 weeks.
A data center breaking ground today cannot count on new heavy equipment to power it.
Even signed contracts do not guarantee delivery. The International Energy Agency counts about 13 GW of firm power purchase agreements signed by data centers, against about 44 GW of conditional offtake agreements, almost all of it tied to small modular reactors that have not been built.
The peak explains why everyone is crowding into gas. In the highest-demand 1% of winter hours on the Texas grid, natural gas supplies an average of 41 GW, against 9 GW from wind and 5 GW from solar. A large new load has to be served in the coldest hours too, and today the peak is still carried mainly by gas.
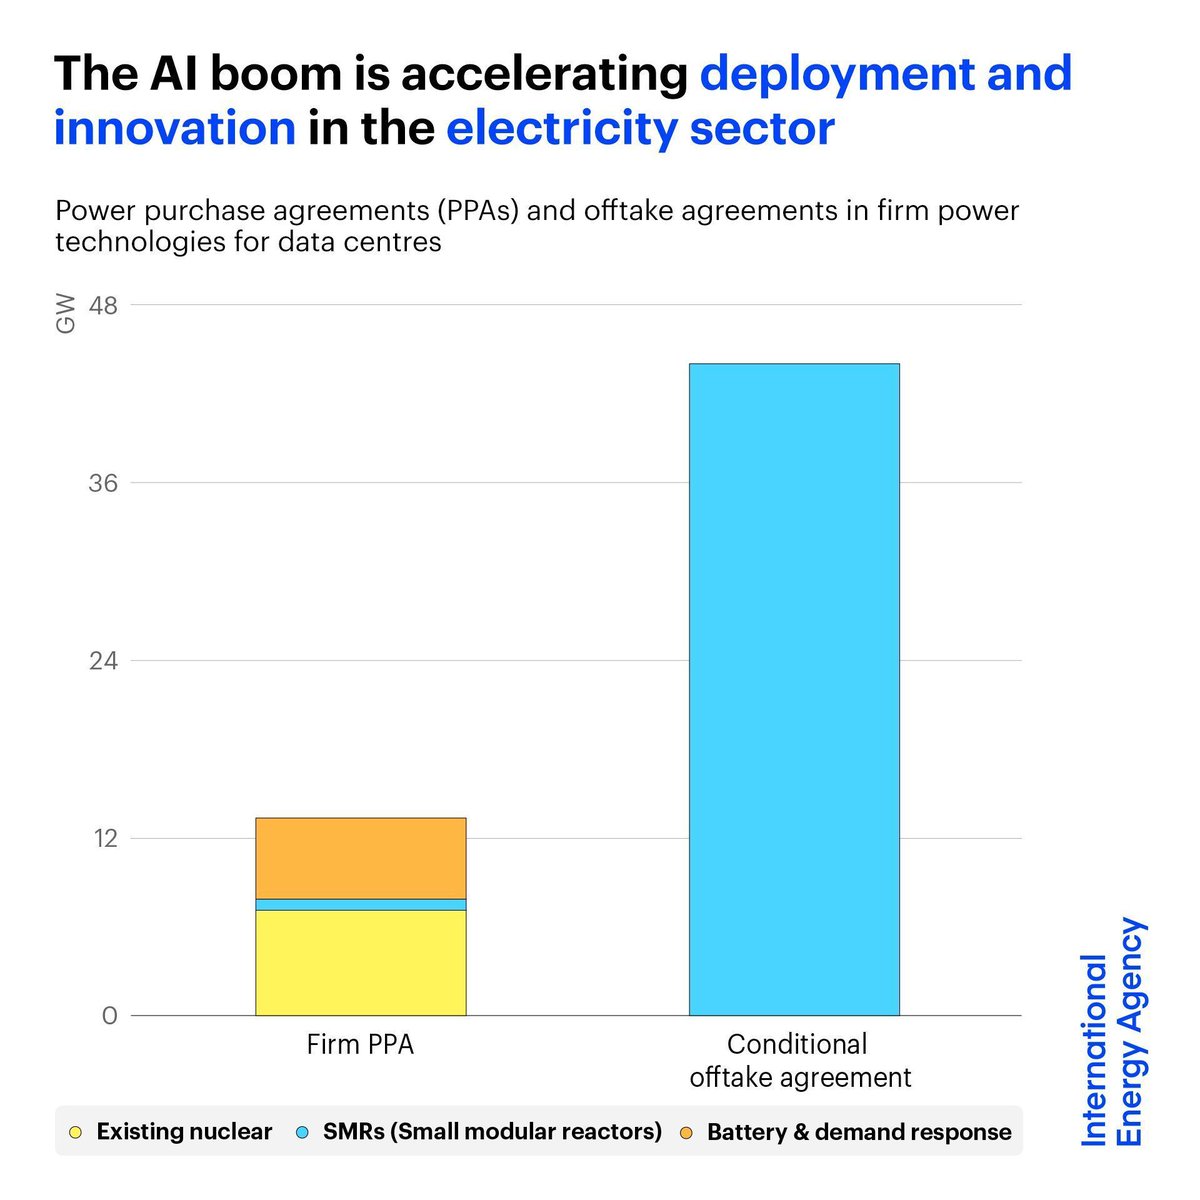
Figure 5 | Conditional offtake agreements are more than three times the firm power purchase agreements. A signed contract is not the same as power arriving. (International Energy Agency)
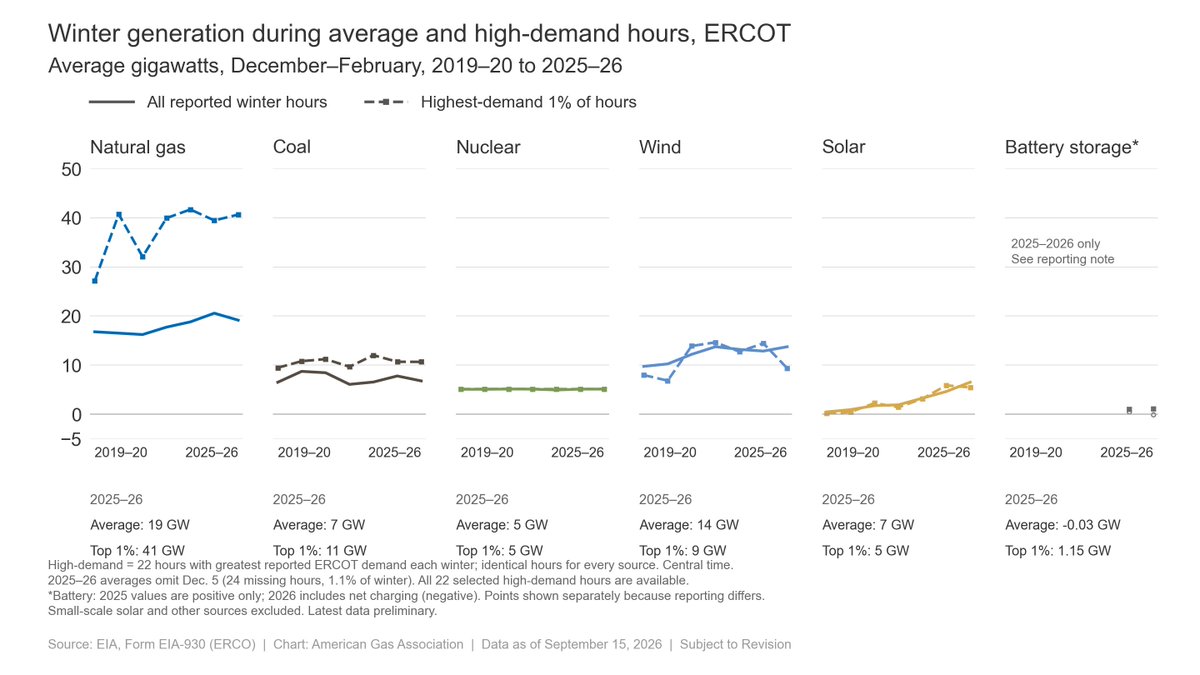
Figure 6 | In the highest-demand 1% of winter hours, natural gas carries most of the Texas grid. What new load ultimately leans on depends on who carries the peak. (U.S. Energy Information Administration EIA-930; chart by the American Gas Association)
And This Is Not Only Texas
Berkeley Lab compiles interconnection queue data from more than 50 U.S. grid operators each year, covering about 98% of existing U.S. generating capacity. As of the end of 2025, roughly 8,200 projects were in the queue nationwide, totalling 1,312 GW of generation plus 749 GW of storage.
In 2025, gas generation capacity in the queue grew 86% to 253 GW. In the same year, solar fell 19%, storage fell 16% and wind fell 19%.
Everybody is running in the same direction: find a way that does not require waiting for the grid. And gas turbine slots being sold out past 2030 is the other side of that same demand.
The limits do not only come from the grid either. According to industry tracking, as of September 1 more than 300 local data center moratoriums had been enacted across the United States, covering about 20 GW of campuses inside restricted boundaries, and New York's statewide order is holding up another 0.8 GW. The capacity that can be specifically counted as delayed is at least about 2.3 GW, and that is before Texas and Pennsylvania are included.
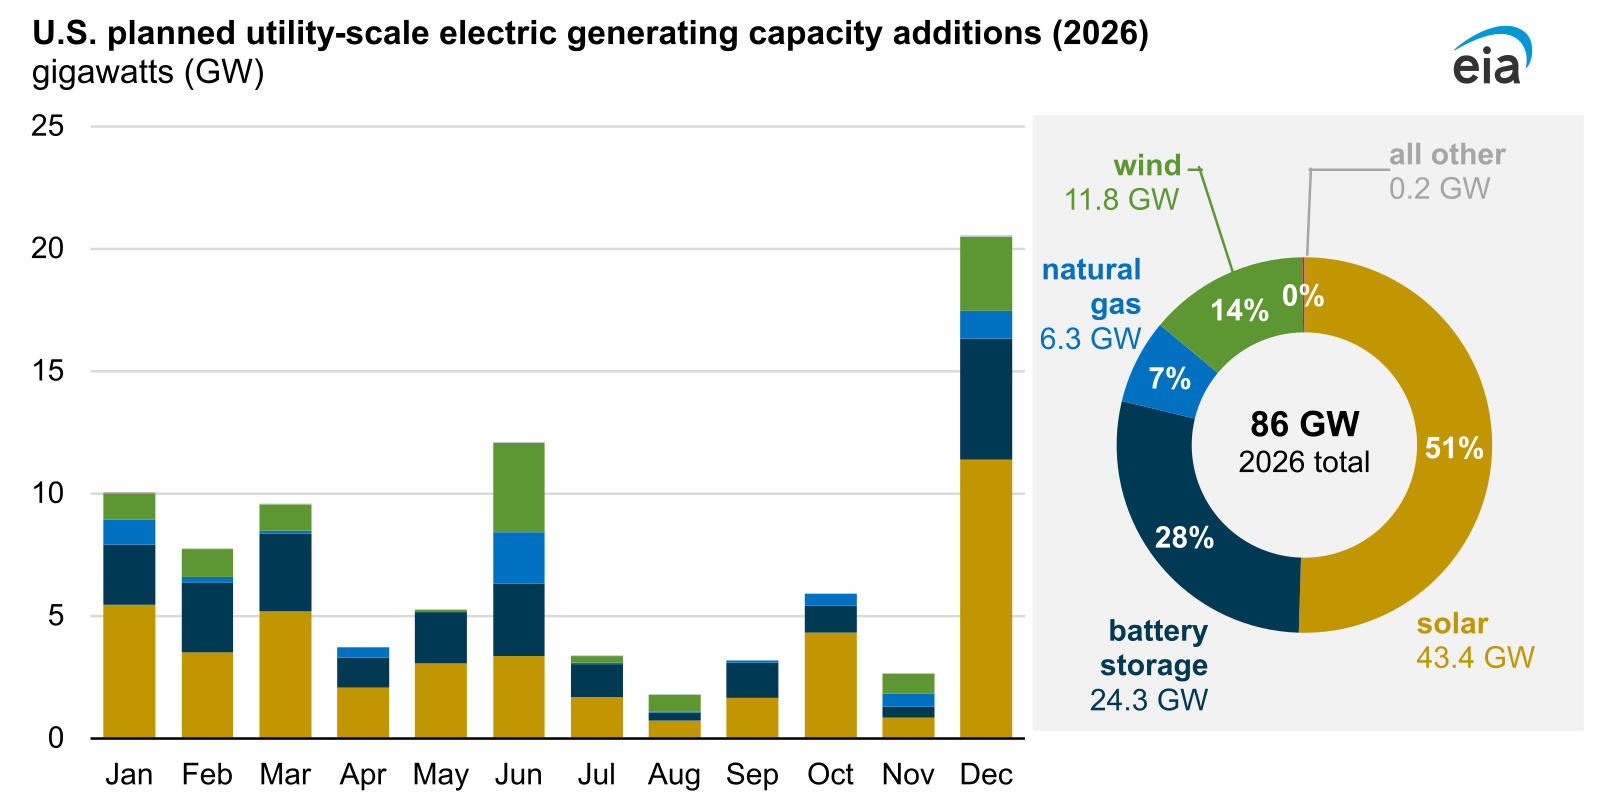
Figure 7 | Planned U.S. generating capacity additions hit a record 86 GW in 2026. Storage accounts for 24 GW of that, the second largest source. This is also why the tax rule discussed later, which lands on storage, has such a direct effect. (U.S. Energy Information Administration, Today in Energy, February 2026)
▋ How Real Is the Demand?
These lead times sound like an industry complaint. Lay the demand-side numbers out and you find they are two sides of the same thing.
Start with usage. A third-party platform that routes requests across many model providers processed 113 trillion tokens a week, up from 4.6 trillion a year earlier, about 25 times, and it doubled again in the last four weeks. That is one platform and cannot stand for the whole market, but the direction is clear: usage is not slowing.
Usage ends up as electricity. The International Energy Agency estimates electricity use by AI data centers rose about 50% in 2025 and will triple from the 2025 level by 2030. The weight falls hardest on the United States, where data centers already use about 5% of all electricity generated, against a global average of 1.5%.
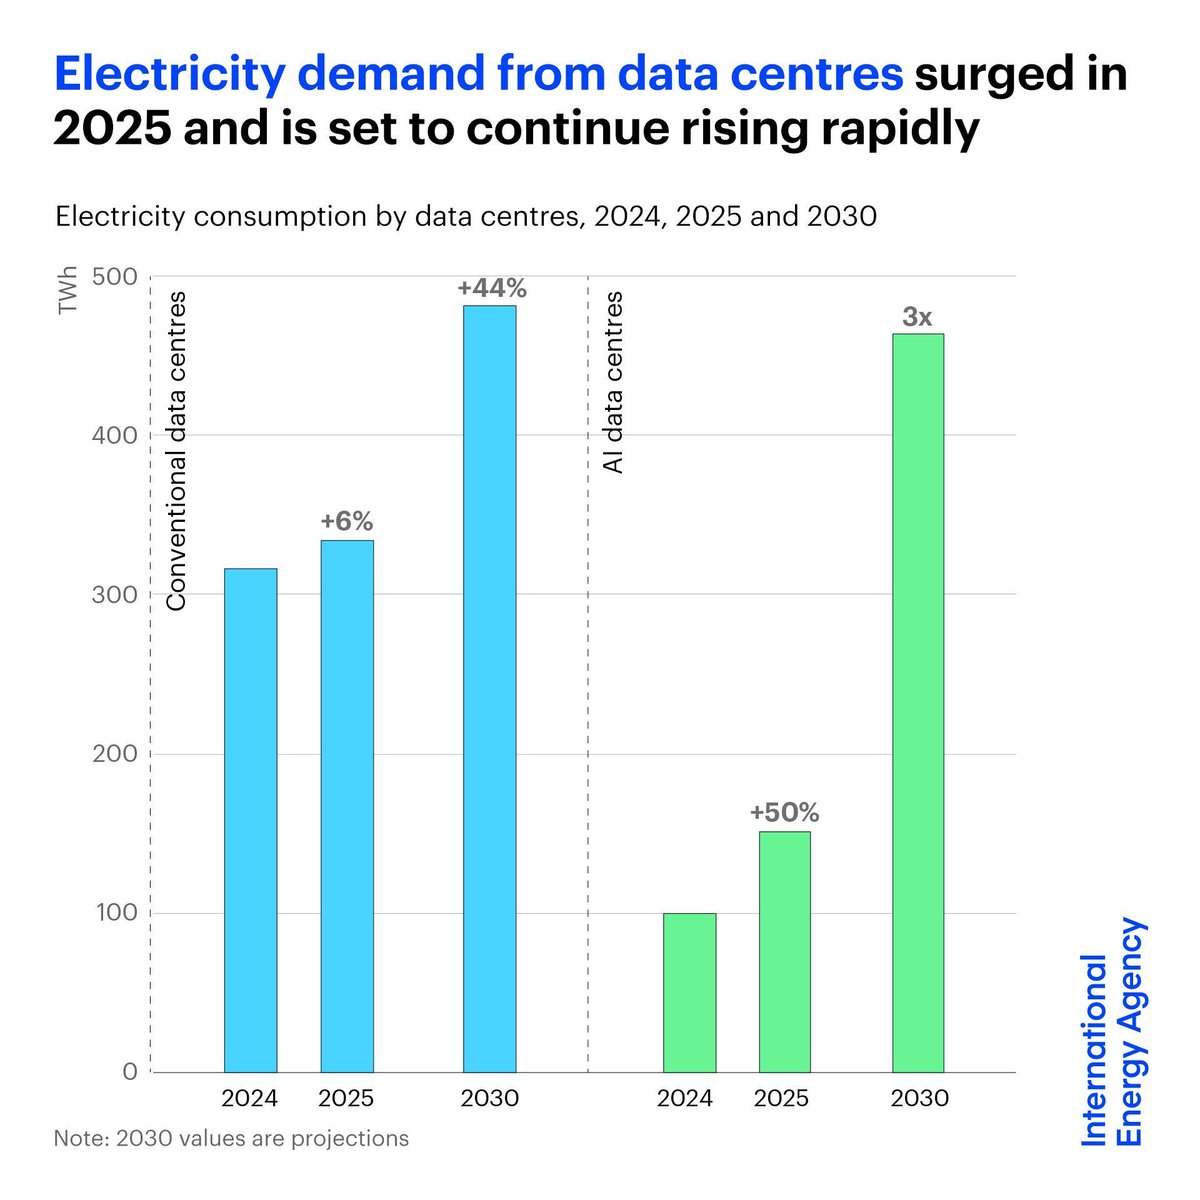
Figure 8 | Electricity use by AI data centers rose about 50% in 2025 and is projected to triple from the 2025 level by 2030, against roughly 44% growth for conventional data centers over the same period. (International Energy Agency)
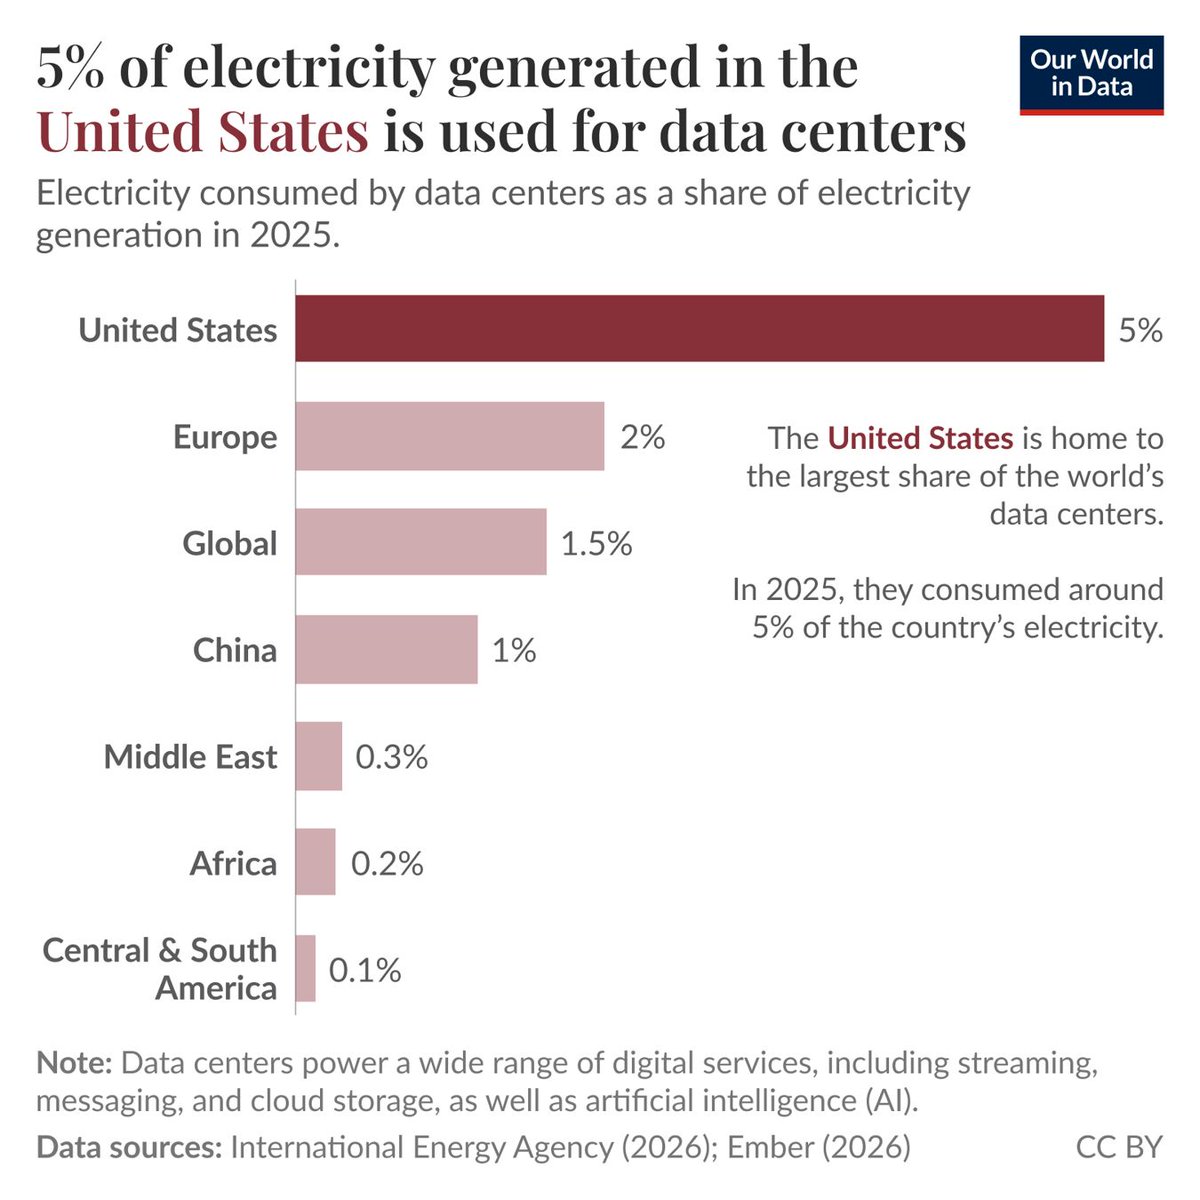
Figure 9 | Data center electricity as a share of generation in 2025: about 5% in the United States, about 2% in Europe and about 1% in China. The same growth rate weighs most heavily on the US grid. (Our World in Data, based on International Energy Agency and Ember data, CC BY)
Then look at the equipment makers. Eaton said on its second-quarter call that total U.S. data center orders amount to 307 GW, which at the 2025 build rate is 15 years of work. In the same quarter its data center revenue grew 65% year on year and its unshipped order book grew 103%. For every $1.20 of new orders it takes in, it ships $1.00, and in the Americas the ratio is 1.3 to 1. Booking faster than shipping means the backlog is still building.
GE Vernova booked $24.2 billion of new orders in the second quarter, up 88%, and its backlog reached $176 billion, close to four times its annual revenue. Equipment backlog in its electrification segment grew 69%, data center orders were $2.7 billion in the quarter and more than $5 billion in the first half, already more than double the full year of 2025.
And then there is Caterpillar.
Caterpillar's second-quarter backlog hit a record $72.1 billion, up 92% year on year. In the same report, its factory spending rose 4%.
The order book nearly doubled in a year and the money spent on building factories went up 4%. Those two numbers are printed on the same page, and the distance between them is the real story of this round of AI power investment.
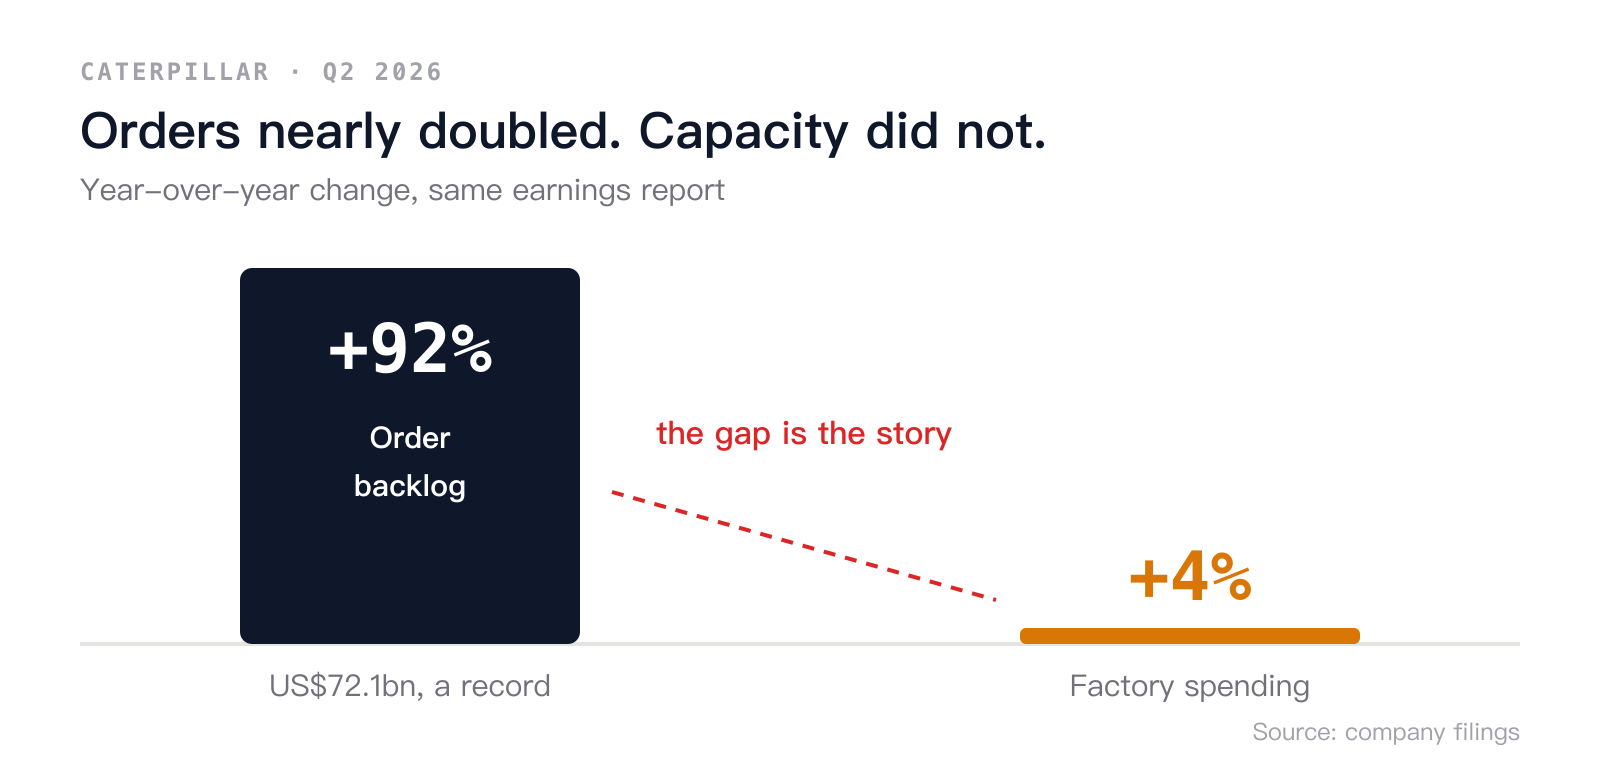
Figure 10 | The gap between the demand side and the supply side is written into the same set of financial statements. (Company filings / LearnInvest)
GE Vernova also states that most of the revenue from that $176 billion backlog will not be recognized until after 2028.
▋ What Does a 1 GW Data Center Actually Have to Buy?
Each of these numbers means something on its own. Put them together and you get the scale. So here is my own calculation, with the assumptions on the table, and you can change them and redo it.
A 1 GW facility draws about 1.2 times its compute load in total, with the other 0.2 going to cooling, lighting and the rest. So the actual compute load is about 833 MW. At about 132 kW per GB200 rack, this data center holds roughly 6,300 racks.
For transformers, there is a real case to anchor on. CloudHQ's 225 MW campus in Illinois installed four 100 MVA transformers in its new substation. Scaled to 1 GW on the same ratio, you need about 1,780 MVA of transformer capacity, which is 18 main transformers in the 100 MVA class.
And transformers above 100 MVA have lead times of 90 to 130 weeks.
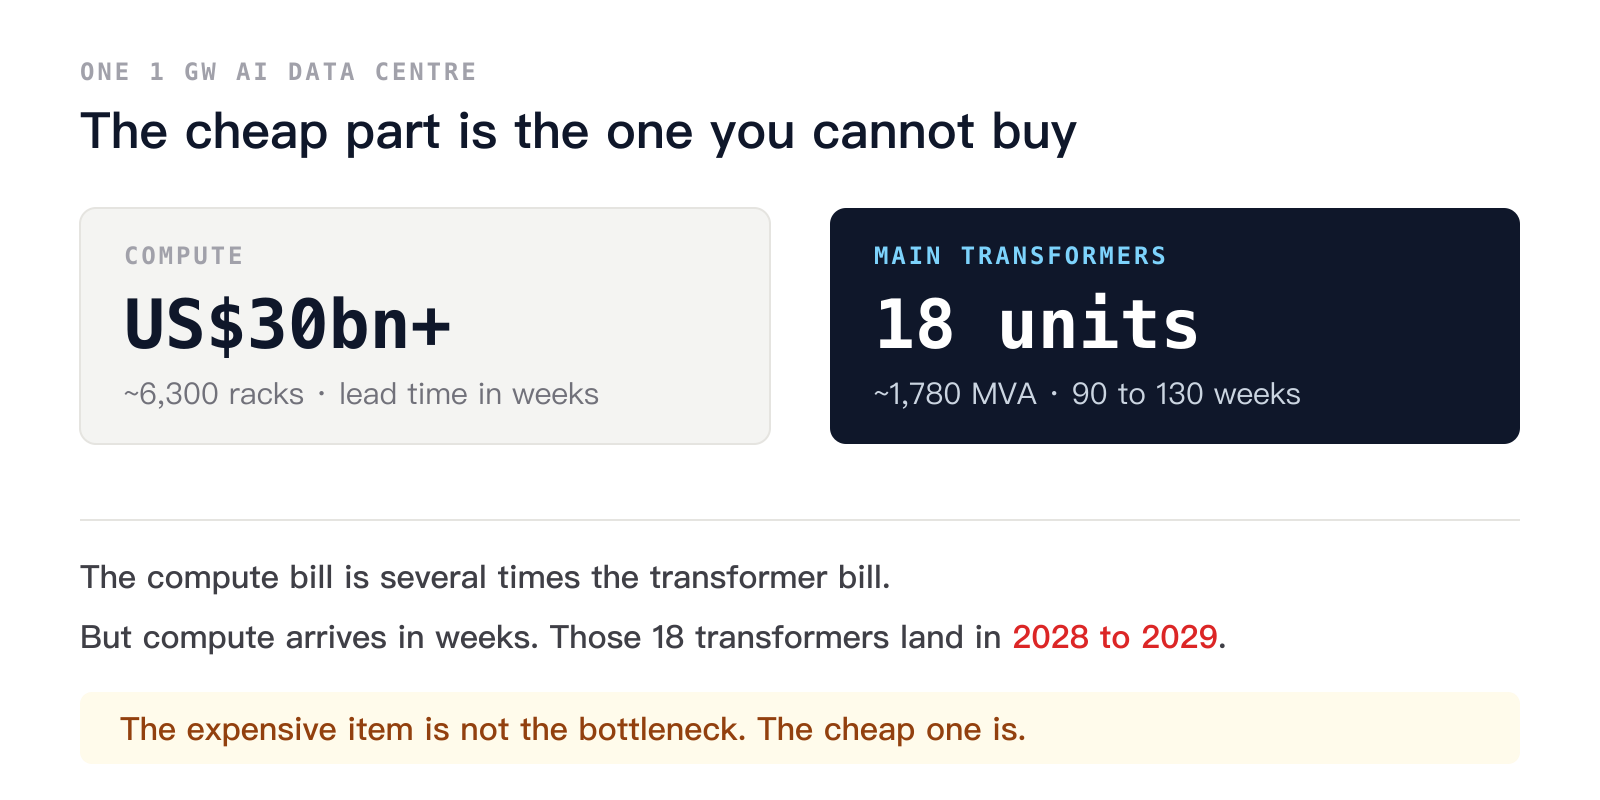
Figure 11 | This is my own calculation with the assumptions stated in the text, and you can change the numbers and redo it. There is more than one 1 GW campus in planning worldwide today, and every one of those sets of 18 transformers has to stand in the same queue. (Public cost guides, project case studies and author calculation / LearnInvest)
The compute equipment costs more than three times what the transformers cost, but the compute equipment takes one tenth of the lead time. The expensive item is not the bottleneck. The cheap one is.
▋ What Does the August 26 Order Actually Reach?
Three weeks after Texas, the United States issued an executive order on national security grounds that brings high-voltage equipment connected to the grid under control.
The scope is transmission facilities at 69 kV and above, plus generating equipment needed to maintain system reliability. Local distribution is not included.
The list of covered items is broader than the market first understood. Beyond transformers, circuit breakers, grid-tied inverters, storage systems and generators, the order explicitly covers the software, firmware, remote access capability and maintenance arrangements attached to that equipment.
In other words, it governs not only who made the machine but who will maintain it. A transformer can be assembled in the United States, but if its monitoring module updates from an offshore server, or its remote diagnostics are handled by an offshore team, it still sits inside the risk the order describes.
And then the key point: the order names no countries.
Who counts as a restricted party, which equipment gets heightened review and how the licensing process works are all left to the Department of Energy to publish within 120 days, meaning before December 24.
The Department of Energy opened a request for information on September 9, with comments due October 9, and battery storage is named explicitly in its questions. One provision deserves more attention than it has had: for equipment already installed on the grid, the Secretary can require ongoing monitoring, physical or network isolation, or replacement and removal.
Lay the timeline out: July 22, Texas sets a demand record. August 3, the governor freezes 474 GW of requests. August 26, the federal order lands with the rules undefined. October 9, the Department of Energy's consultation closes. December 10, the Texas review is due. December 24, the Department of Energy rules are due.
Inside one month, from record to brake to national security control. And there are still three months until the rules exist. During those three months, every contract for 2029 delivery is being signed without knowing what the rules will say.
▋ Why Do I Think the Market Is Looking in the Wrong Place?
If you only look at the August order, you conclude that the rules are not written yet, so there is still time. That conclusion is wrong.
The member section goes on to answer:
- Everyone is watching transformers. Why do I think the real risk sits somewhere else?
- The cloud giants have already issued $218.7 billion of bonds this year. Who feels the September 16 rate hike first?
- What lines up with the 1999 fiber buildout, and what does not?
- Taiwanese suppliers sit at both ends of this chain. Which position lasts longer?
- Three predictions with verification dates, five numbers you can track yourself, and a full map of eight links and about 50 companies.
Member content starts here
The Complete Report Is For Members
You have reached the end of the free preview. Sign in with Pro to continue with the complete research and charts.