本週文字版重點
W45 週報|費半一週跌 12.1%,布蘭特跌 13.3%
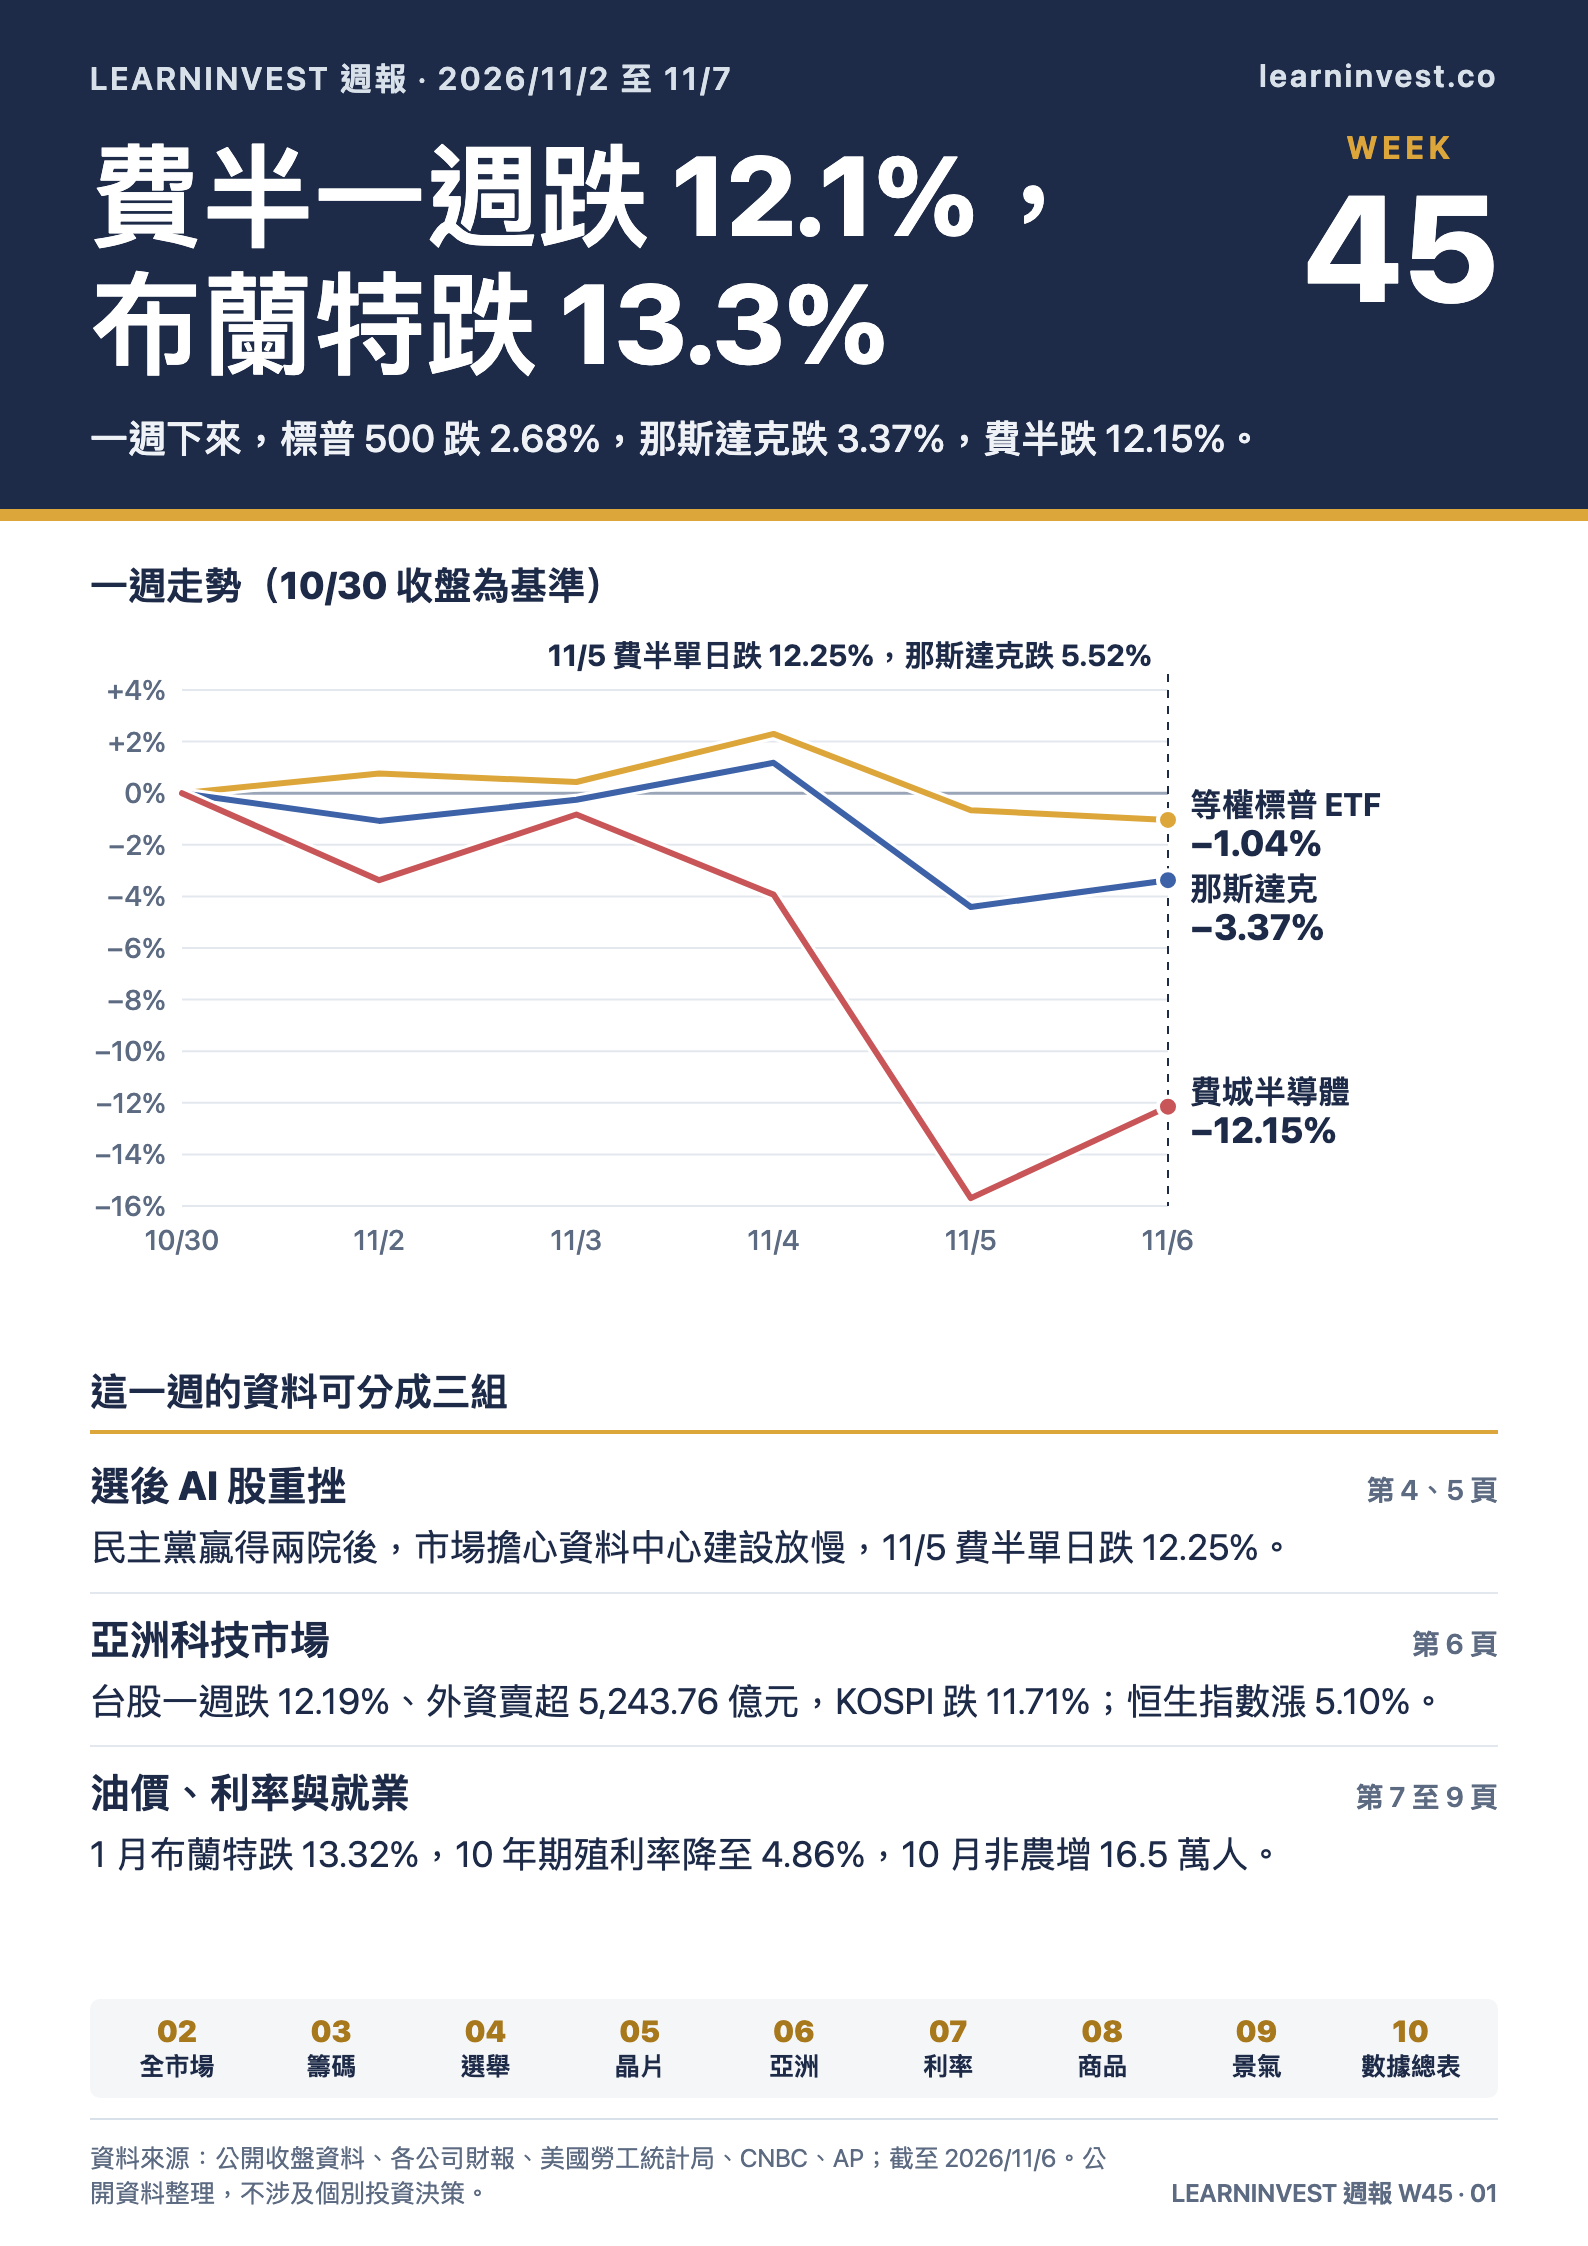
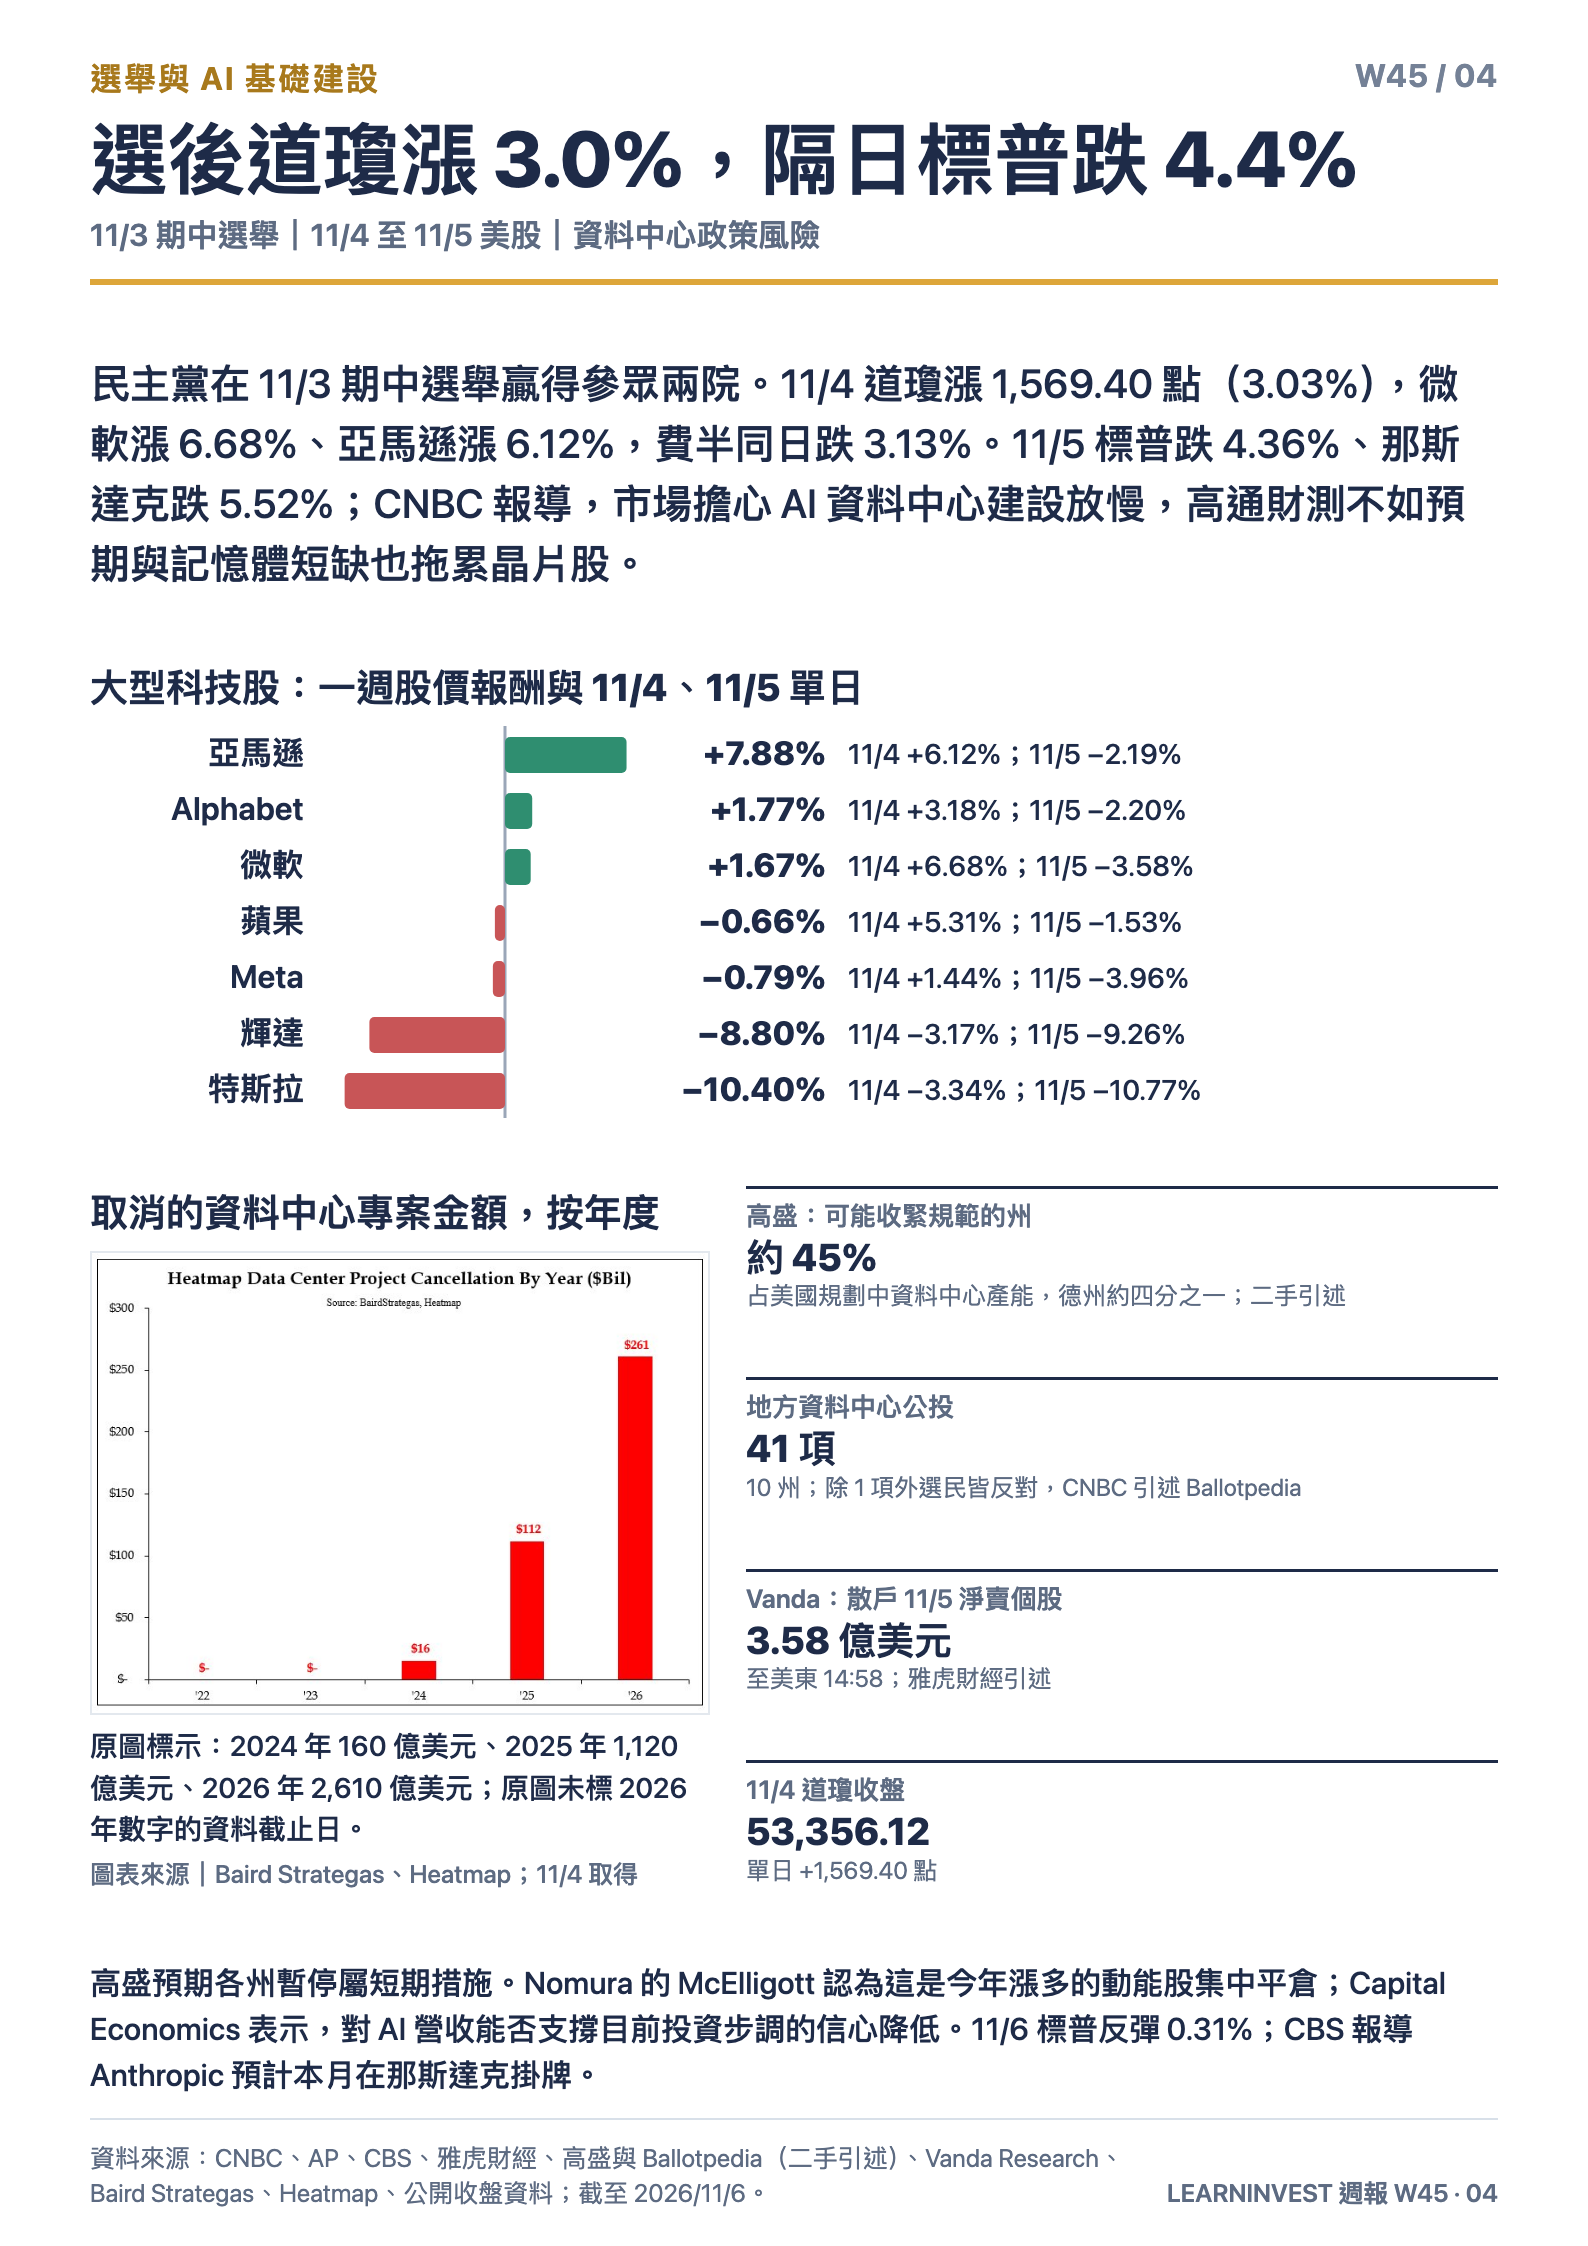
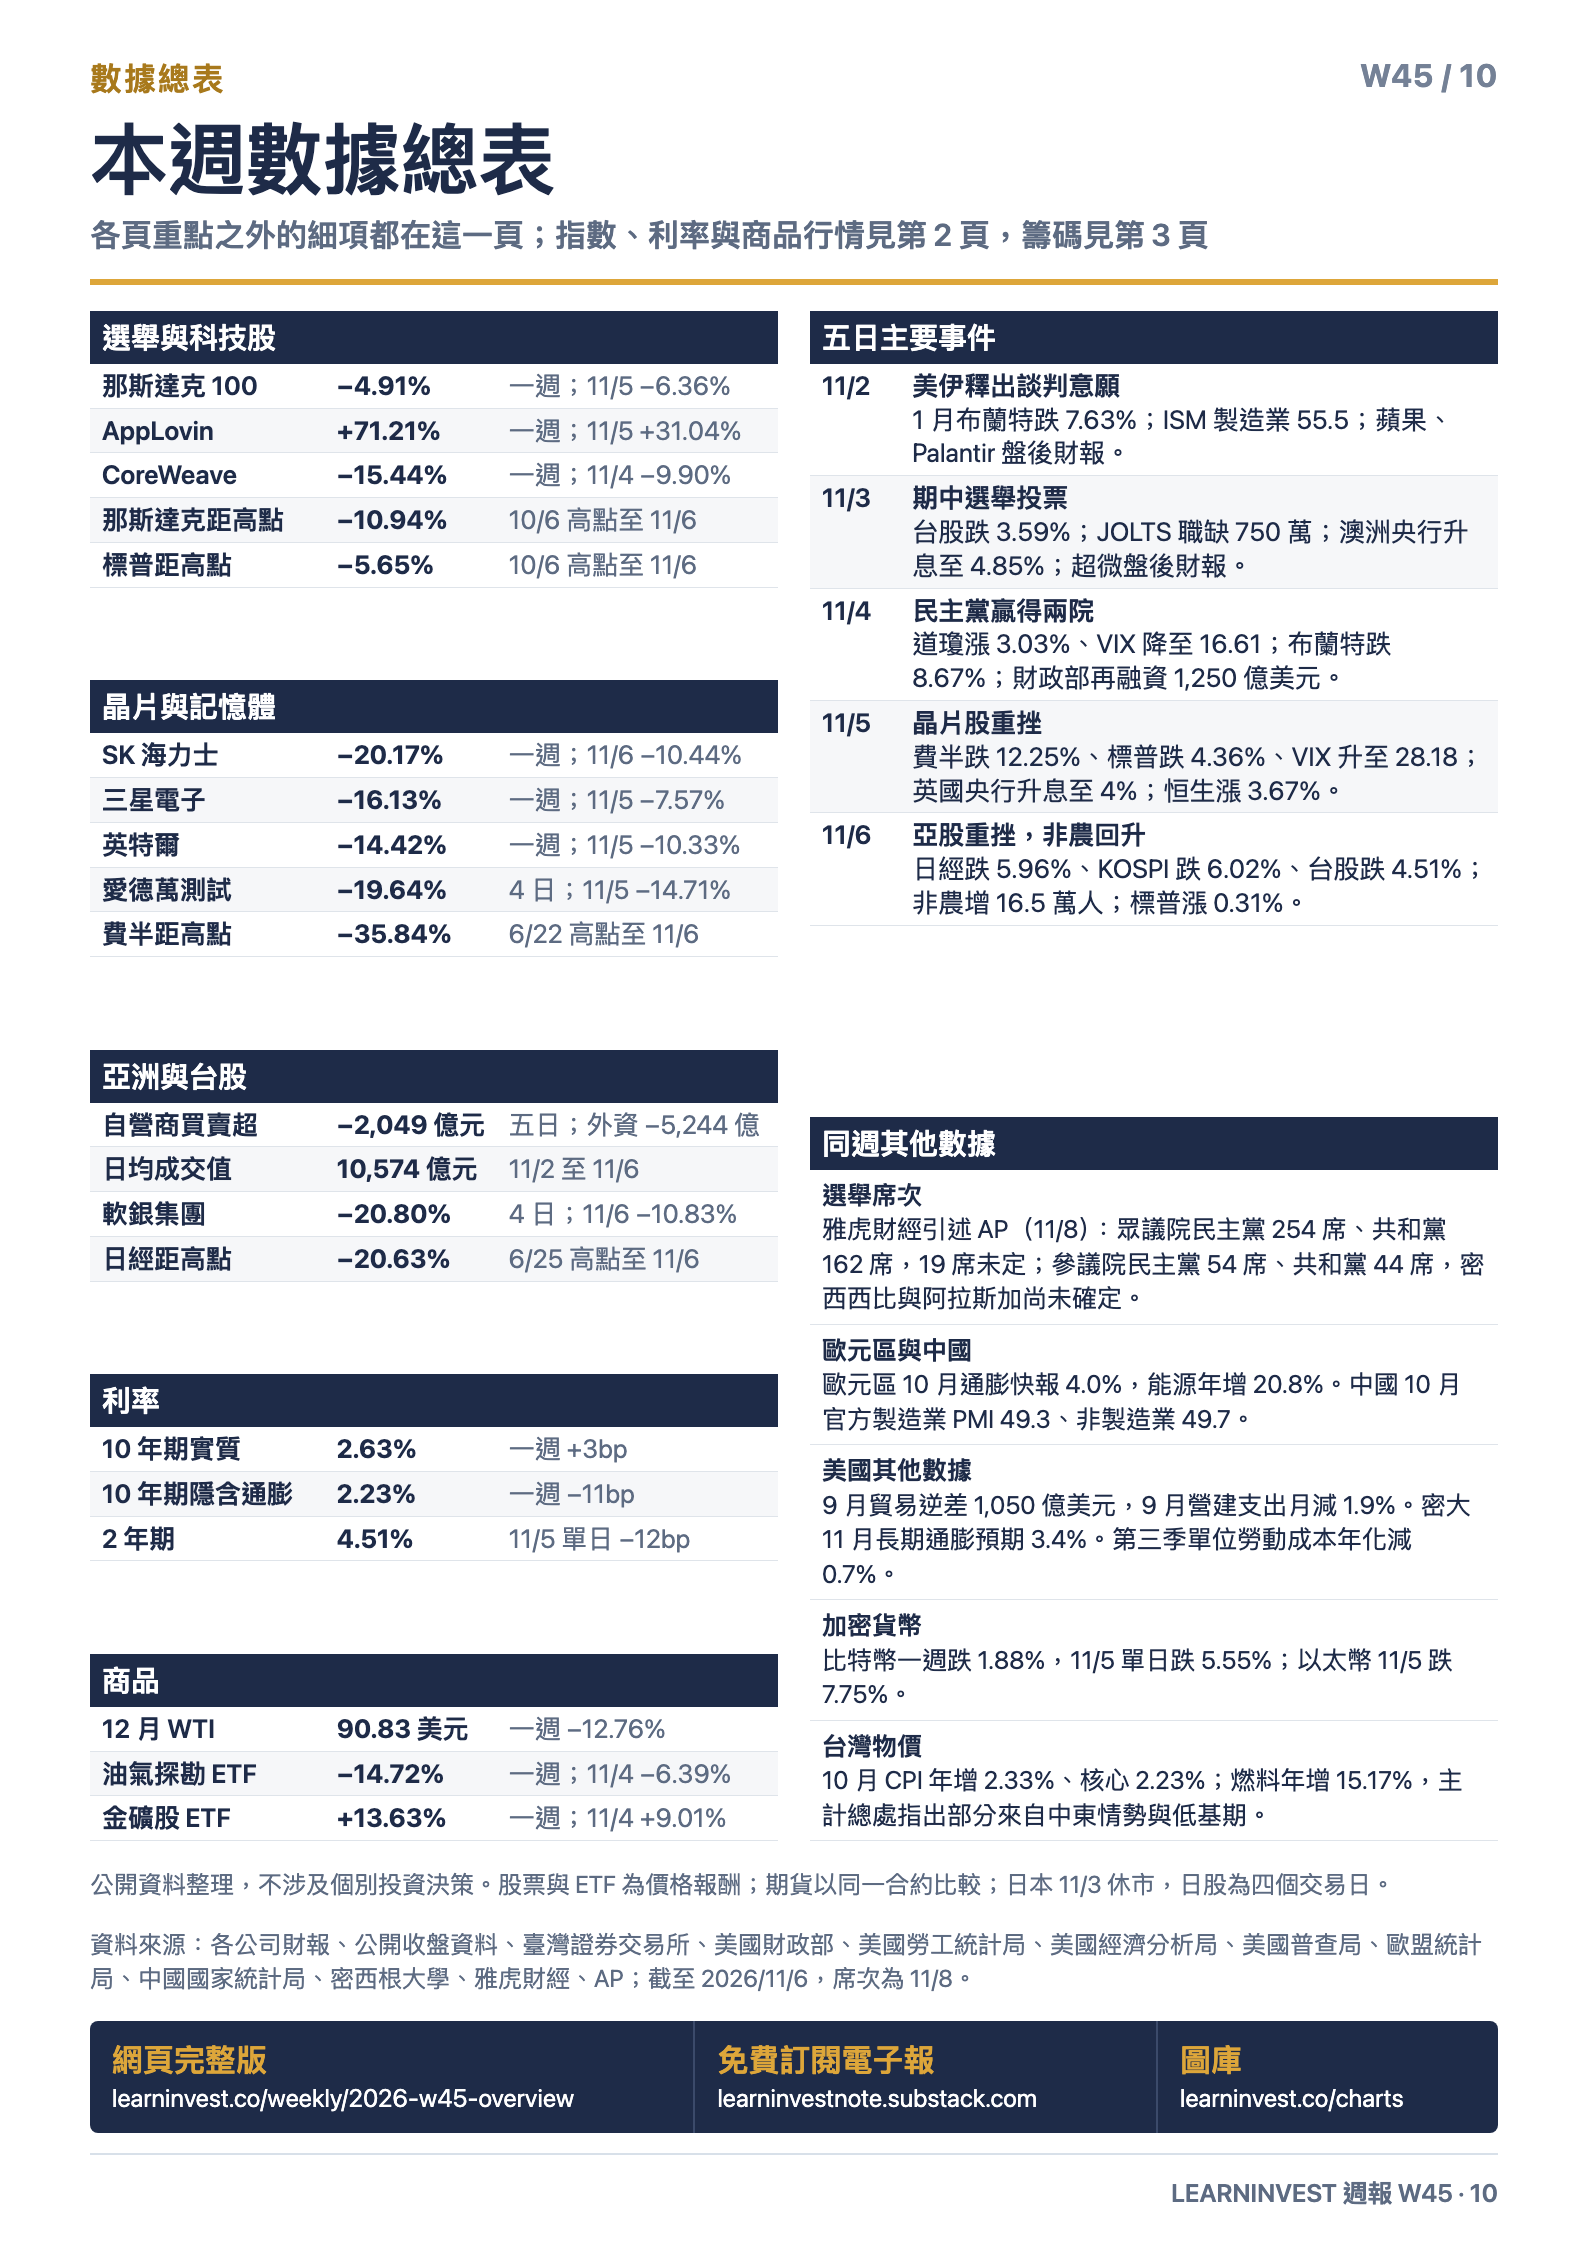
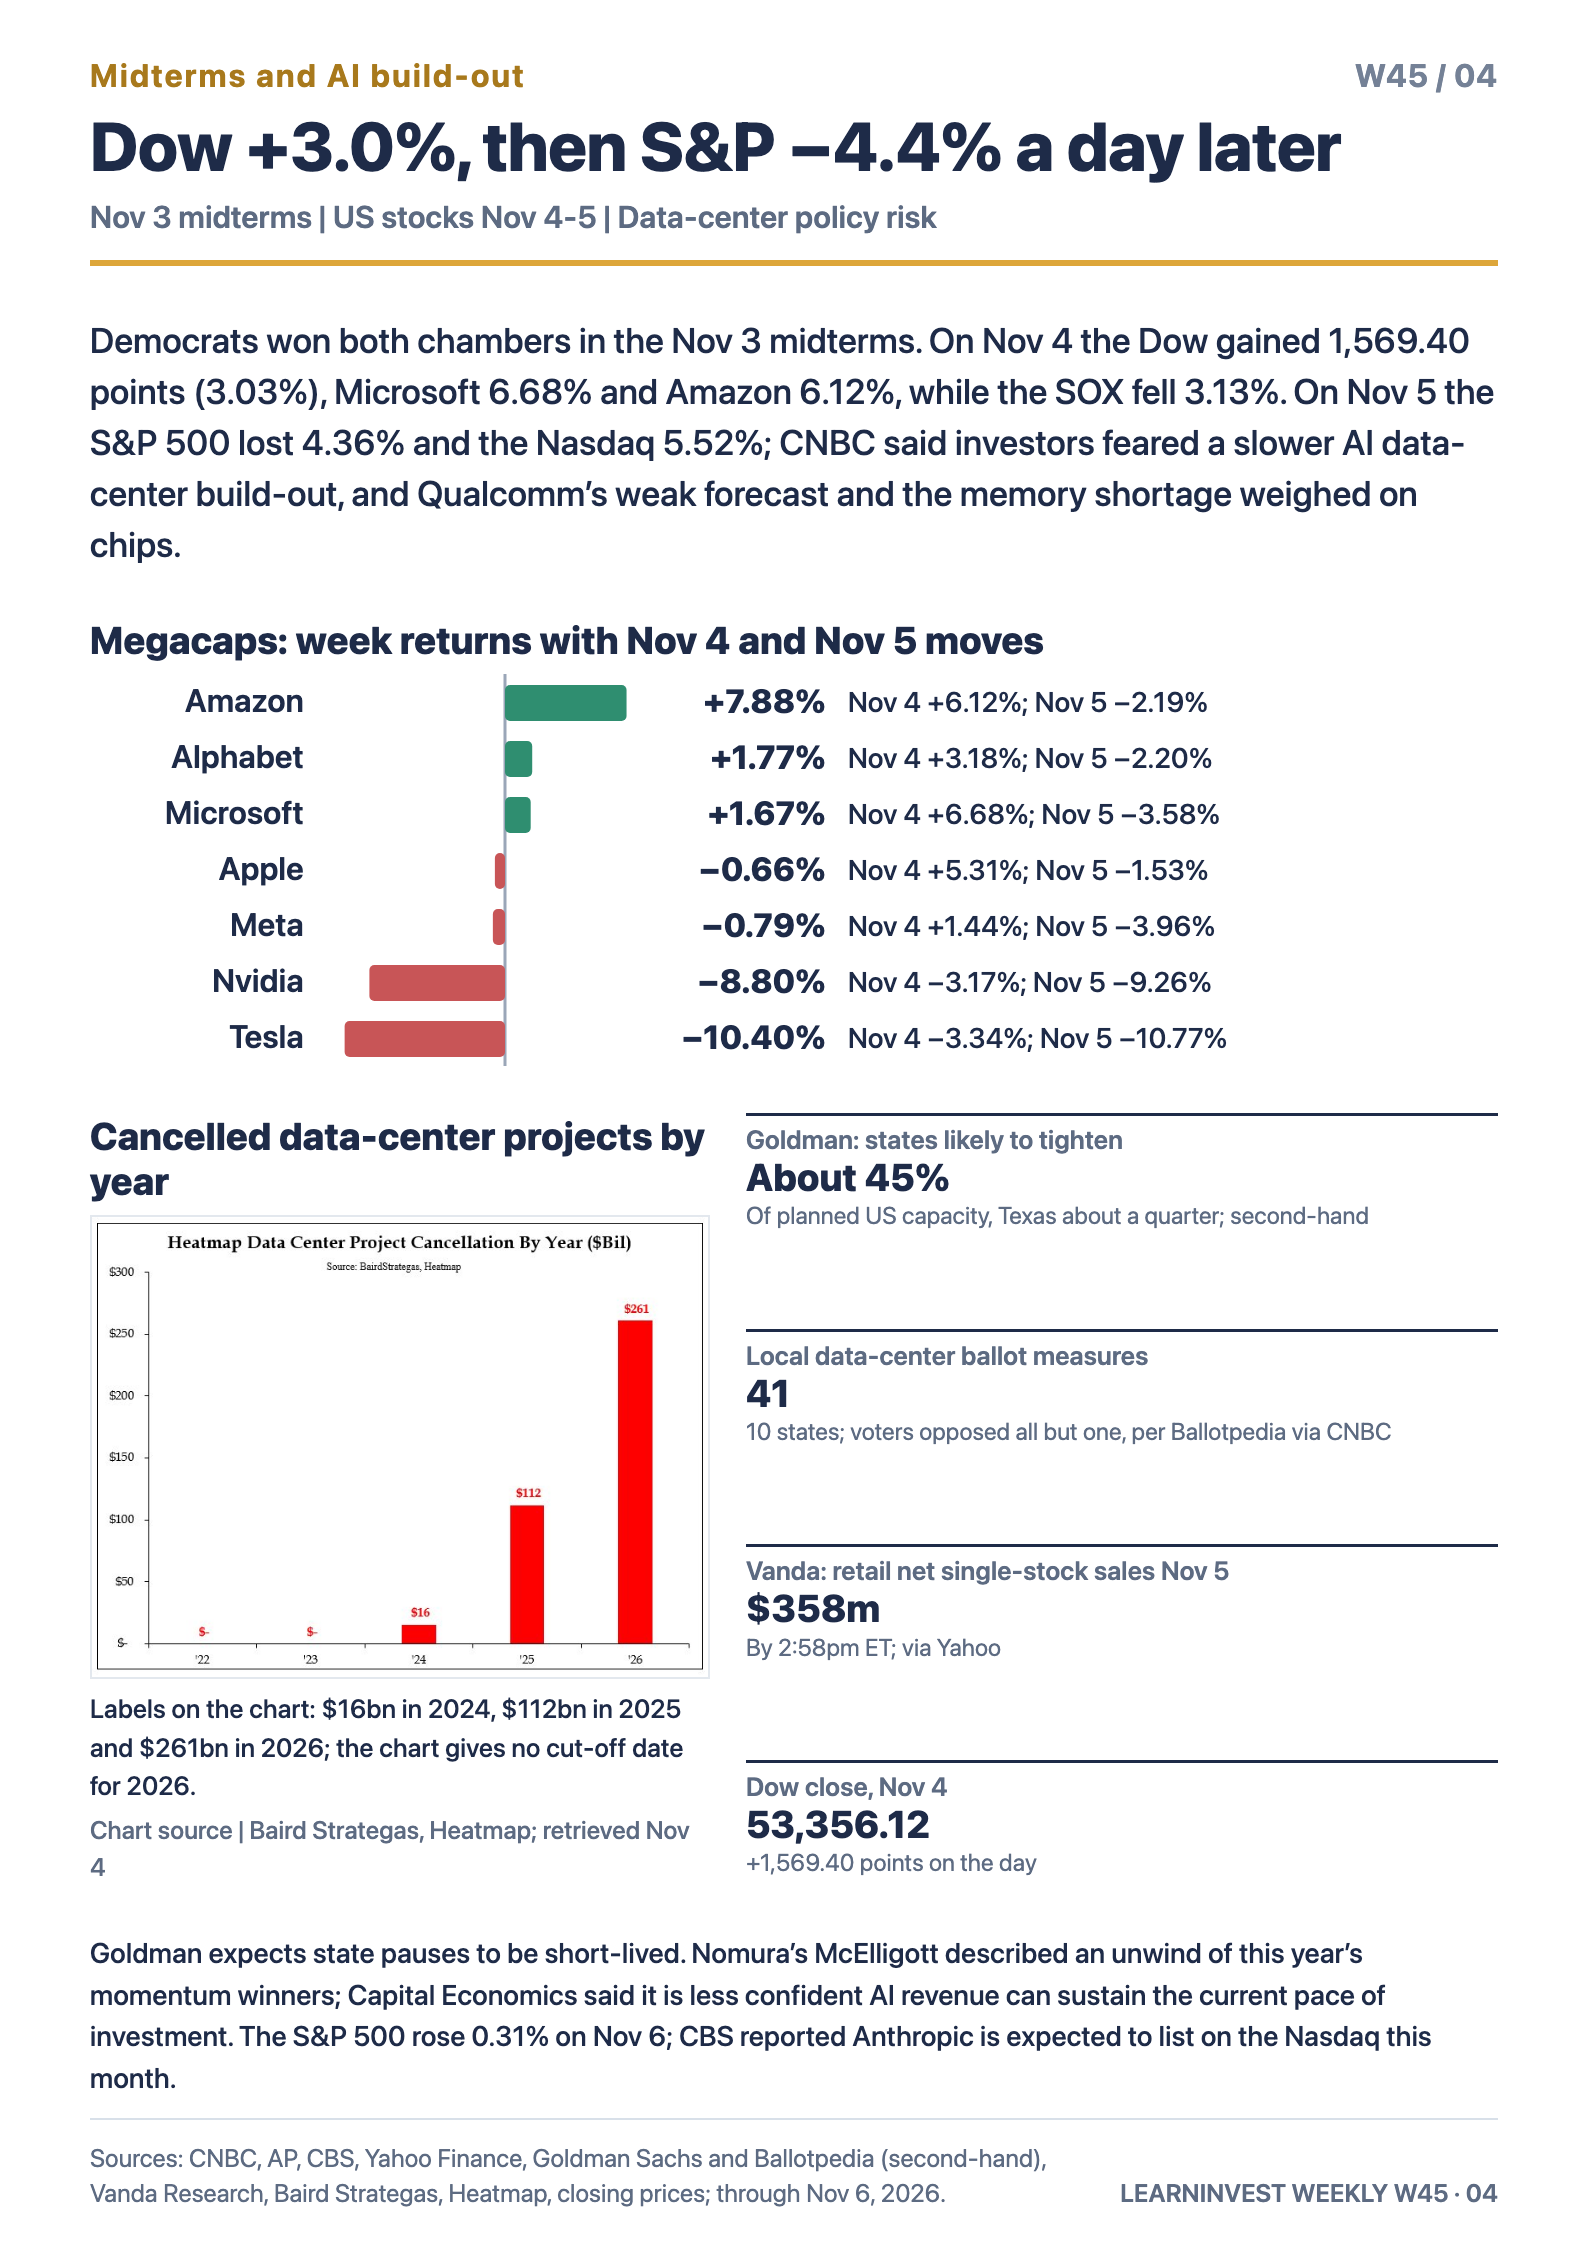
這週的關鍵在 11/4 與 11/5。民主黨在 11/3 期中選舉贏得參眾兩院,11/4 道瓊漲 1,569.40 點(3.03%),微軟漲 6.68%、亞馬遜漲 6.12%。隔天 CNBC 報導市場擔心 AI 資料中心建設放慢,11/5 標普 500 跌 4.36%,為 2025 年 4 月以來最大單日跌幅;費城半導體指數跌 12.25%,為 2020 年 3 月以來最大單日跌幅。
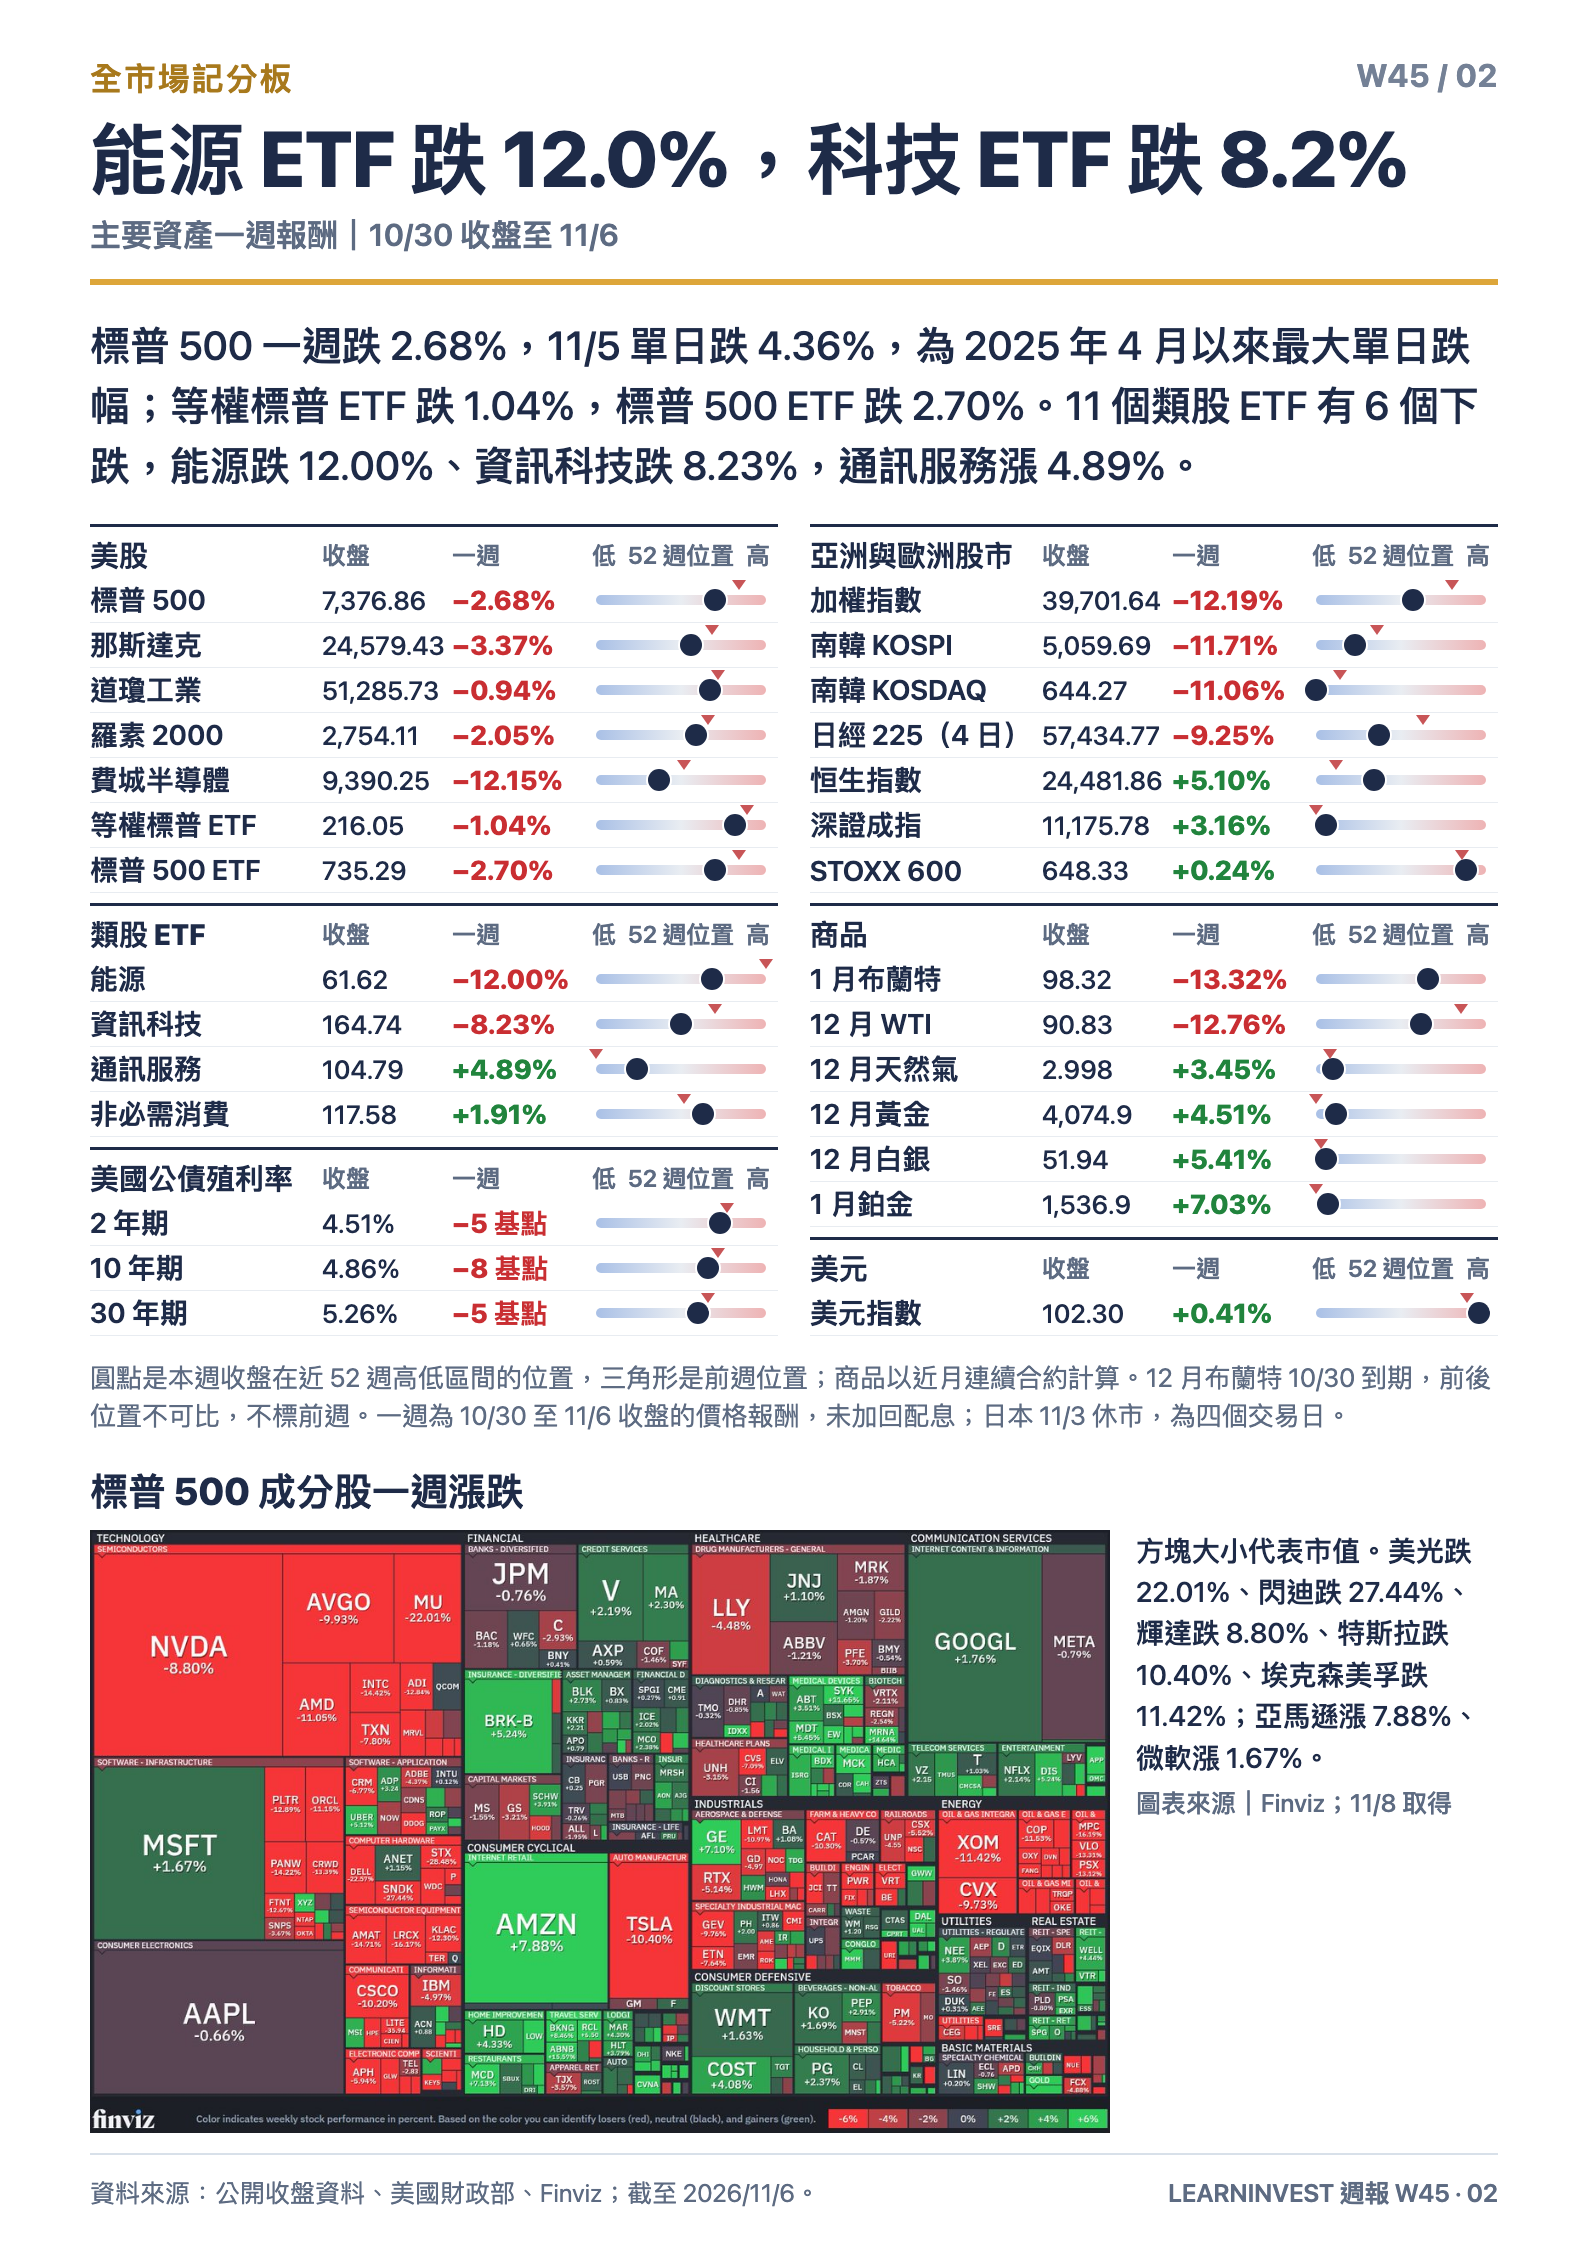
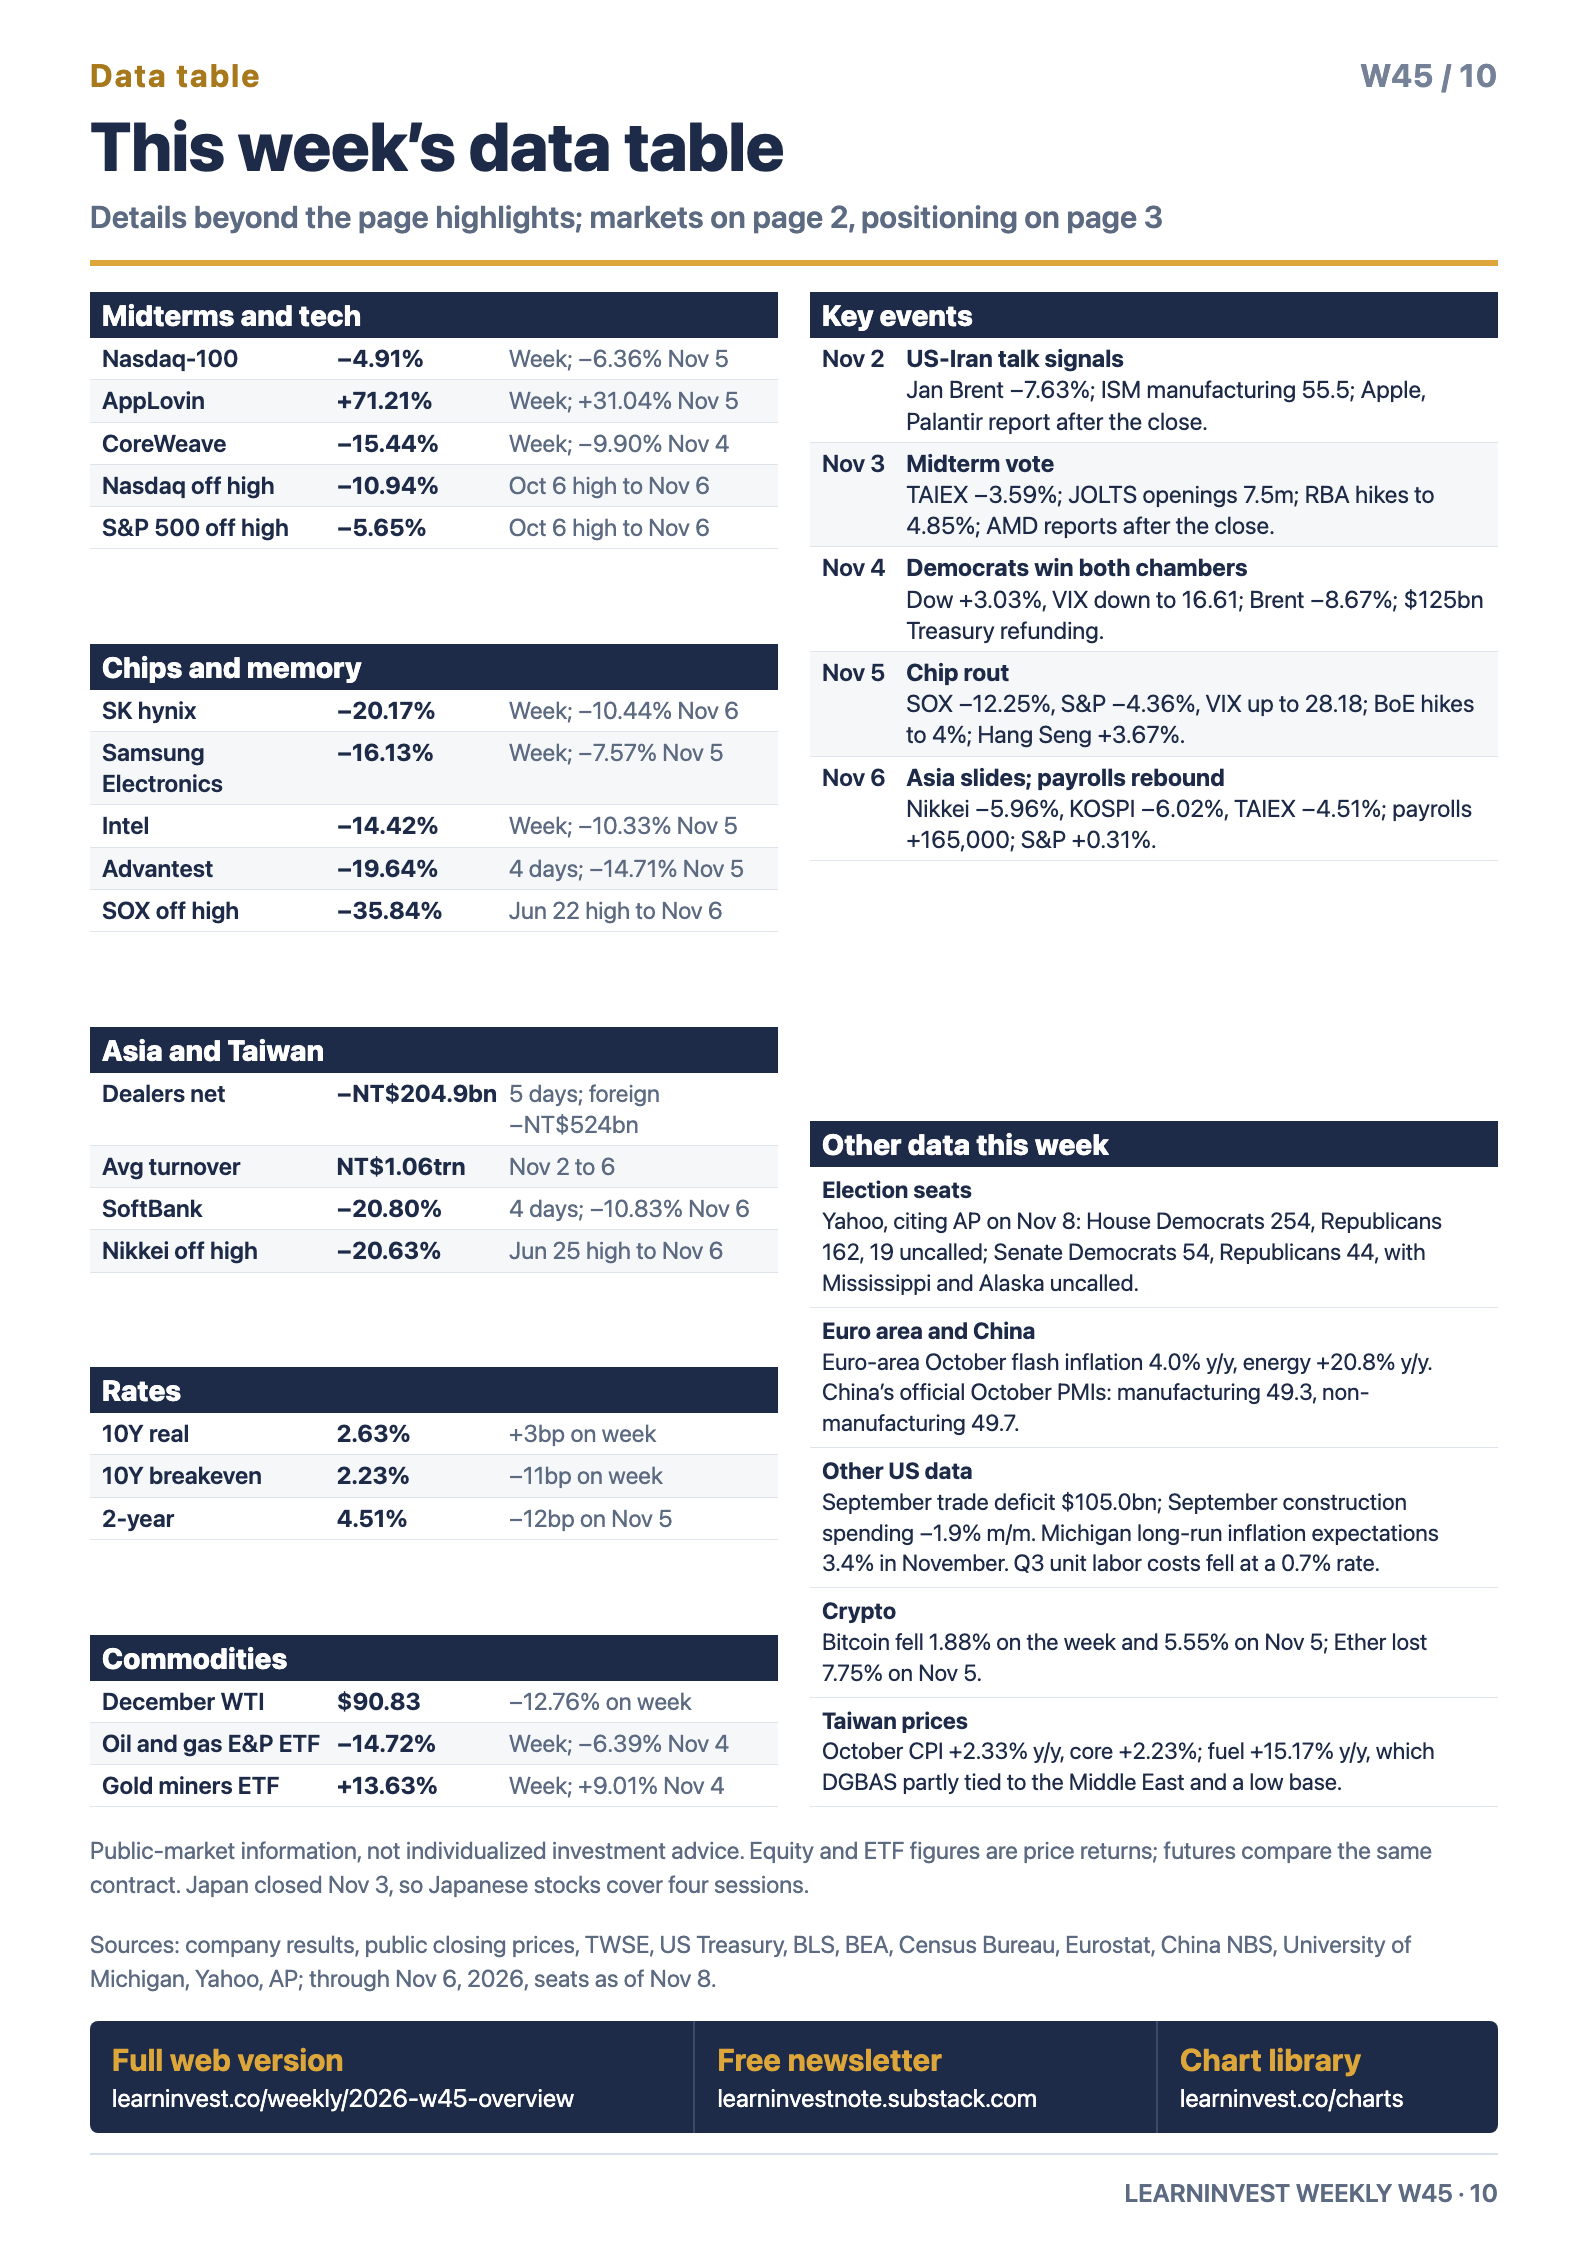
一週下來標普 500 跌 2.68%、那斯達克跌 3.37%、費半跌 12.15%;等權標普 ETF 跌 1.04%,標普 500 ETF 跌 2.70%。11 個類股 ETF 有 6 個下跌,能源 ETF 跌 12.00%、資訊科技 ETF 跌 8.23%,通訊服務 ETF 漲 4.89%。
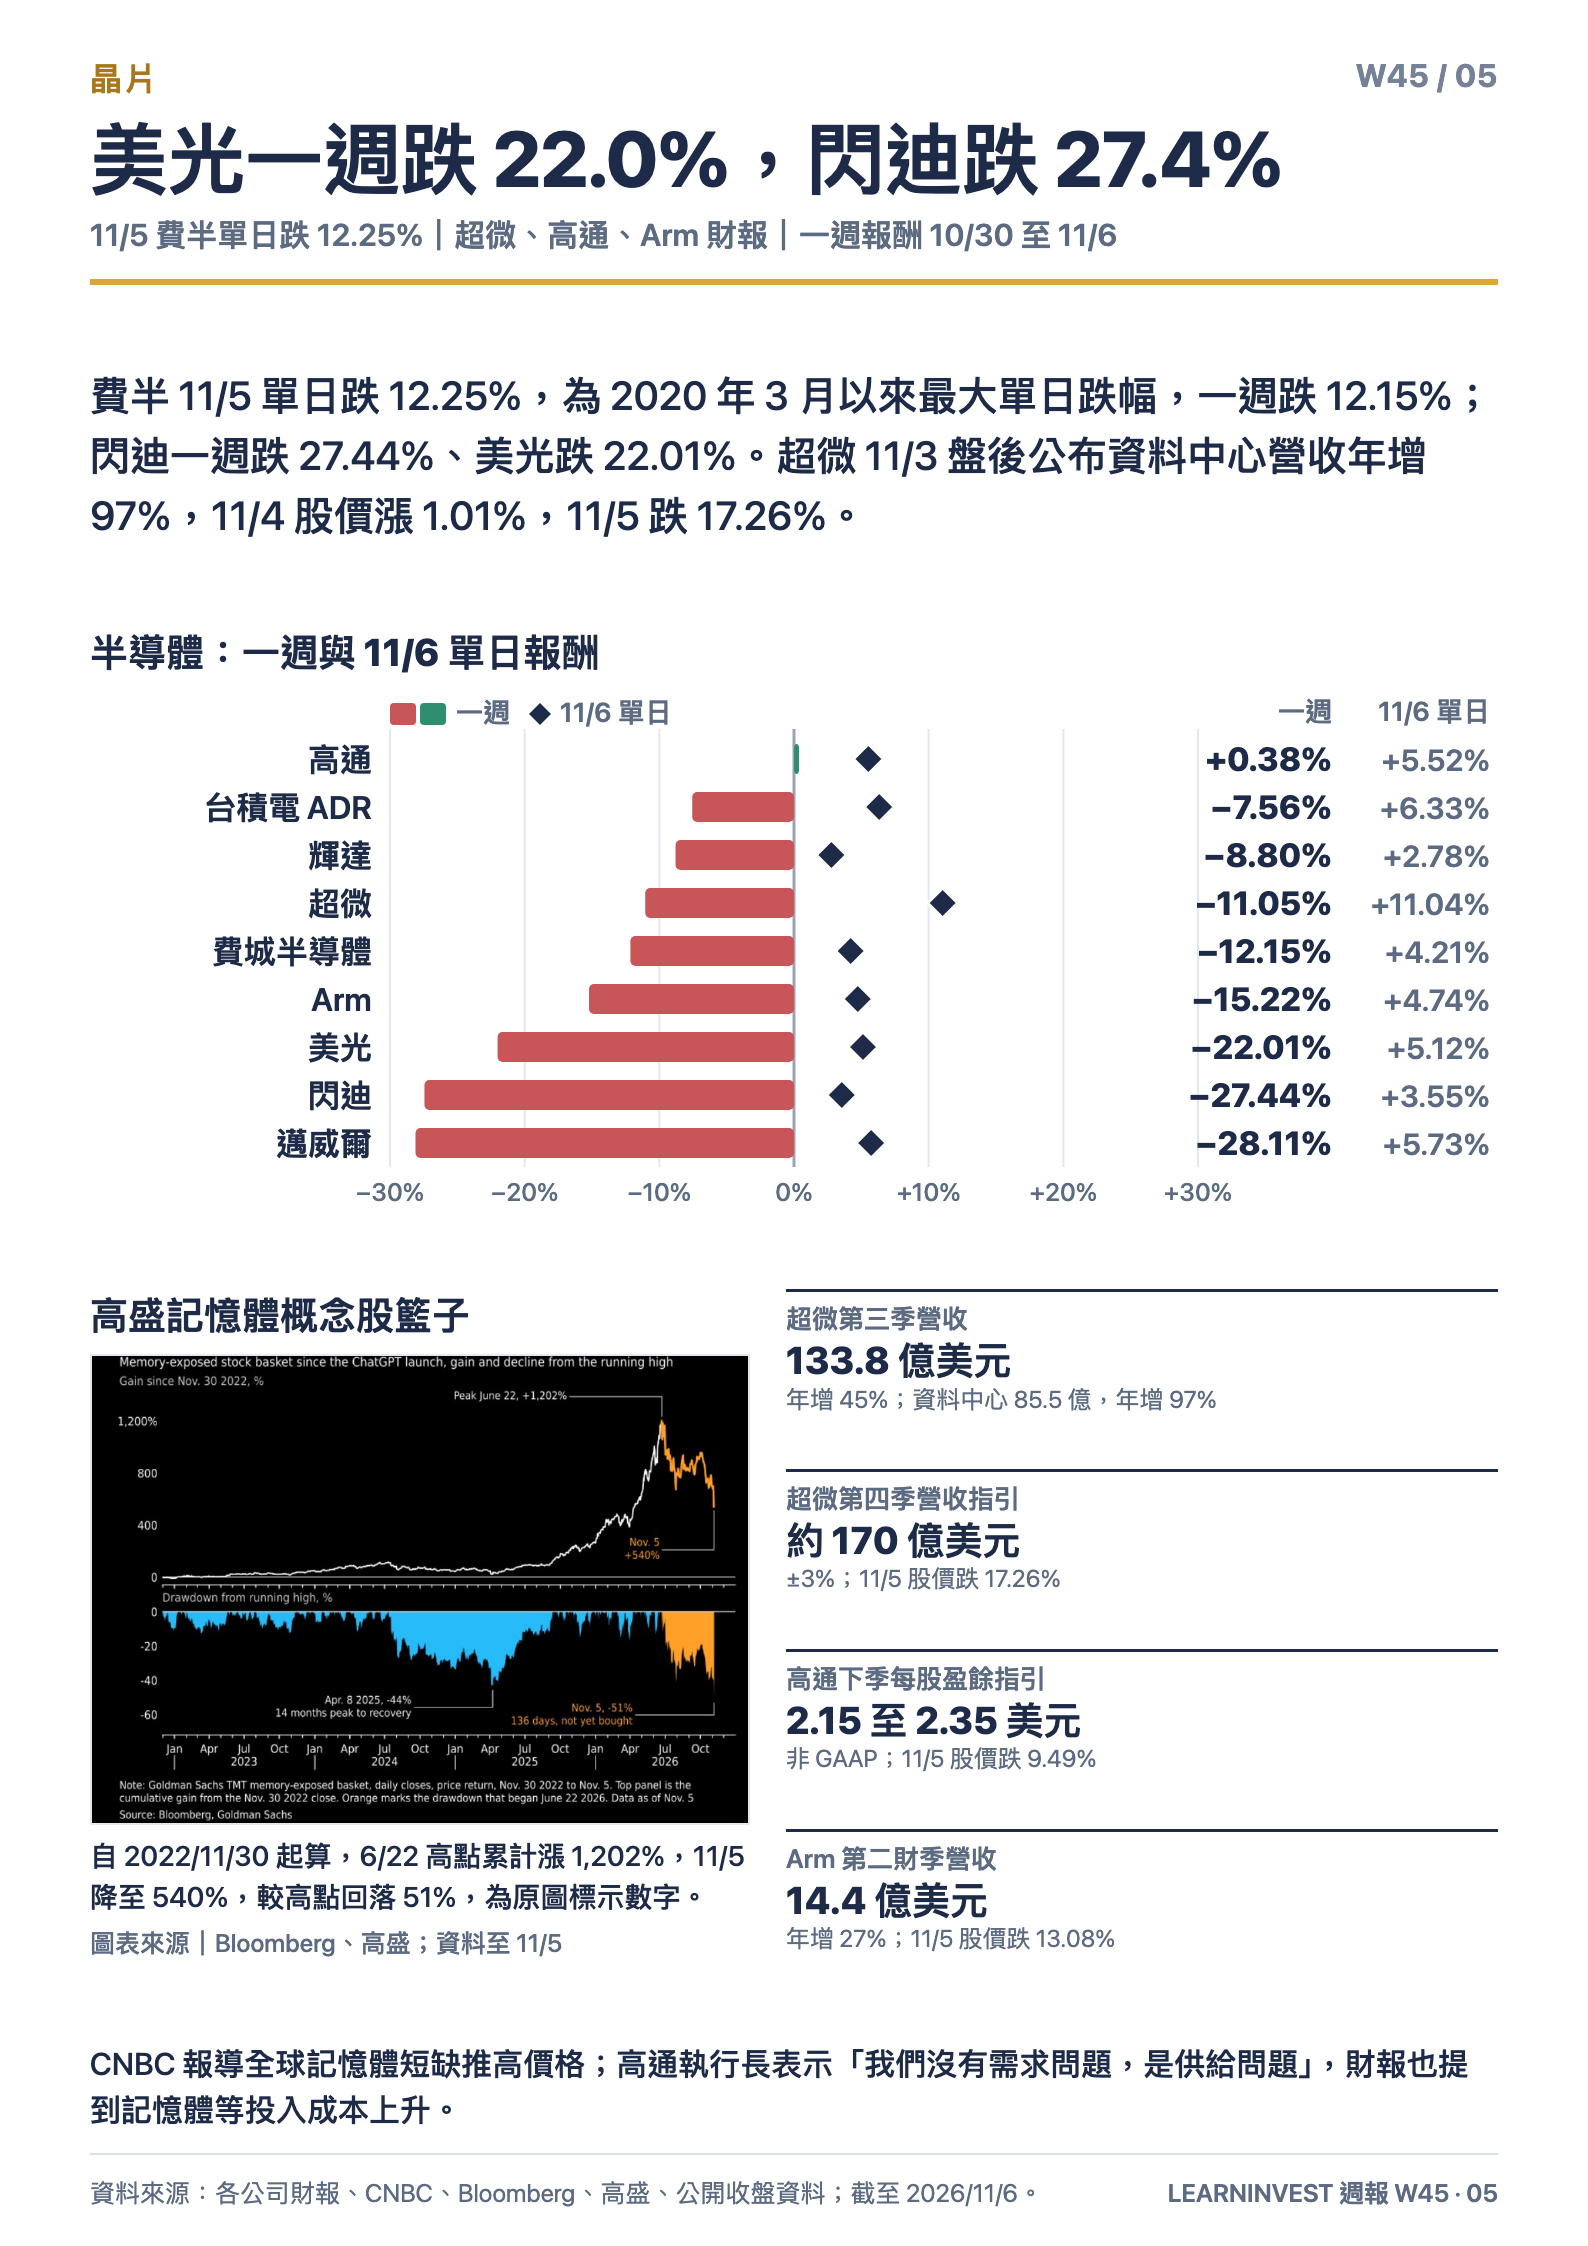
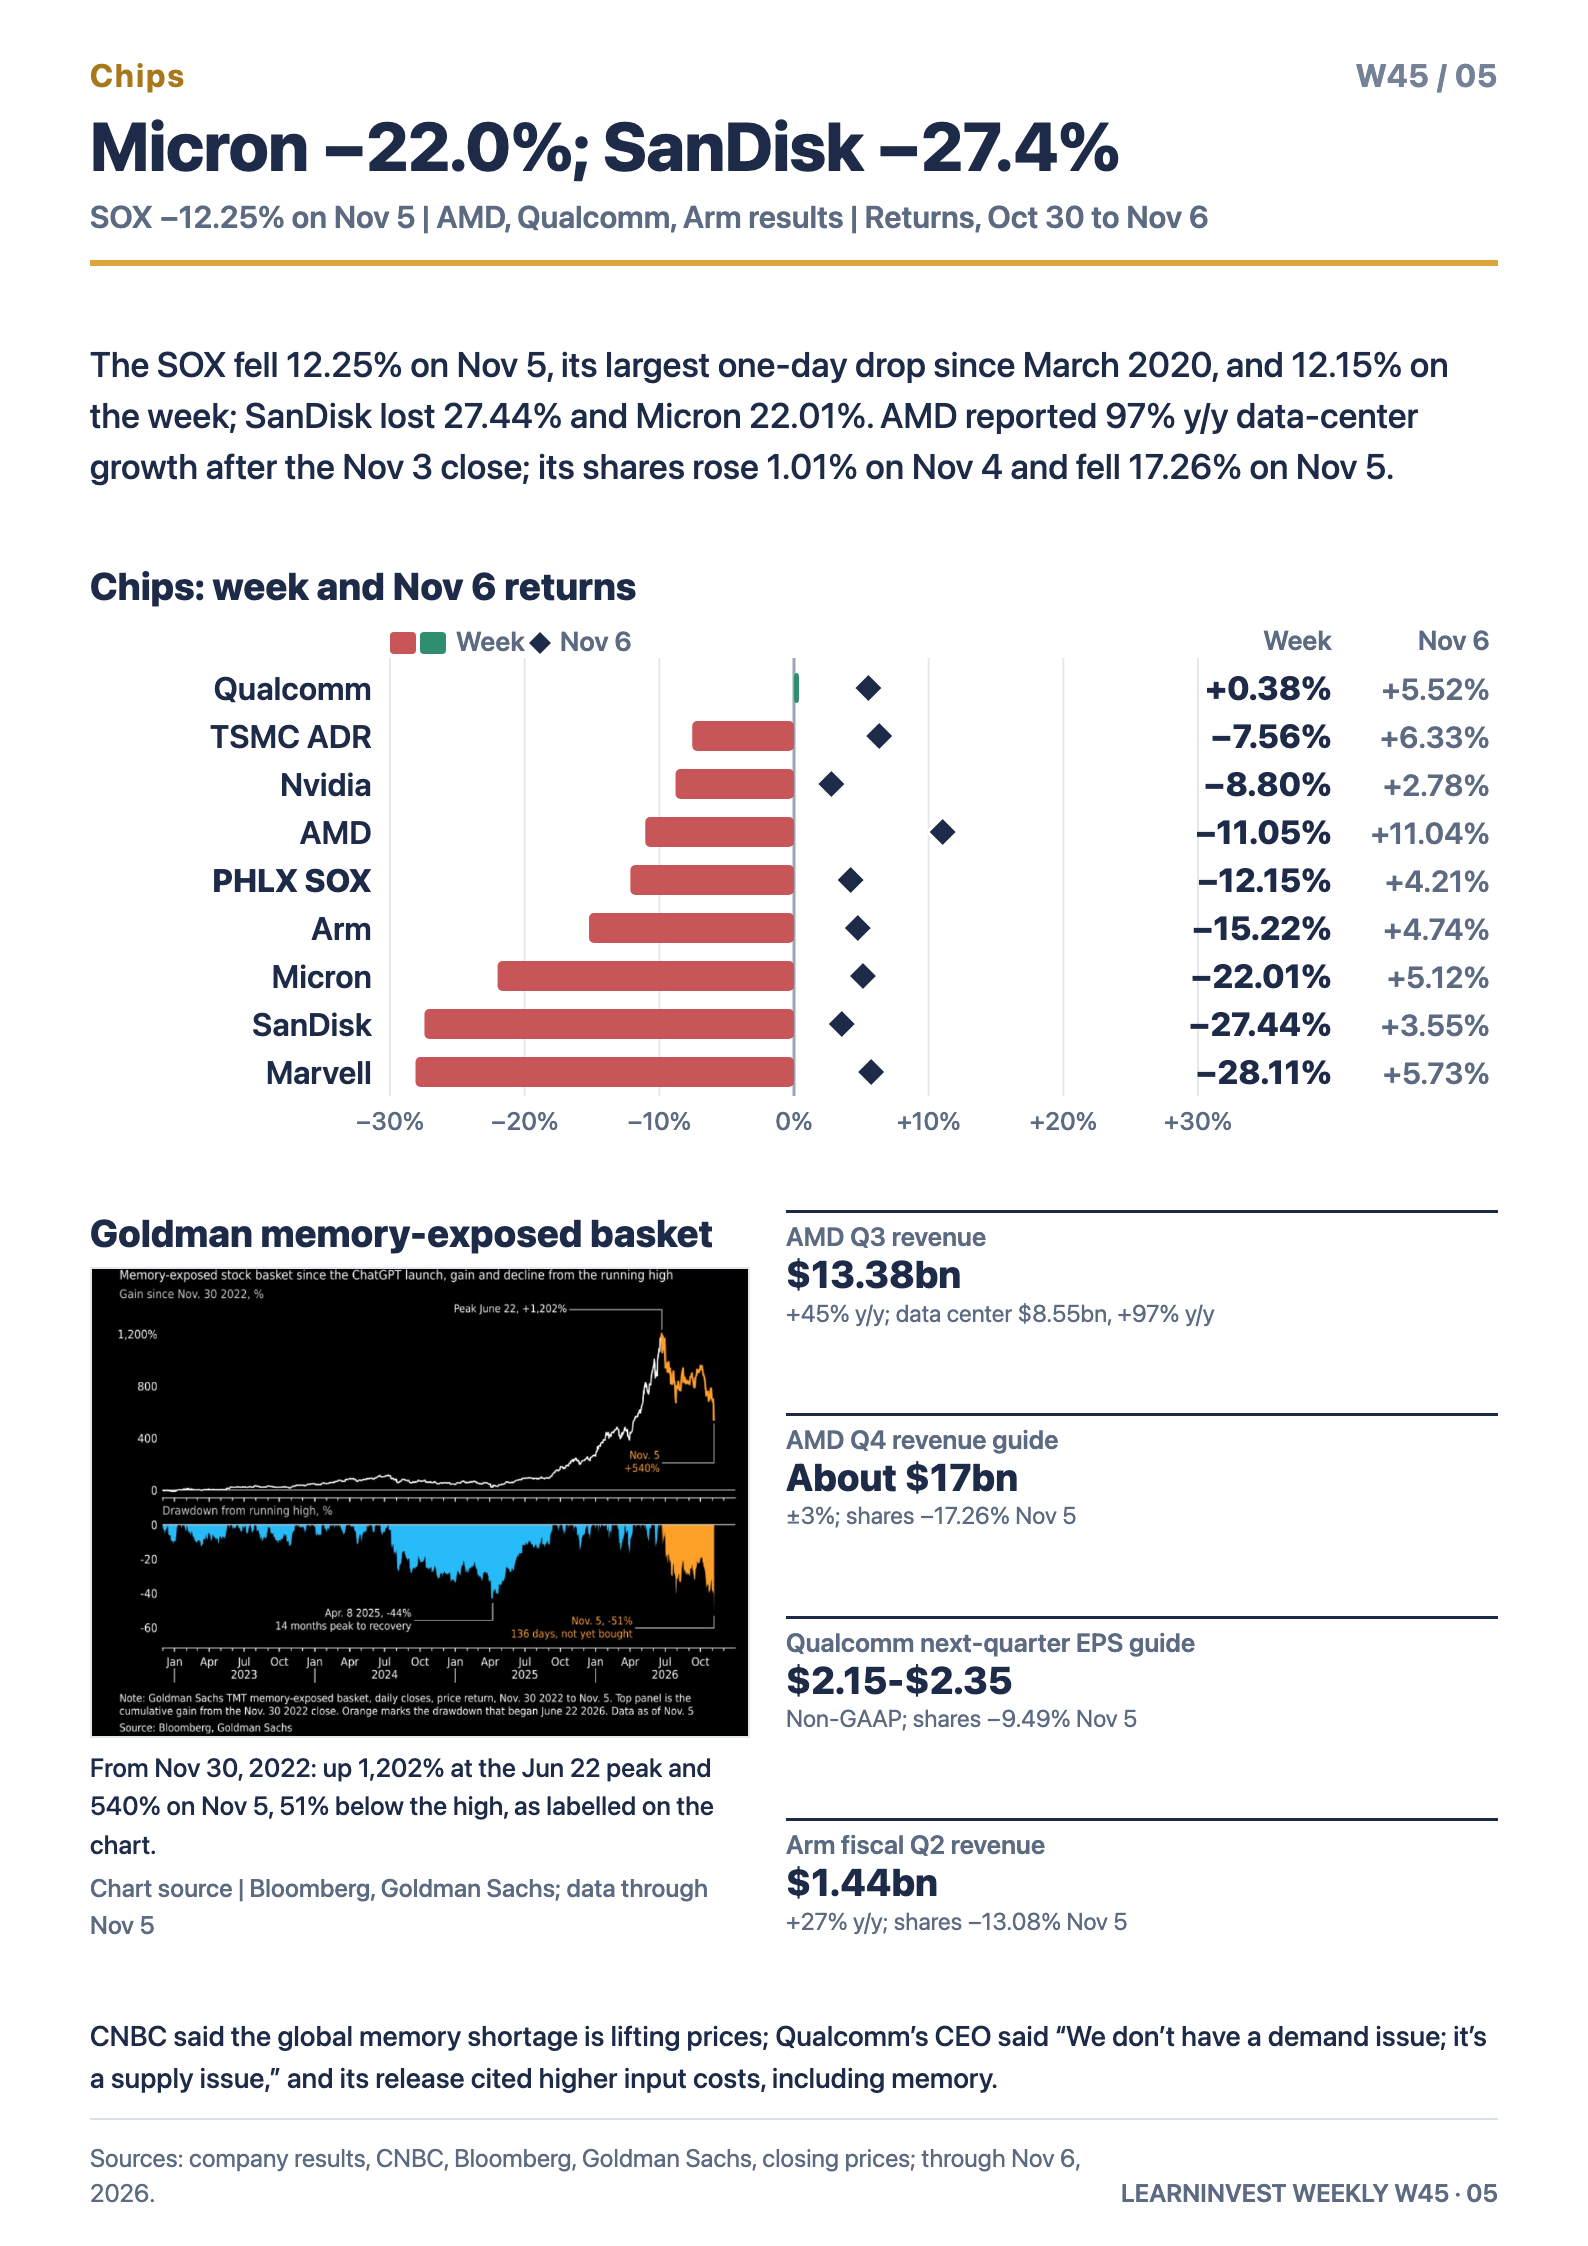
晶片股中記憶體股跌幅最大,閃迪一週跌 27.44%、美光跌 22.01%。超微 11/3 盤後公布資料中心營收年增 97%,11/4 股價漲 1.01%,11/5 跌 17.26%。高通財報提到記憶體等投入成本上升,11/5 跌 9.49%。
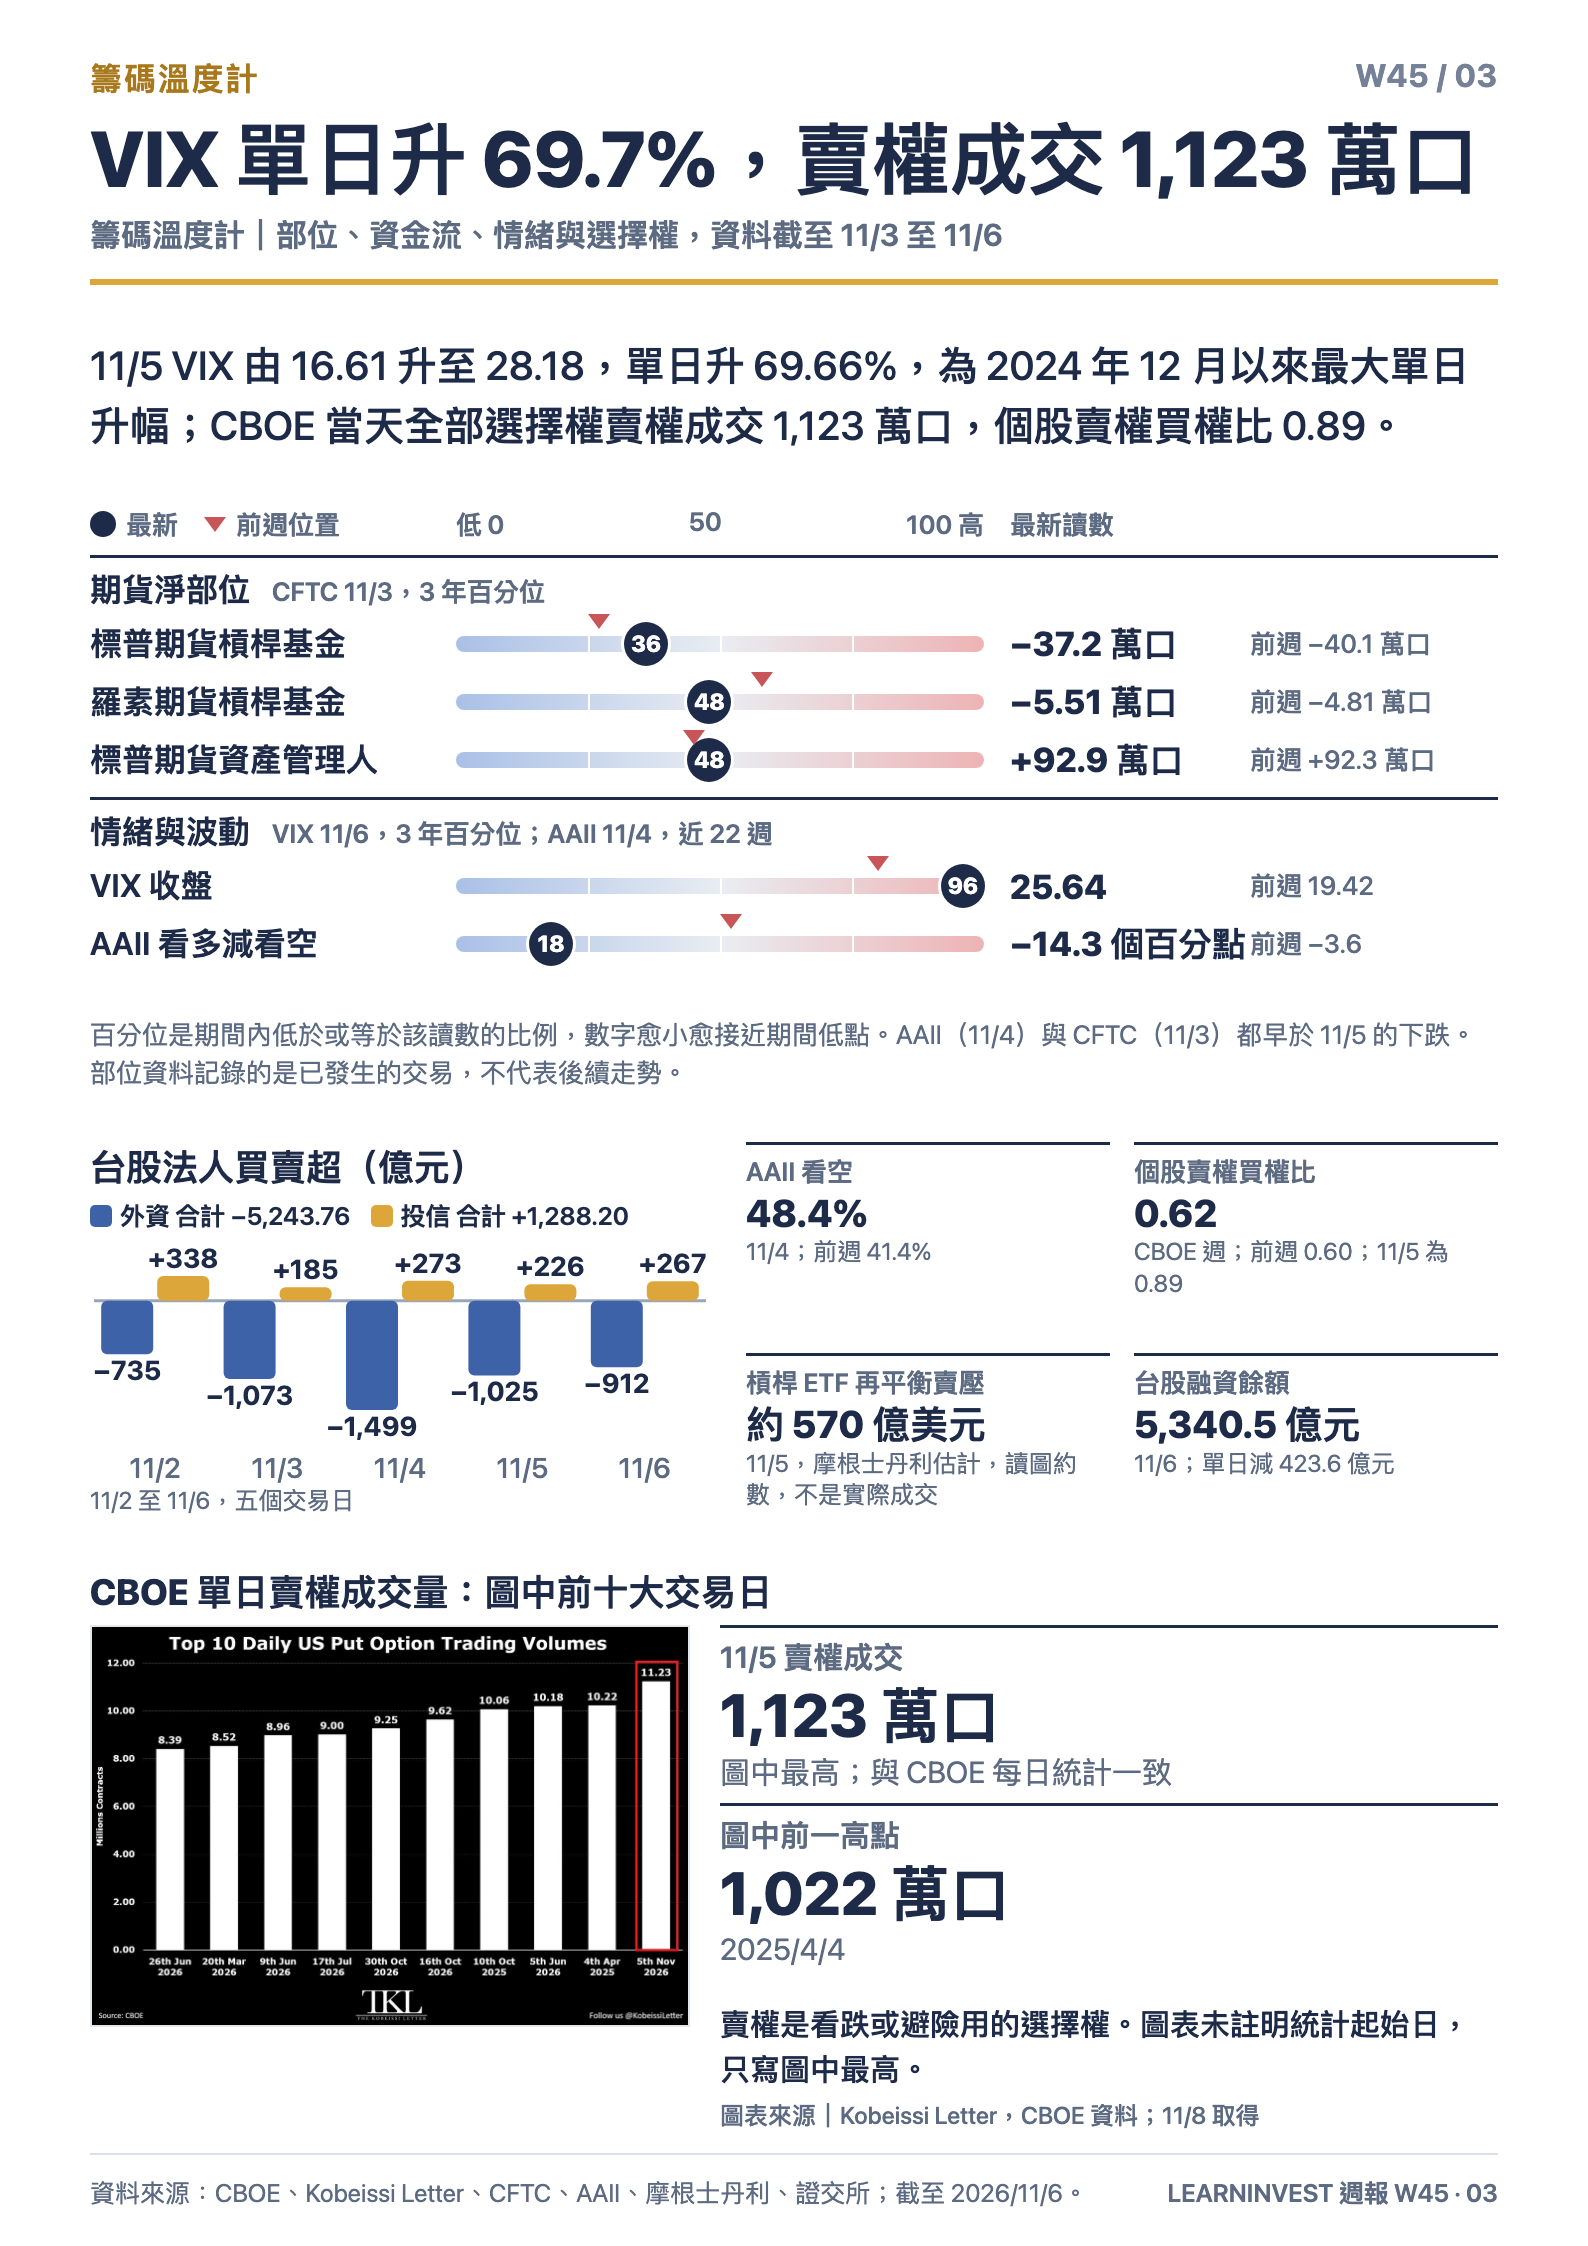
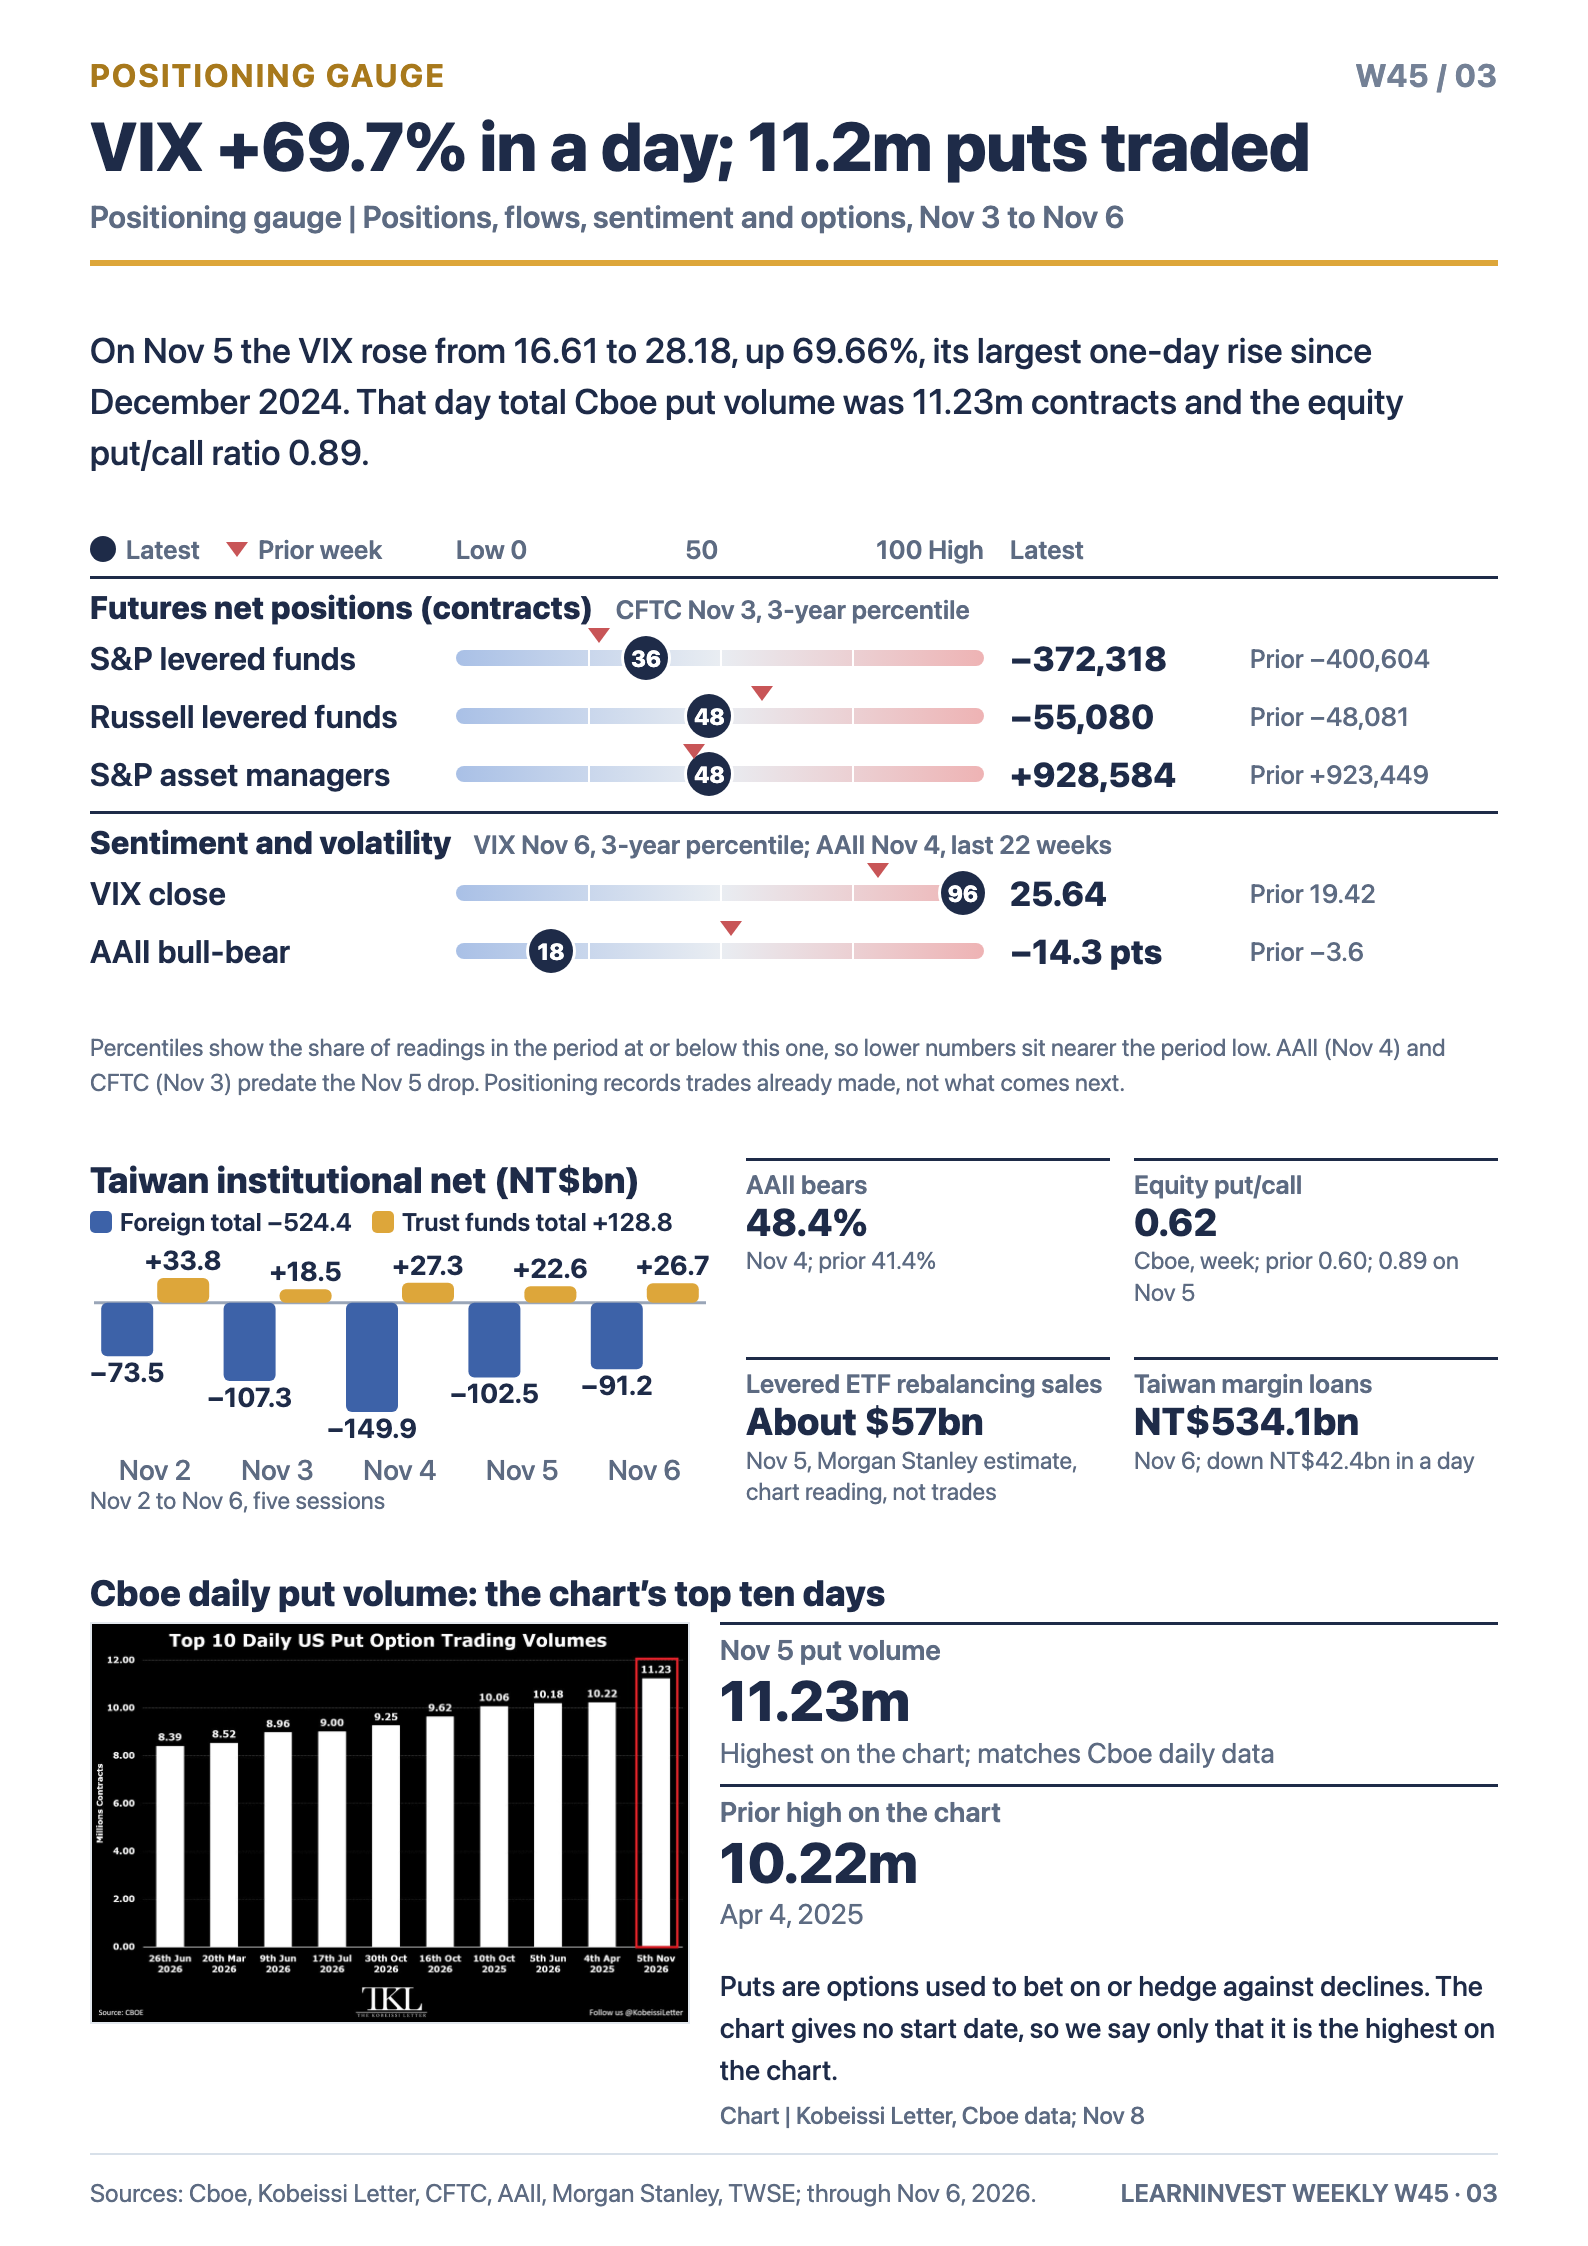
籌碼面,11/5 VIX 由 16.61 升至 28.18,單日升 69.66%;CBOE 當天全部選擇權賣權成交 1,123 萬口,個股賣權買權比 0.89。AAII 11/4 公布的週調查看空 48.4%,高於看多 34.1%,調查早於 11/5 的下跌。
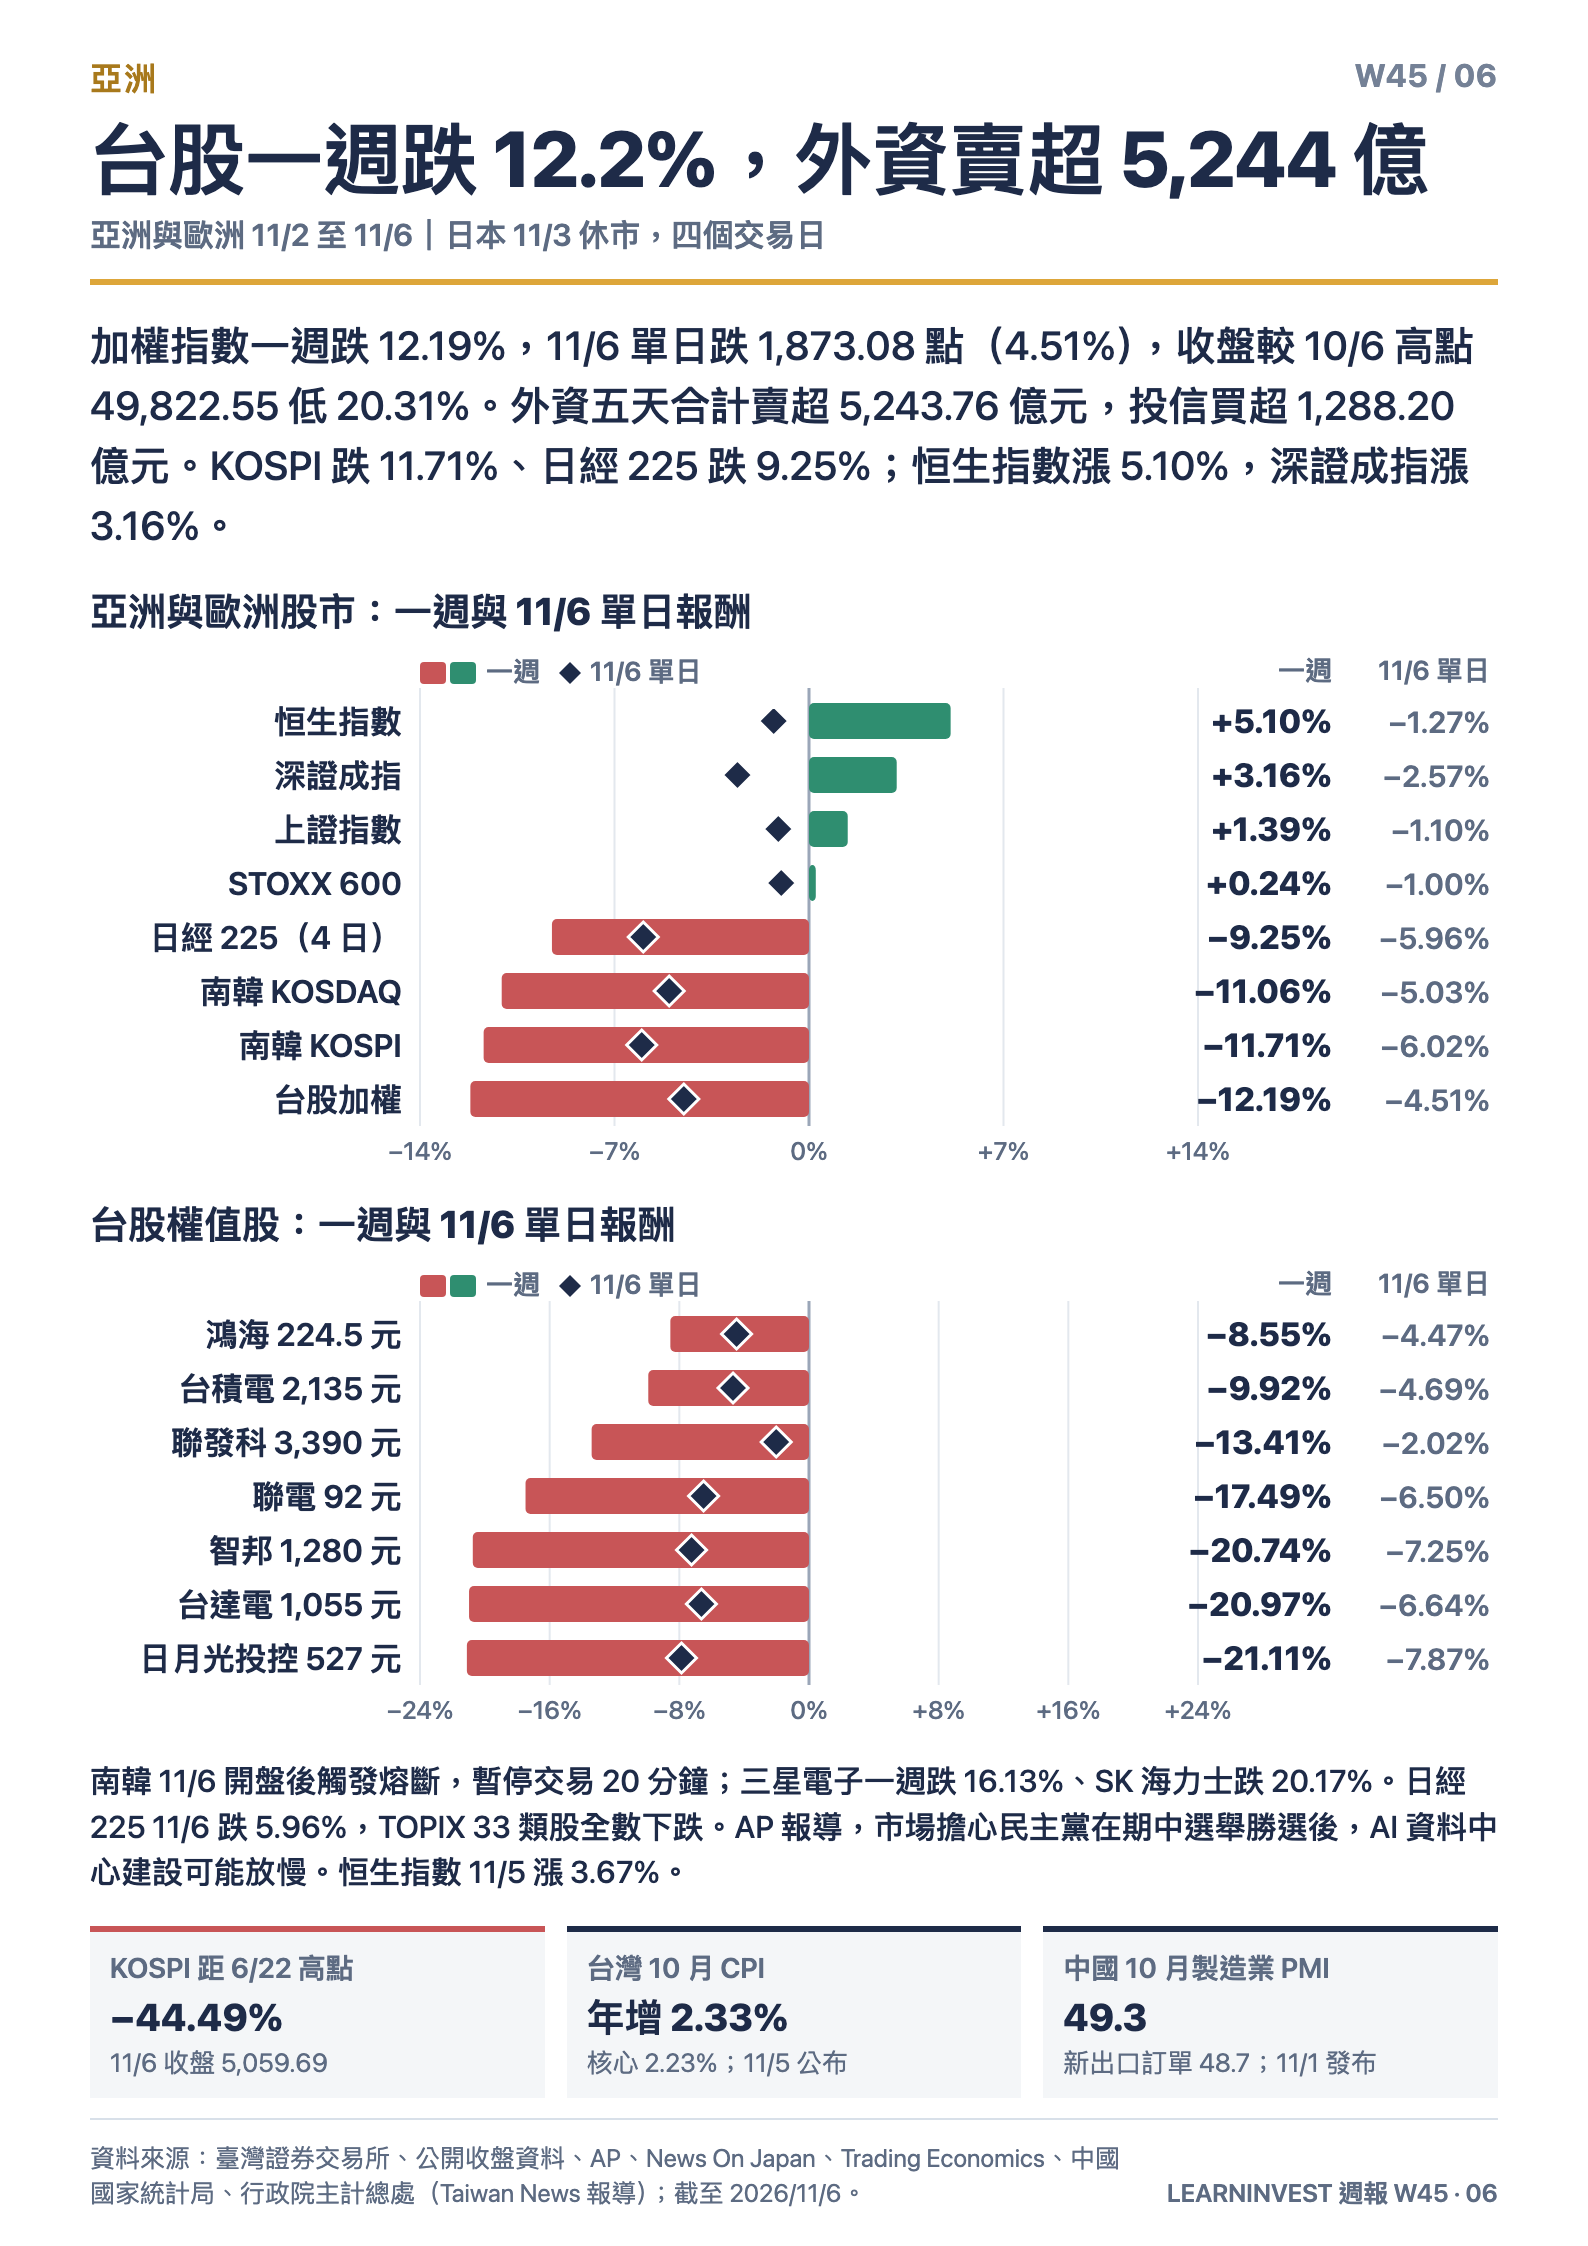
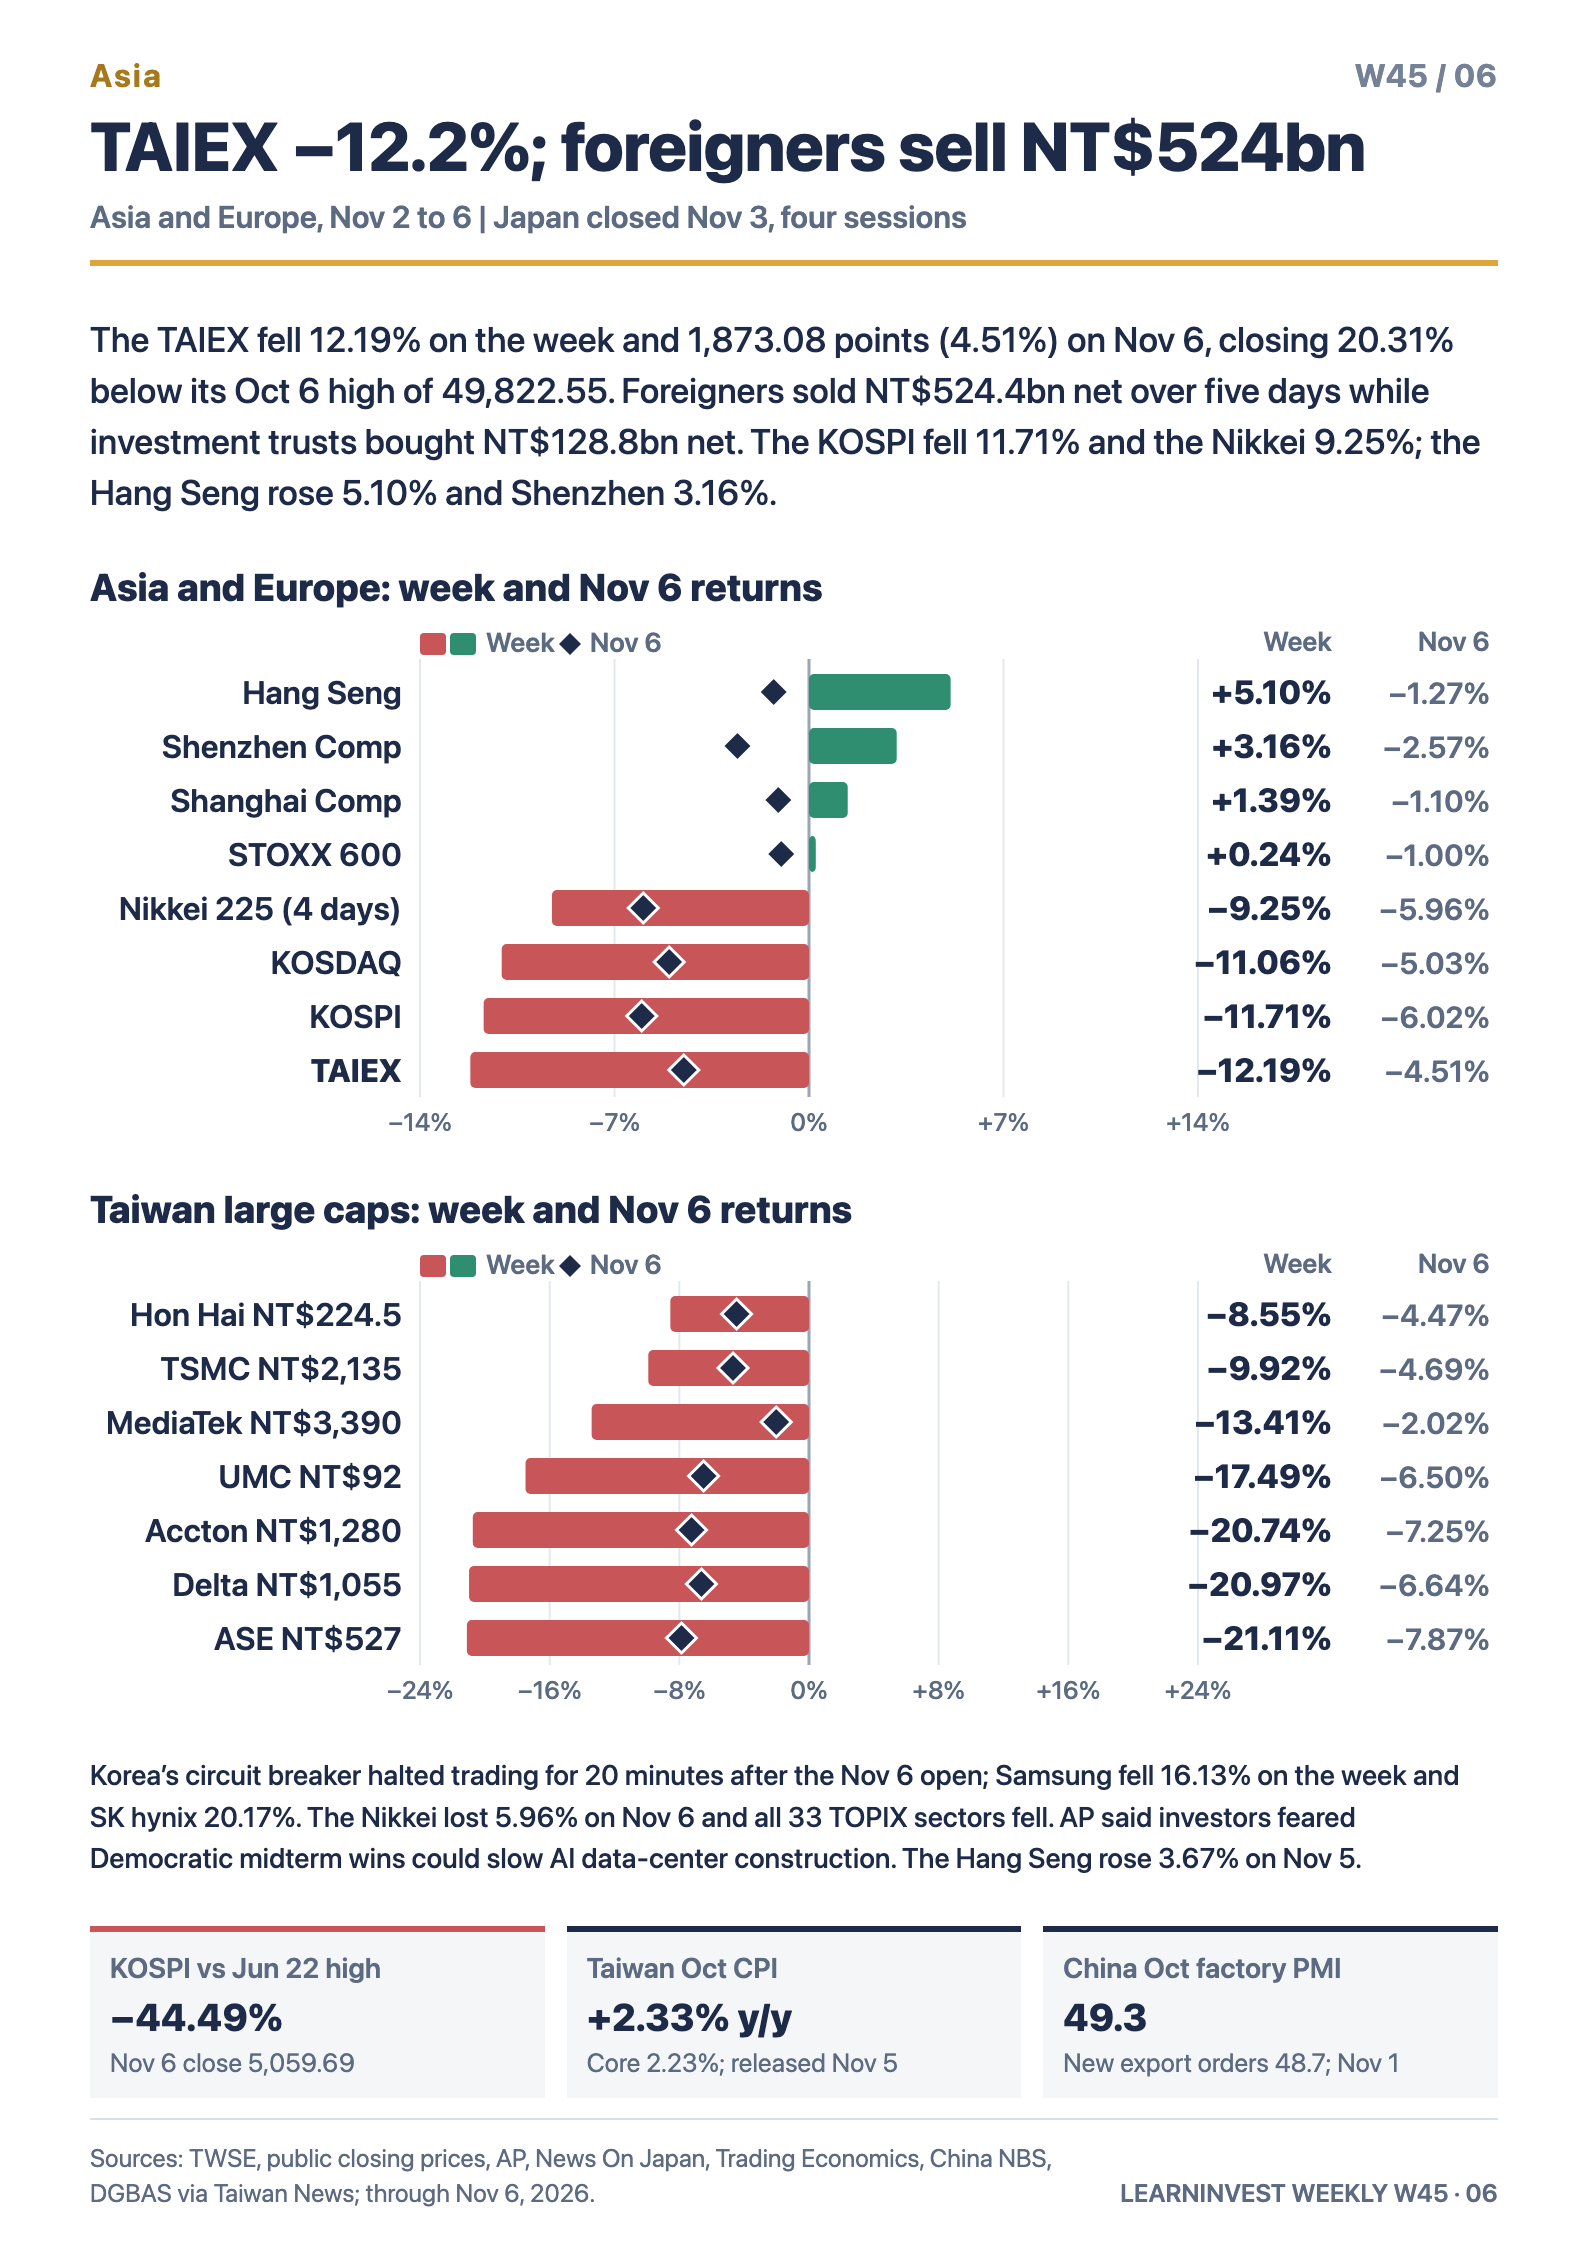
亞洲科技市場重挫。台股一週跌 12.19%,11/6 單日跌 1,873.08 點,收盤較 10/6 收盤高點低 20.31%;外資五天賣超 5,243.76 億元,投信買超 1,288.20 億元。KOSPI 跌 11.71%、日經 225 四個交易日跌 9.25%;恒生指數漲 5.10%。
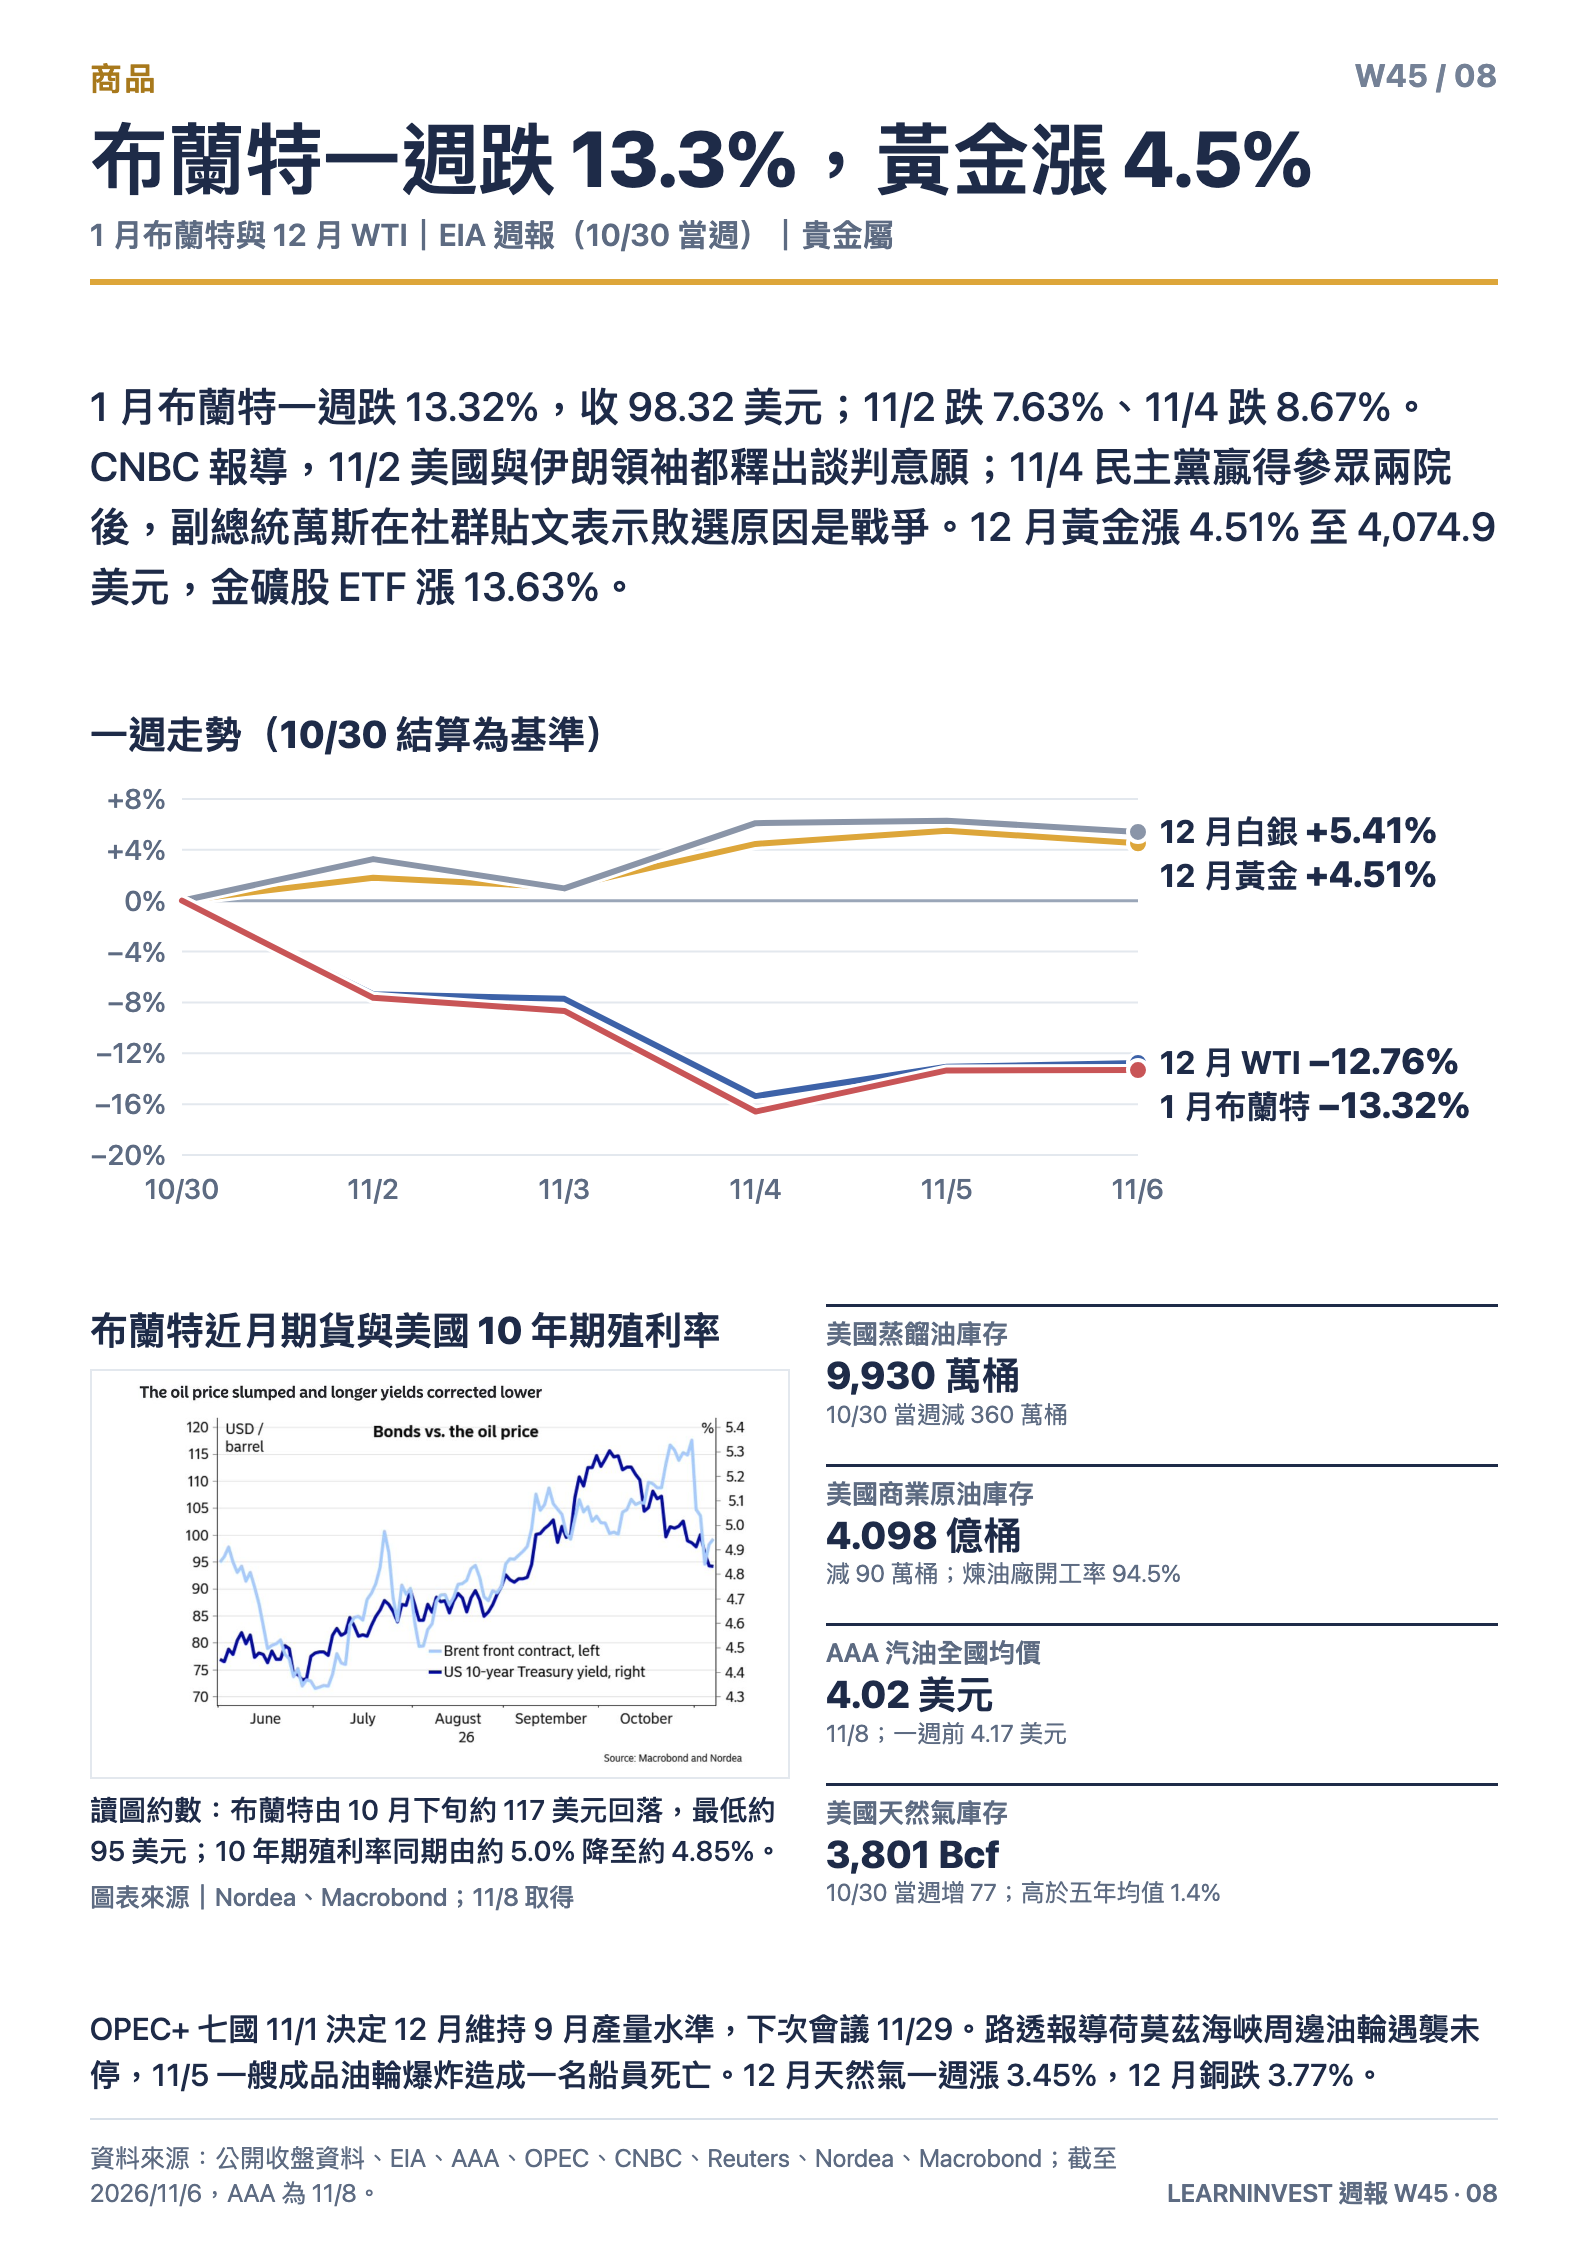
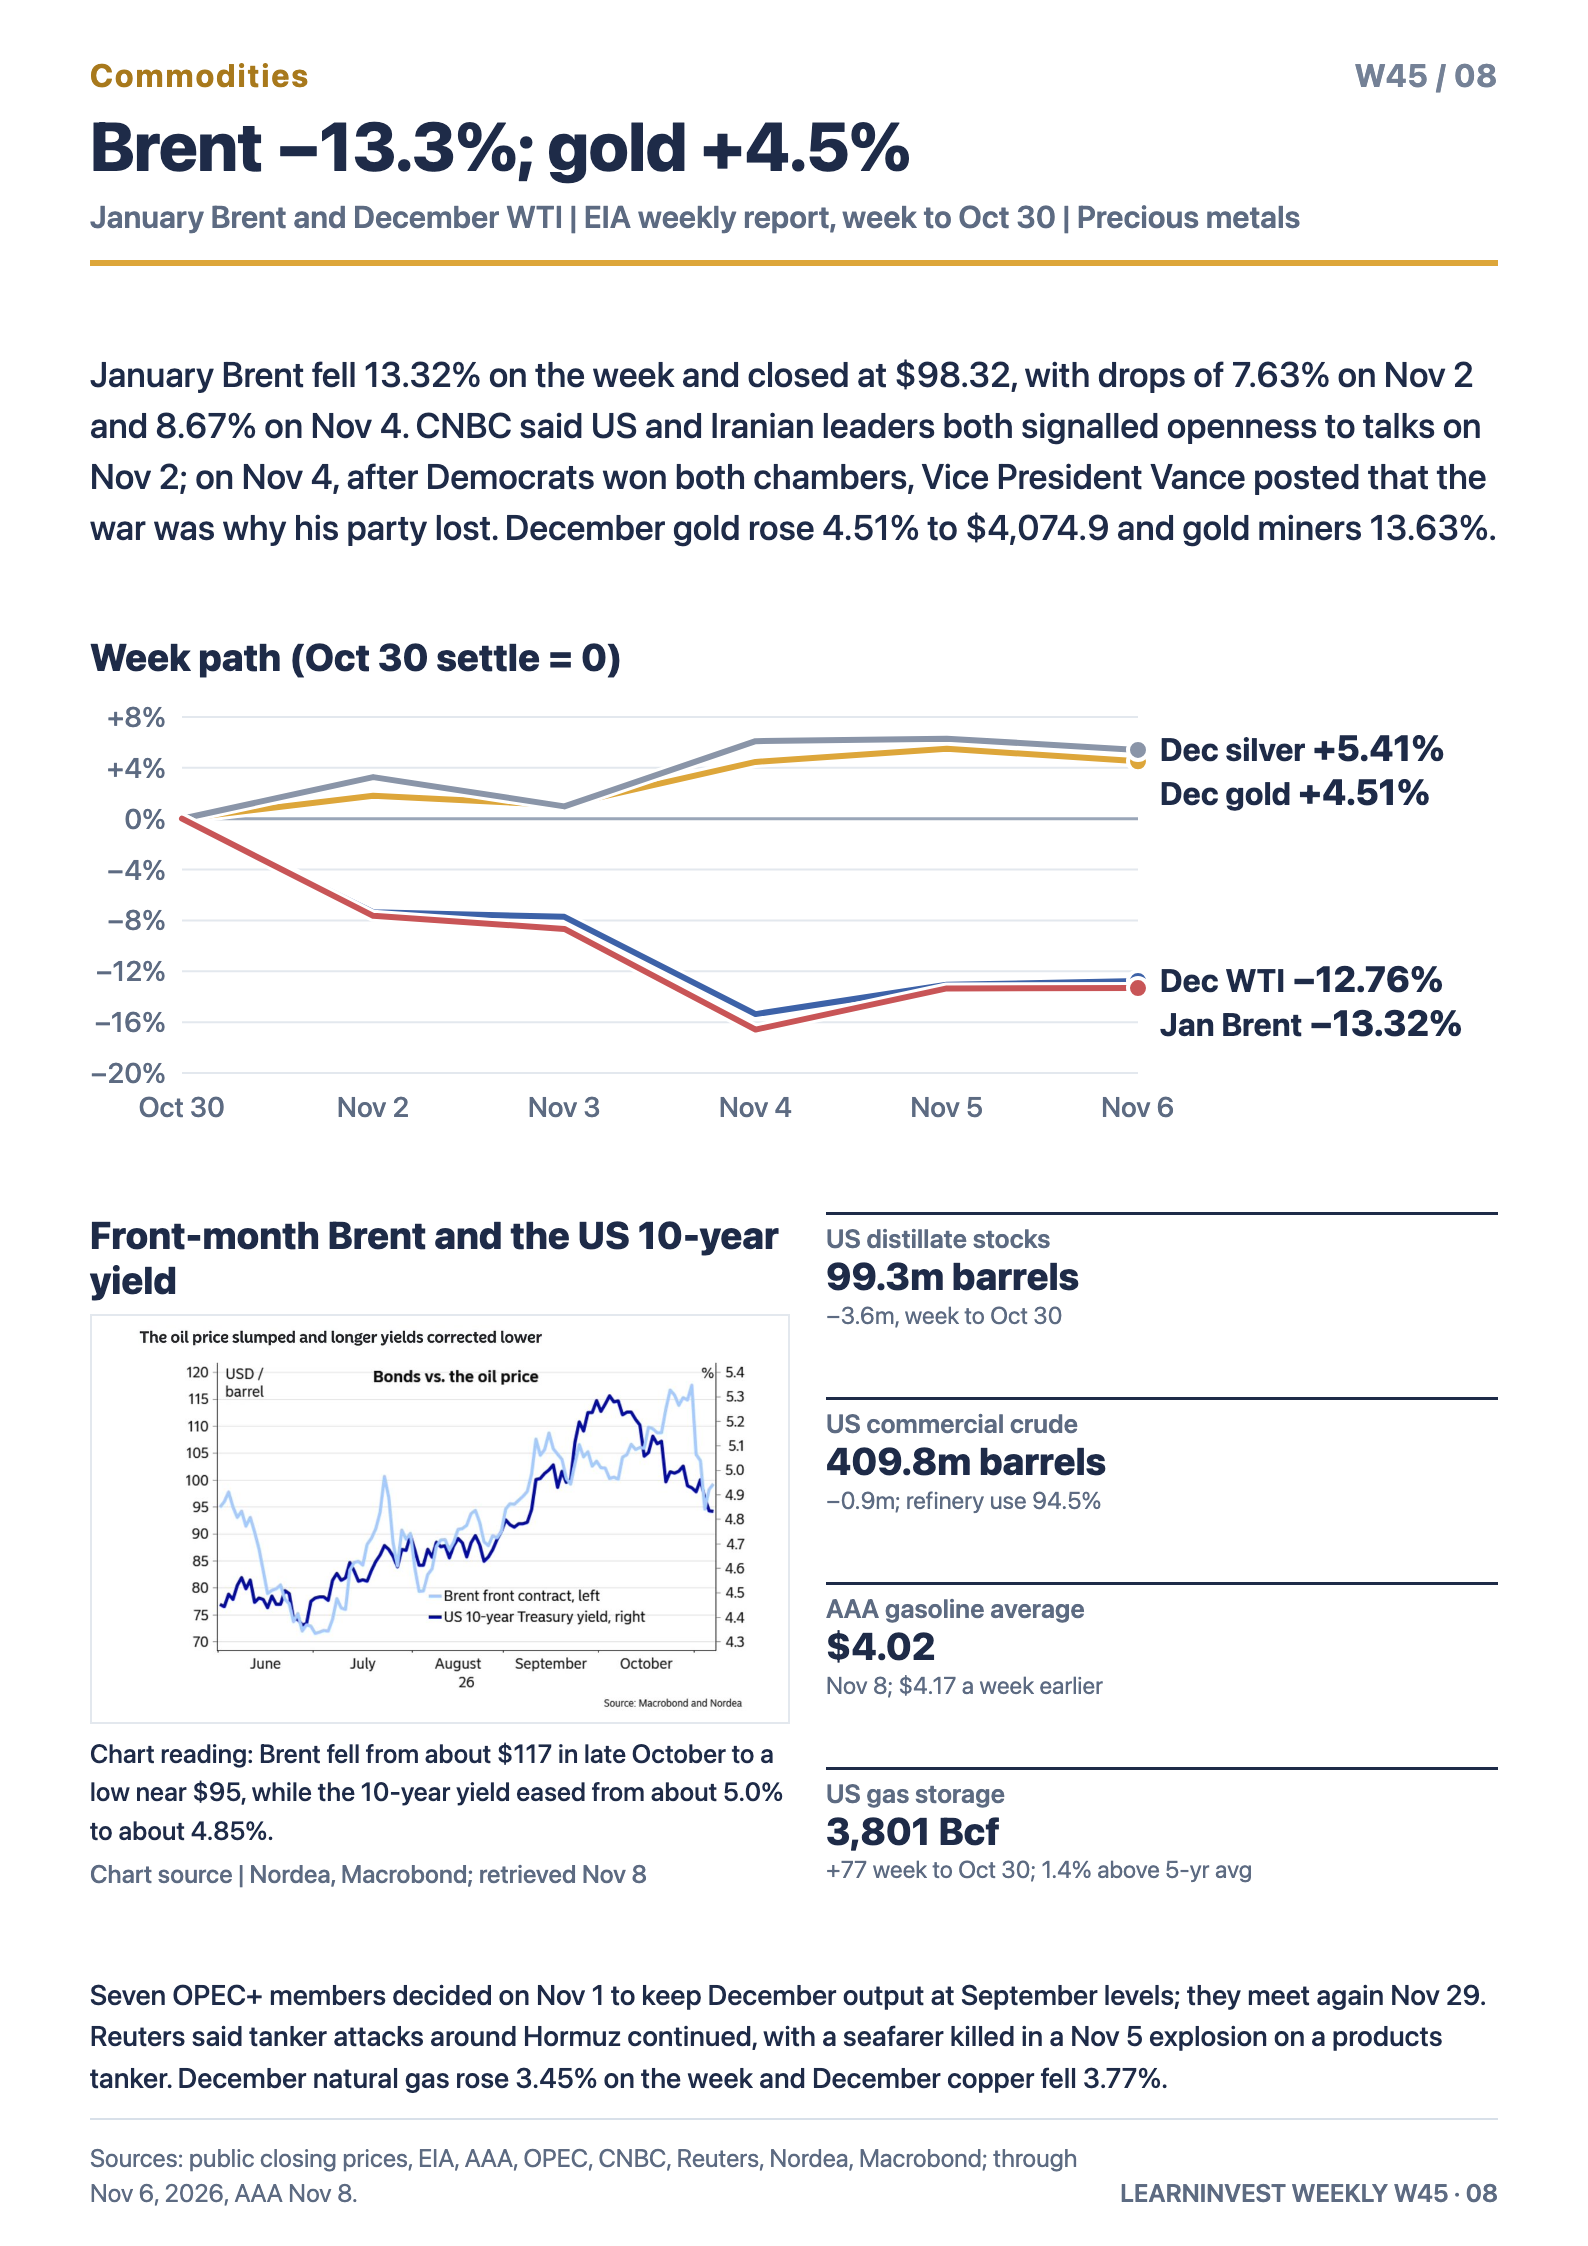
油價大跌、貴金屬走高。1 月布蘭特期貨一週跌 13.32% 至 98.32 美元。CNBC 報導,11/2 美伊領袖都釋出談判意願;11/4 副總統萬斯在社群貼文表示敗選原因是戰爭。12 月黃金期貨漲 4.51% 至 4,074.9 美元,金礦股 ETF 漲 13.63%。
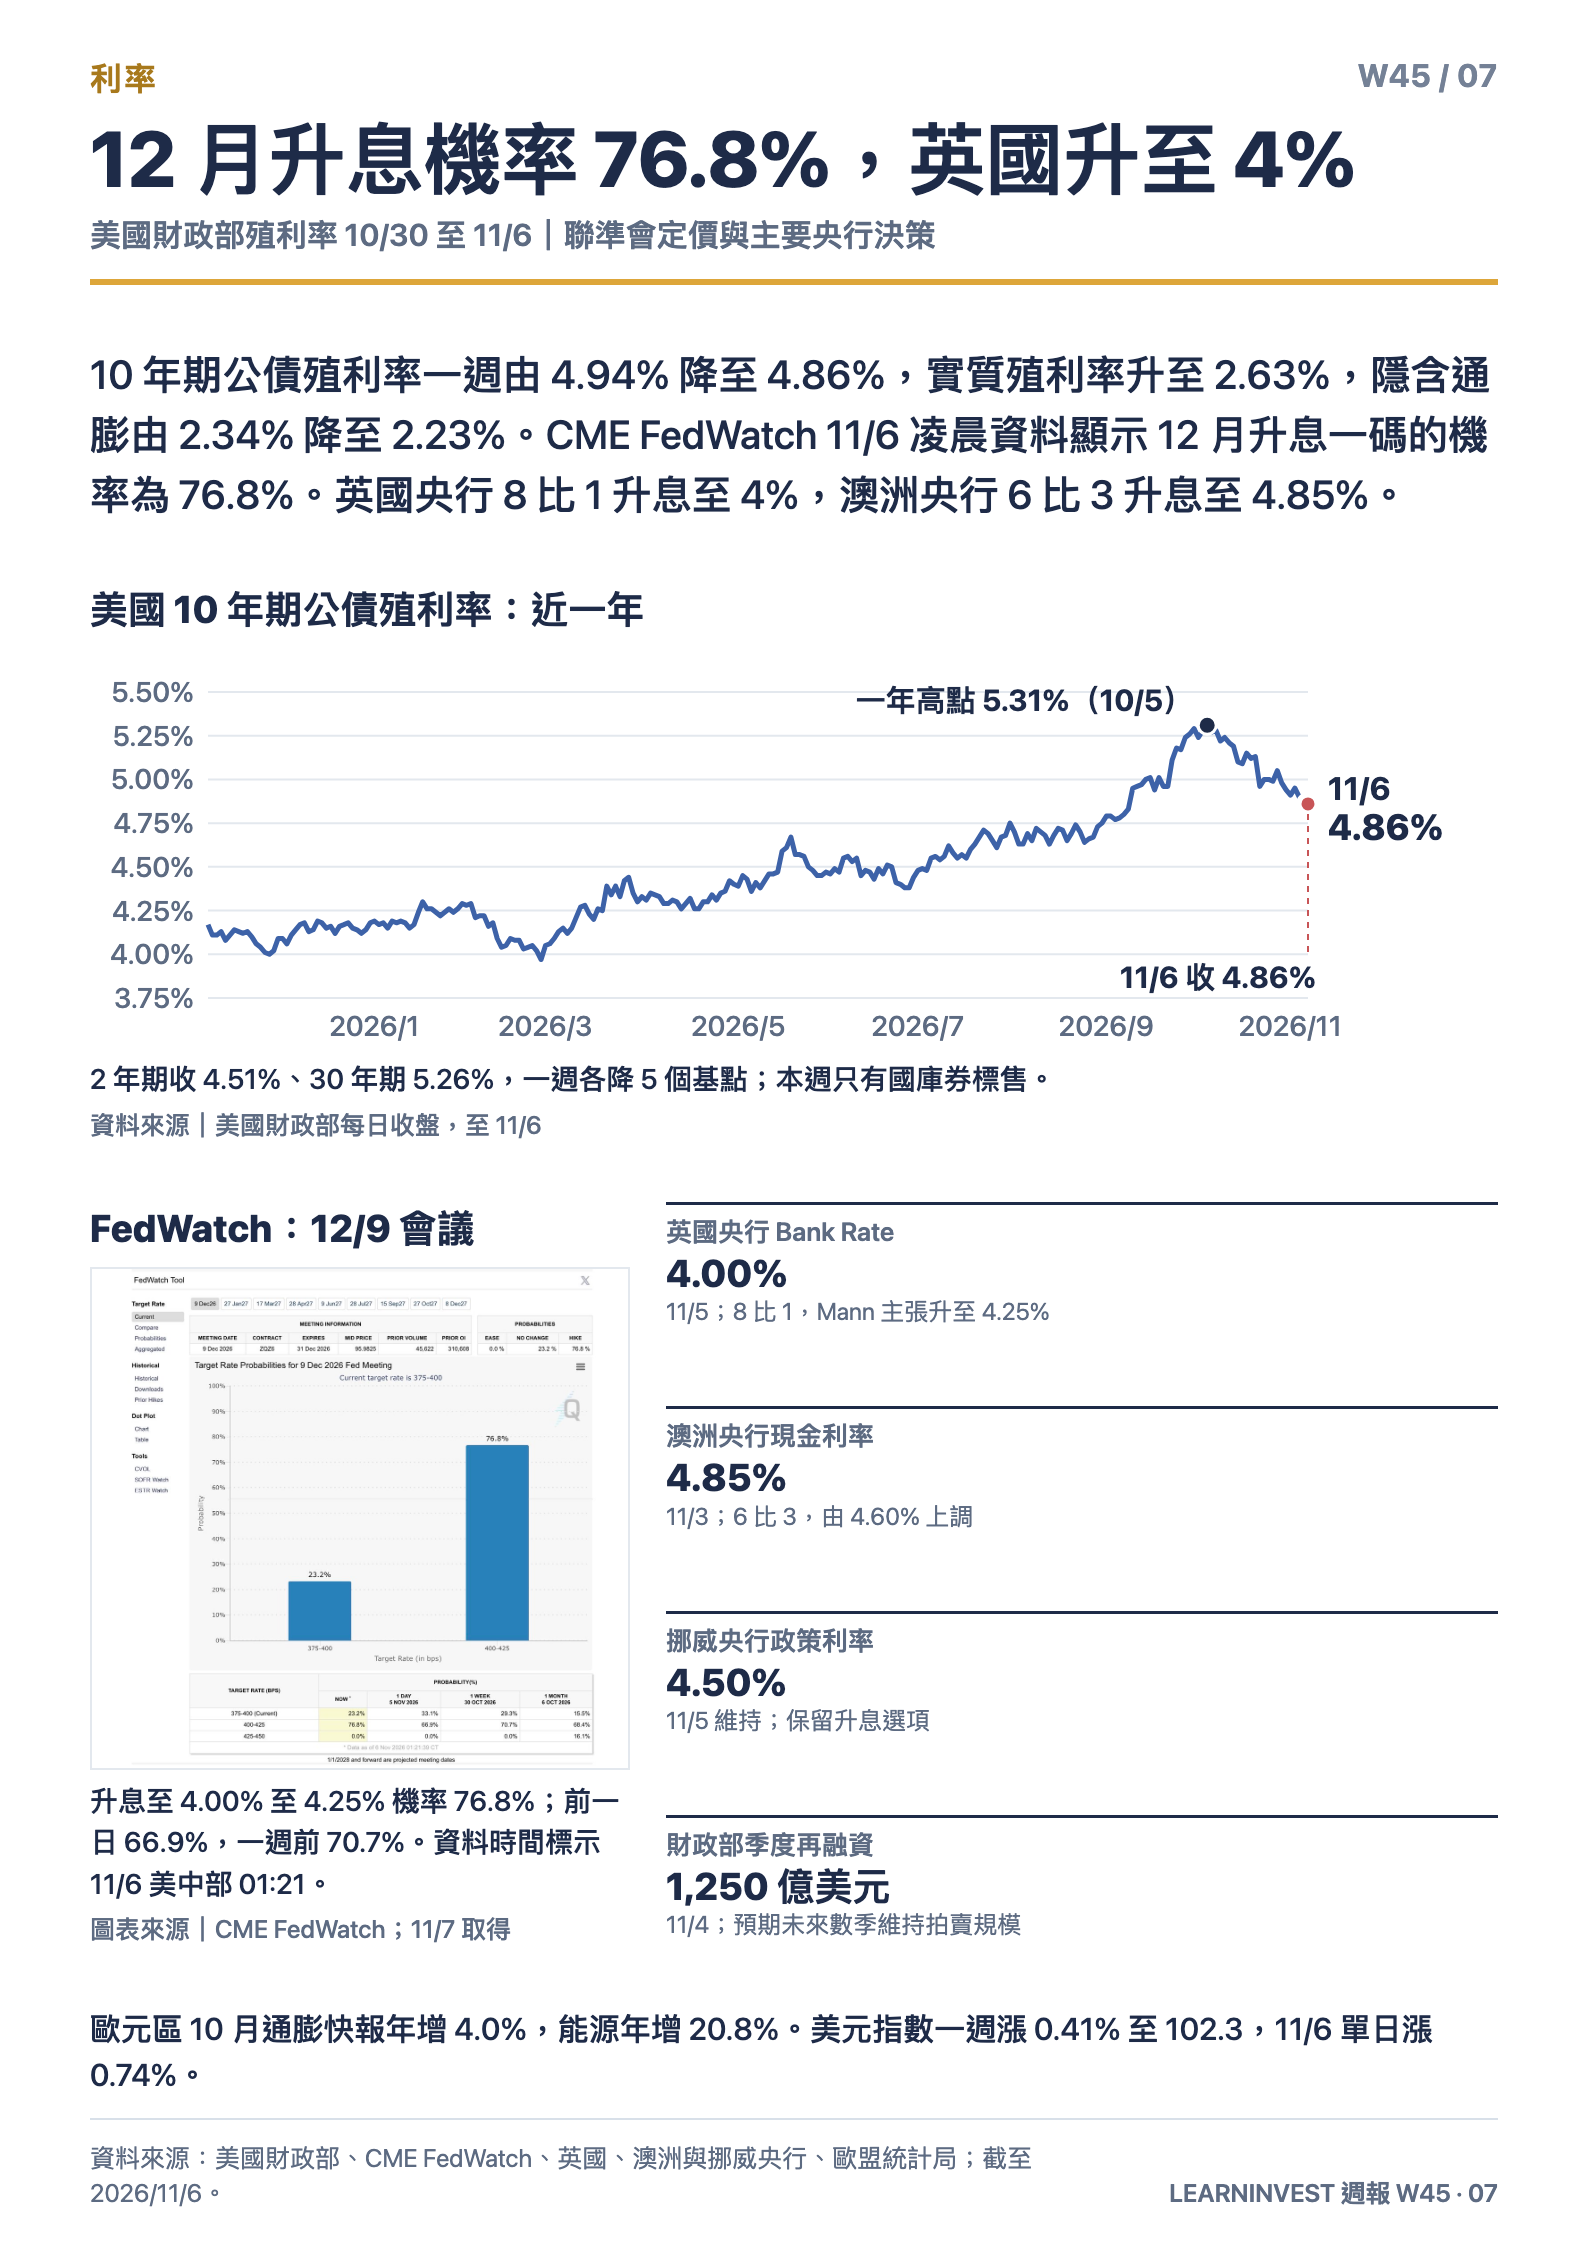
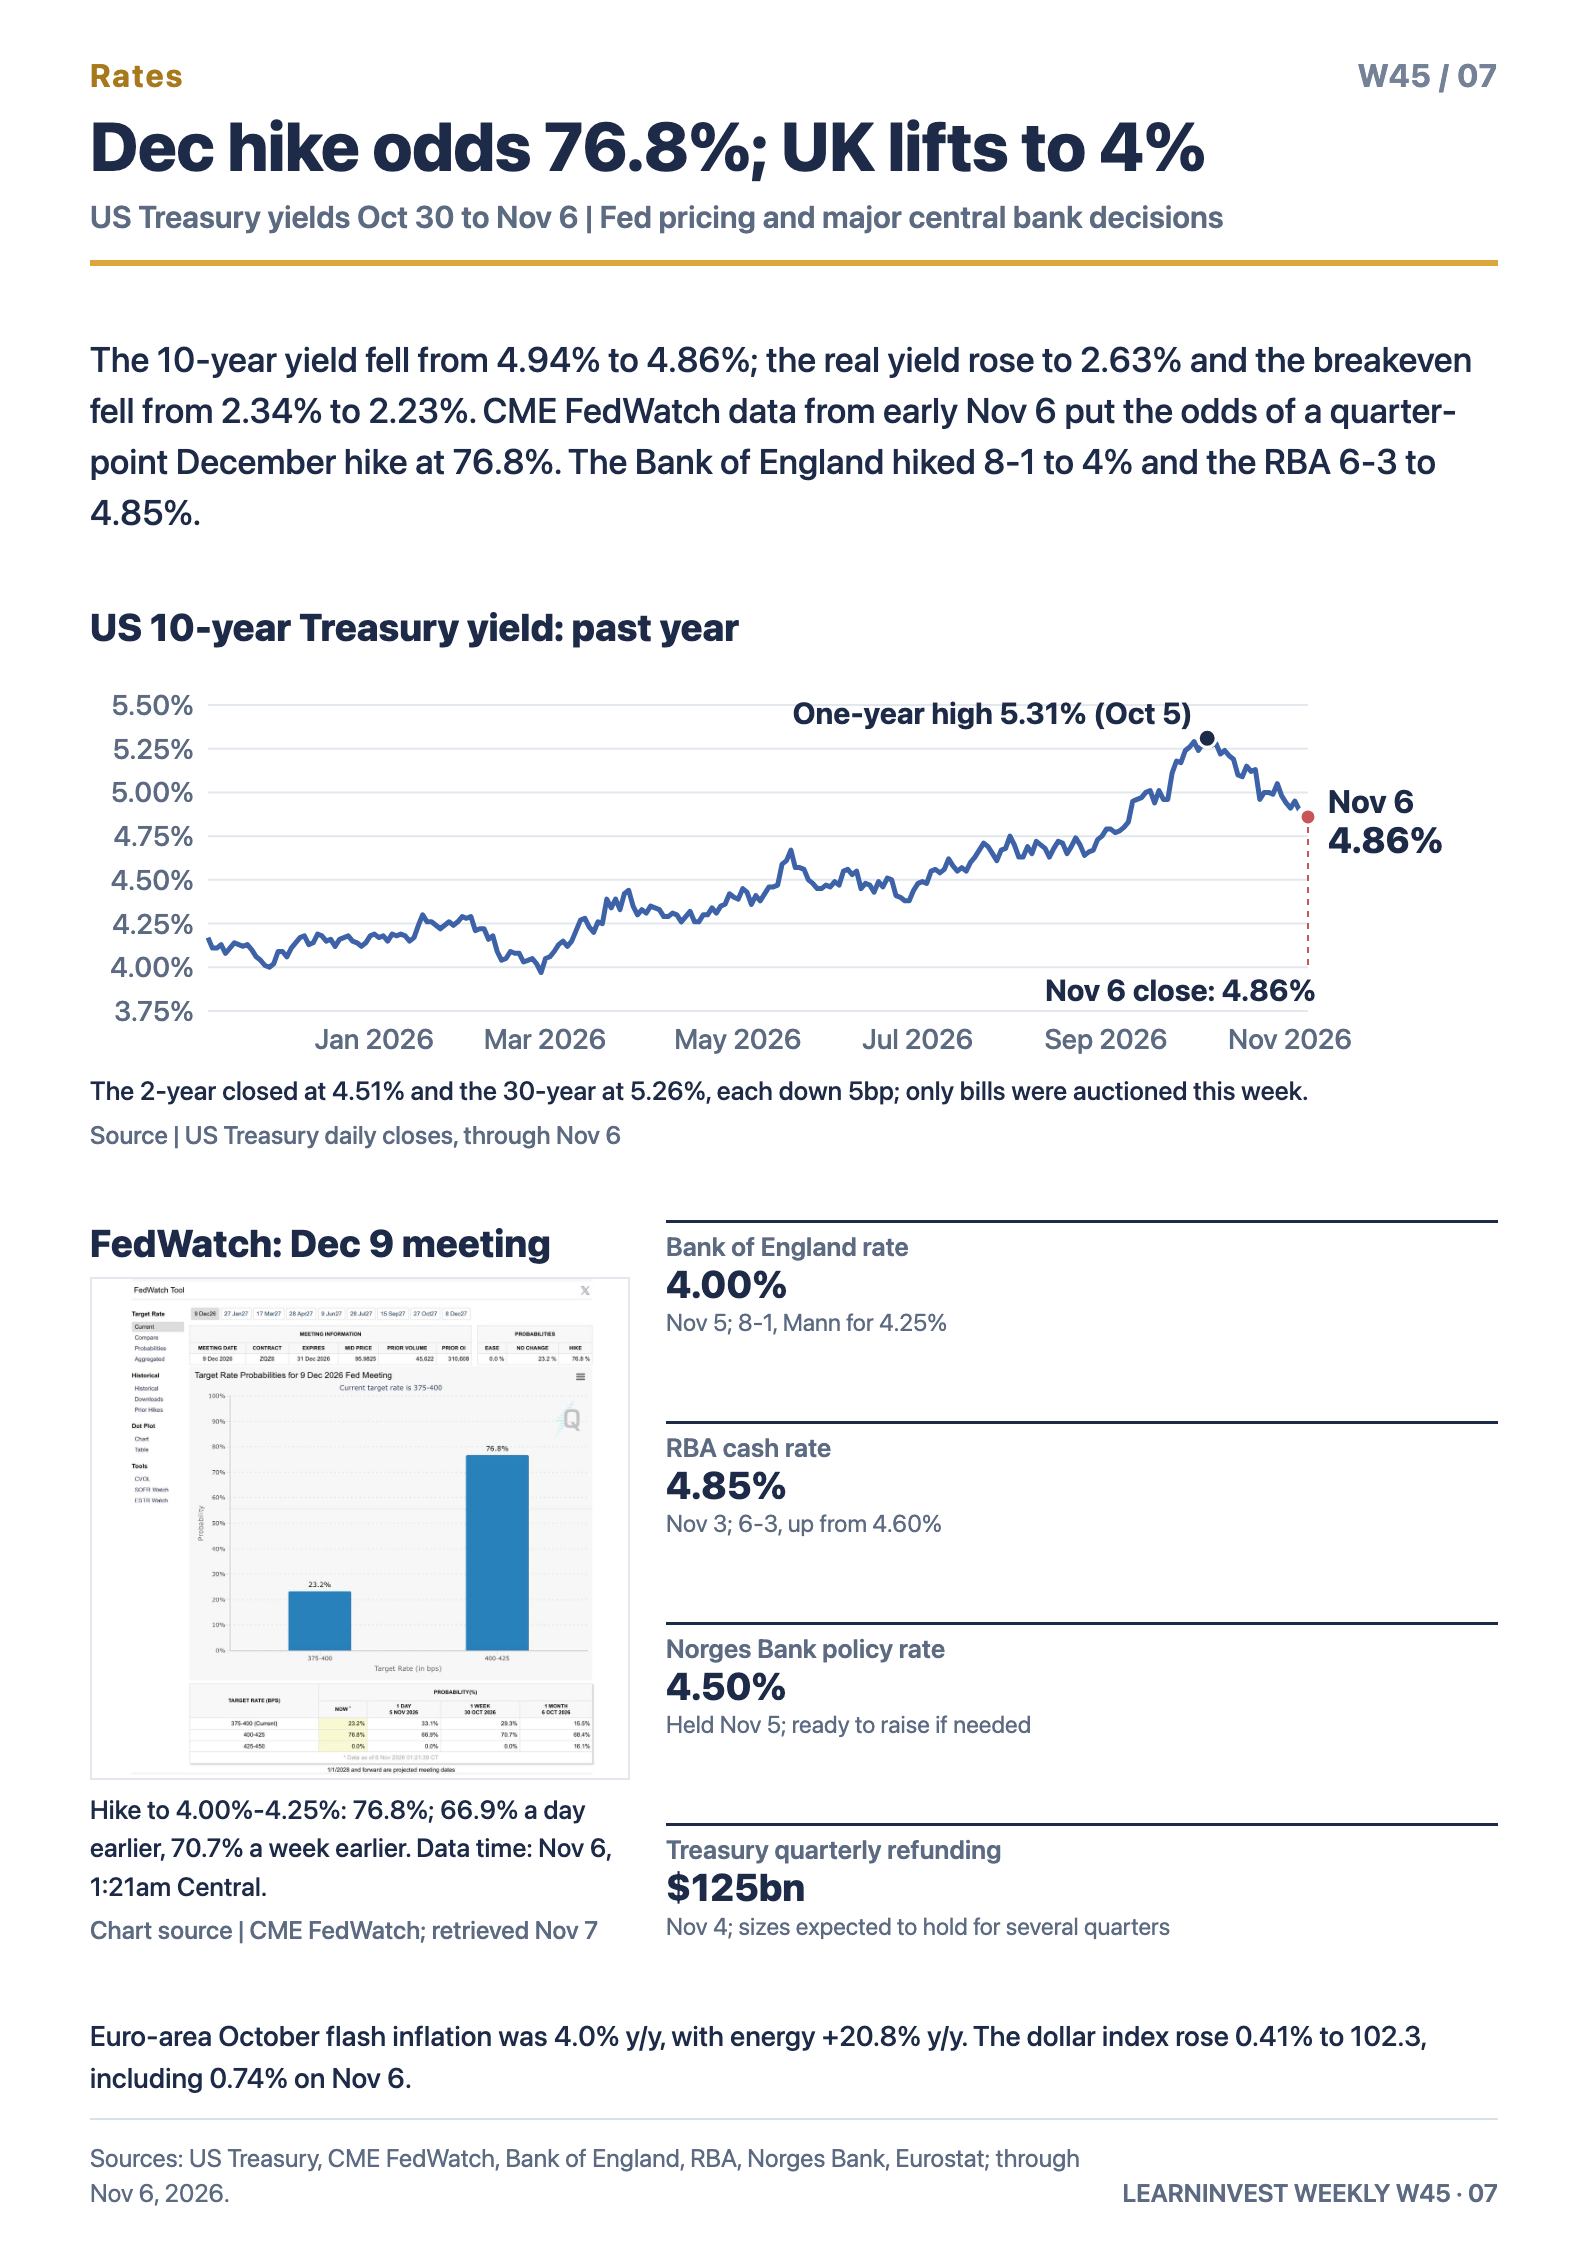
利率方面,10 年期公債殖利率由 4.94% 降至 4.86%,10 年期隱含通膨由 2.34% 降至 2.23%。CME FedWatch 11/6 凌晨資料顯示 12 月升息一碼的機率為 76.8%。英國央行升息至 4%,澳洲央行升息至 4.85%。
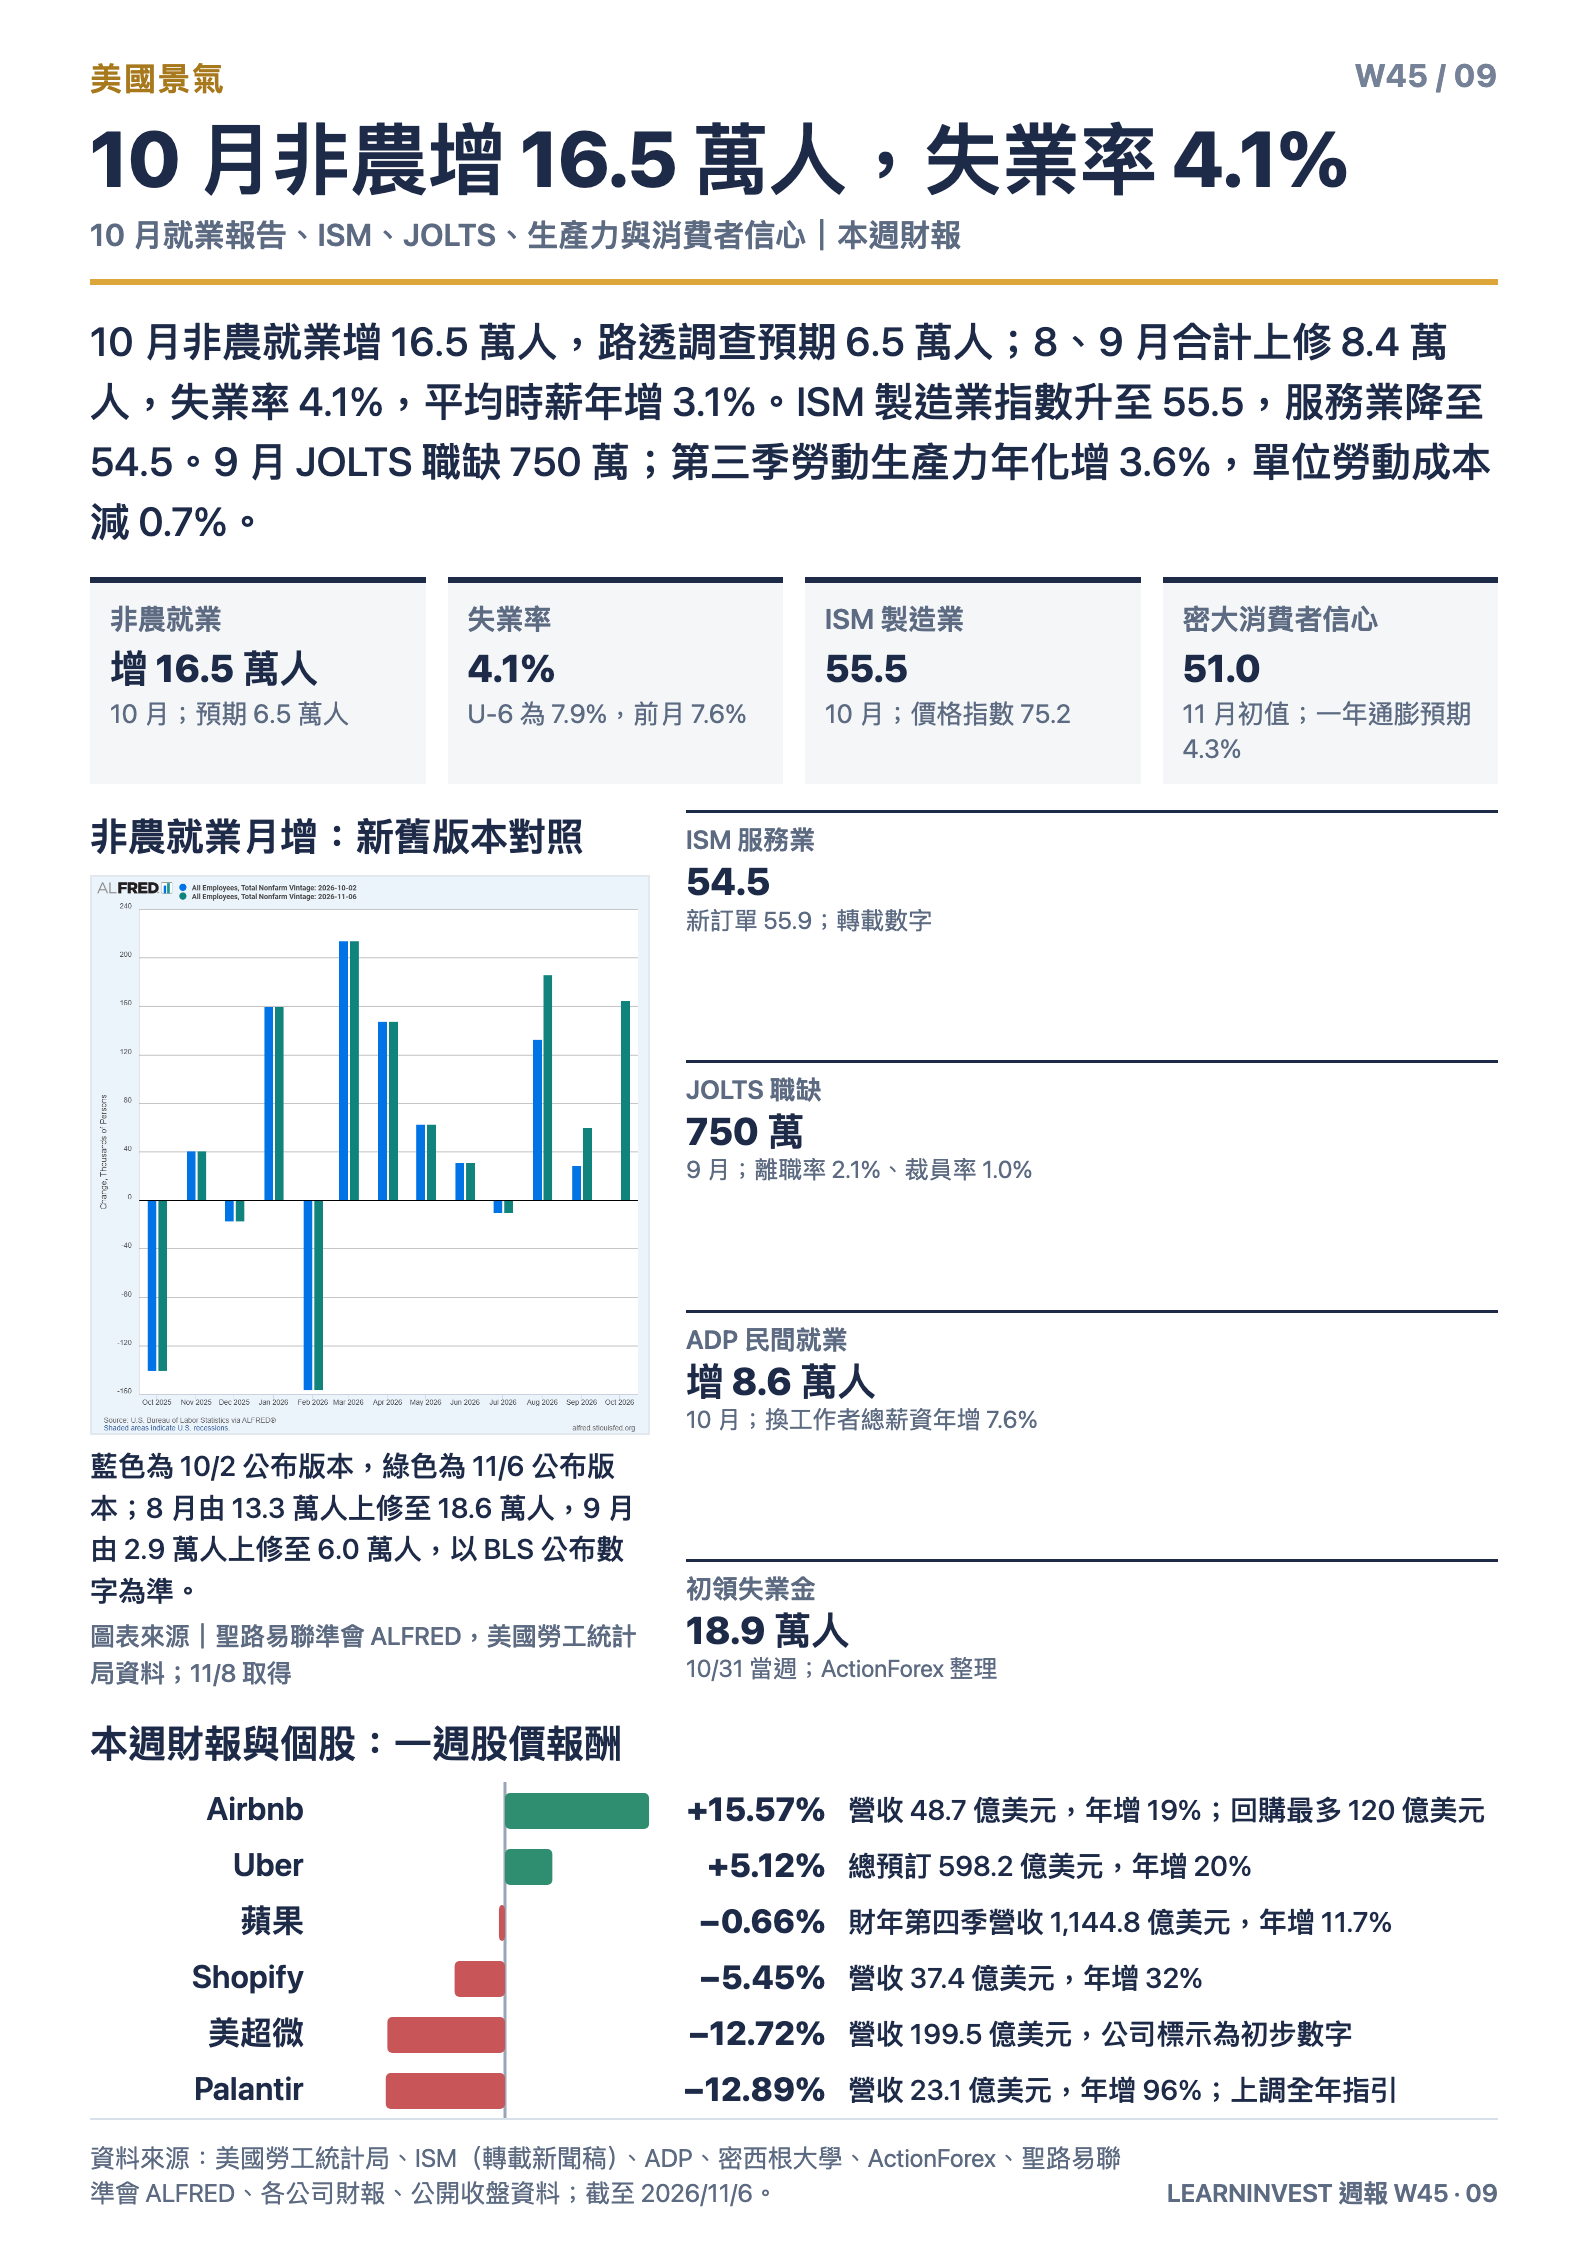
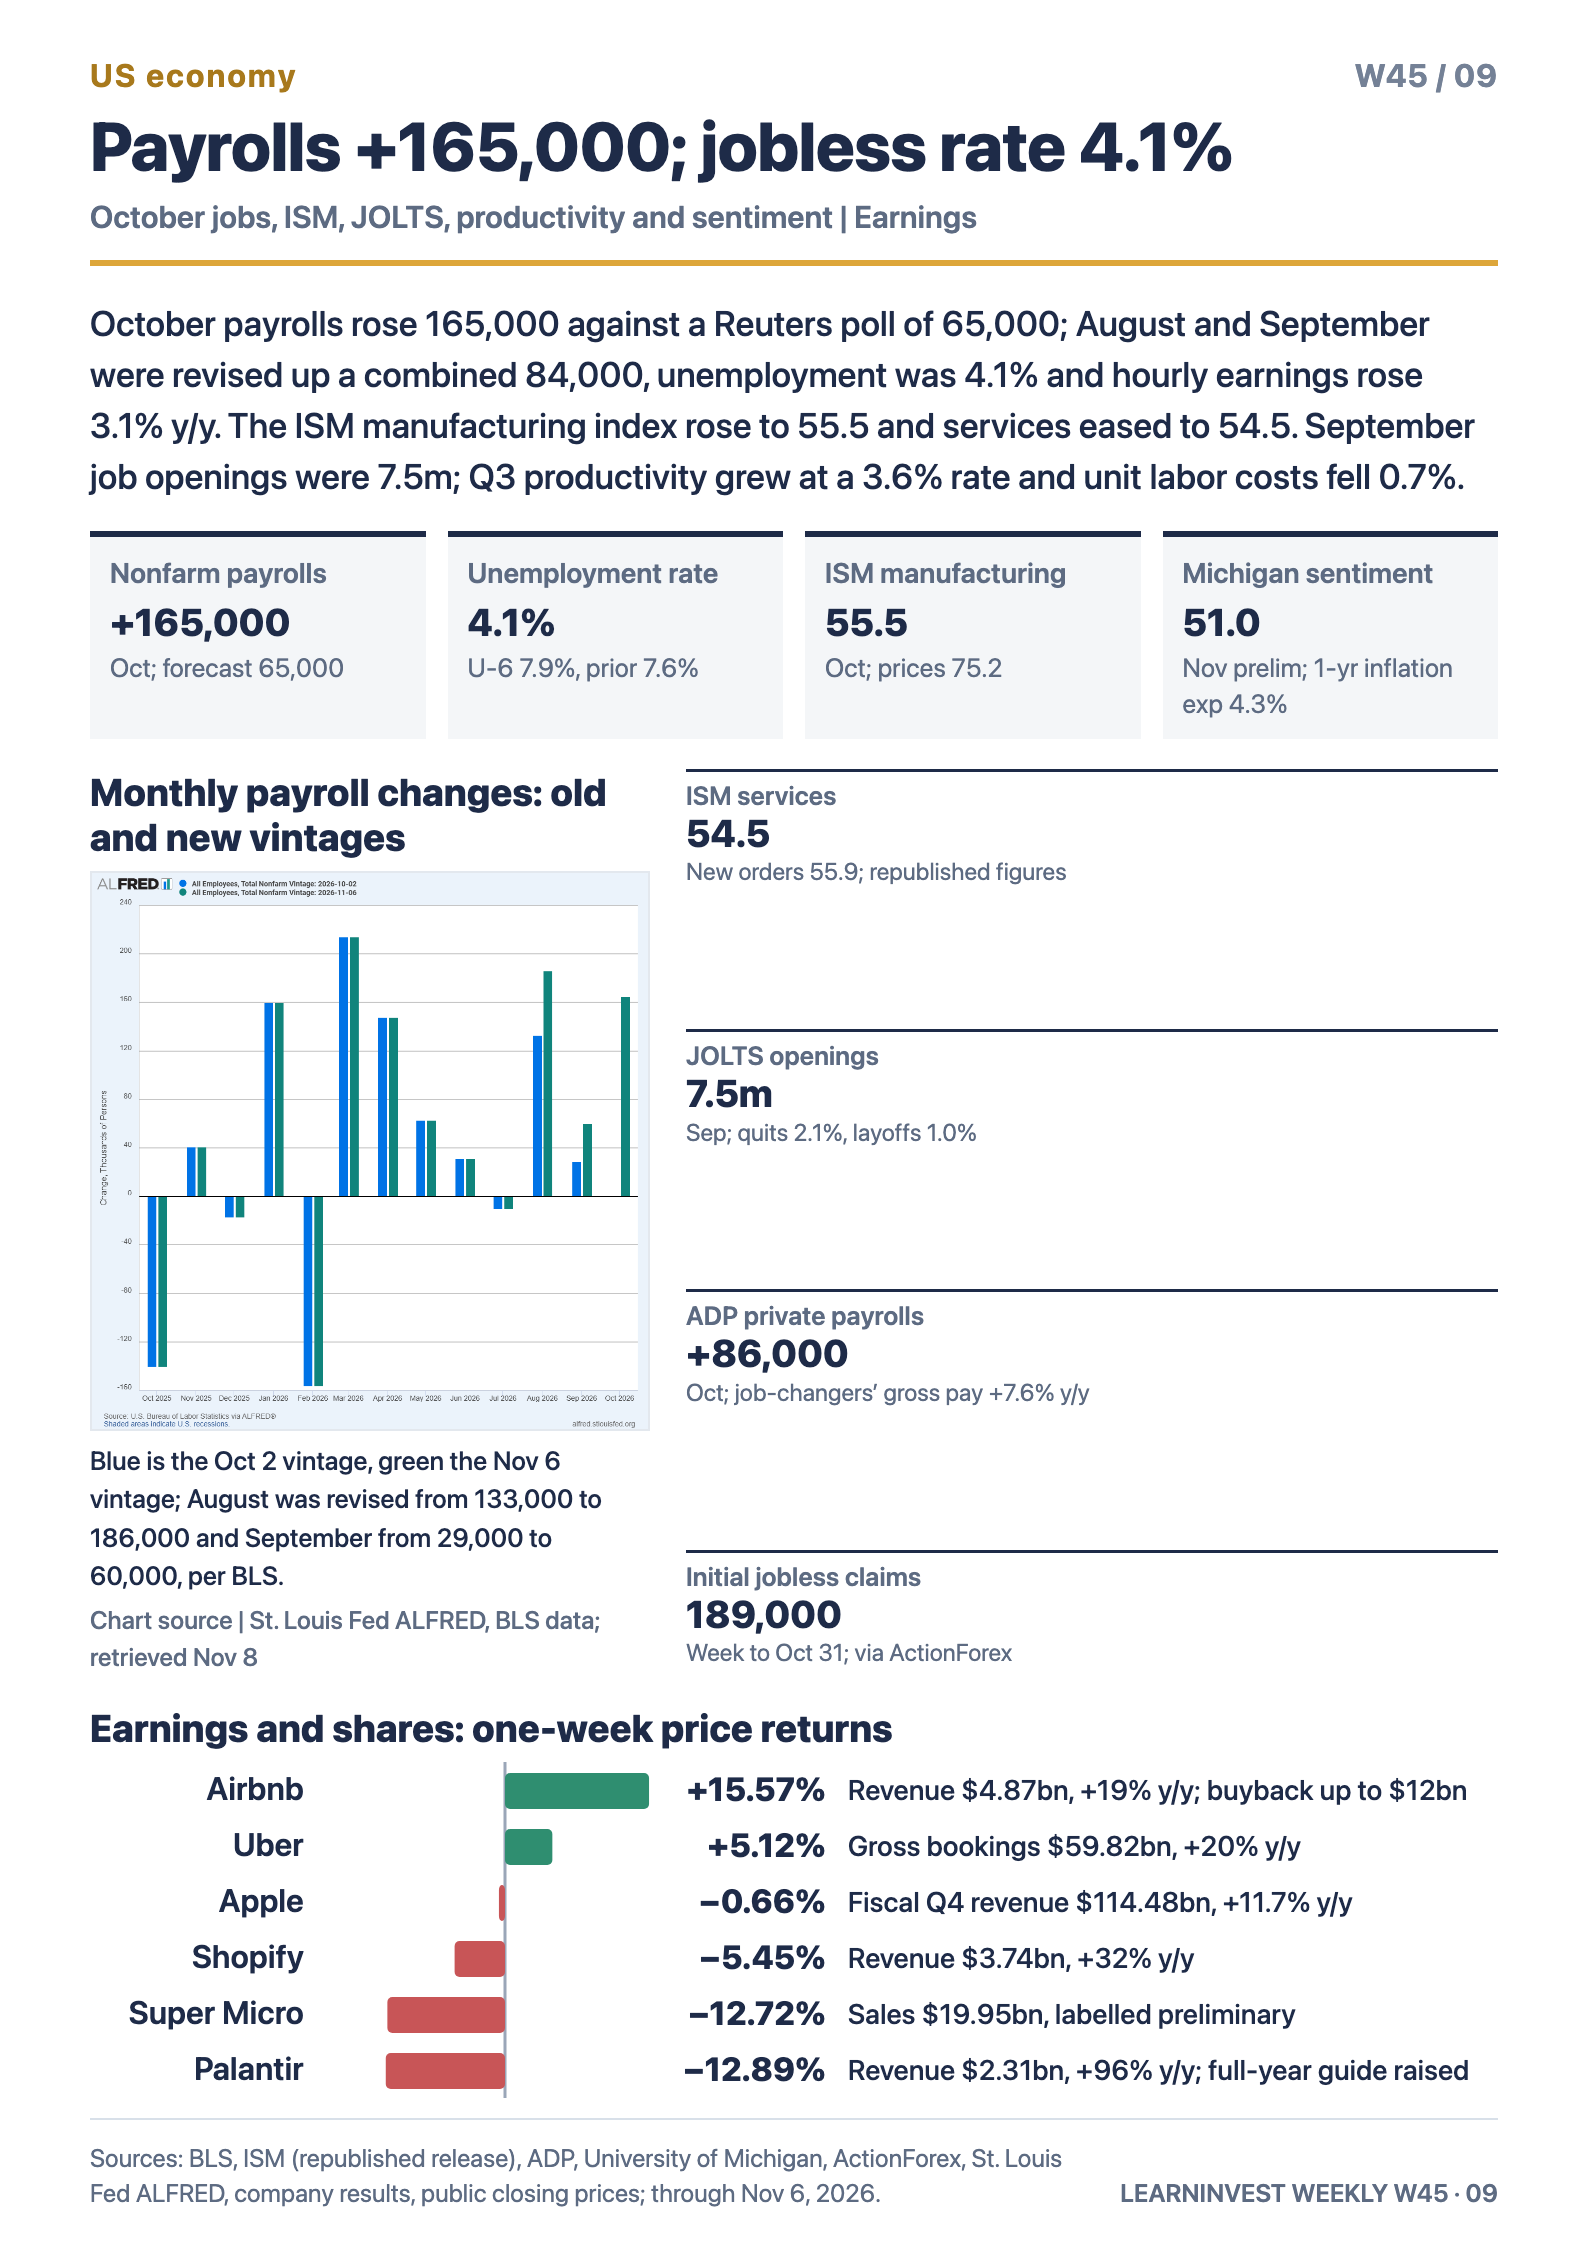
10 月非農就業增 16.5 萬人,路透調查預期 6.5 萬人,失業率 4.1%。ISM 製造業指數 55.5、服務業 54.5;密大 11 月消費者信心初值 51.0。
資料來源:美國財政部、美國勞工統計局、ISM、密西根大學、CME FedWatch、CBOE、AAII、CNBC、AP、各公司財報、臺灣證券交易所、英國央行、澳洲央行、公開市場收盤資料;截至 2026/11/6。股票與 ETF 為價格報酬,未含配息。 本內容為公開市場資料整理,不涉及個別投資決策。
Full-text weekly highlights
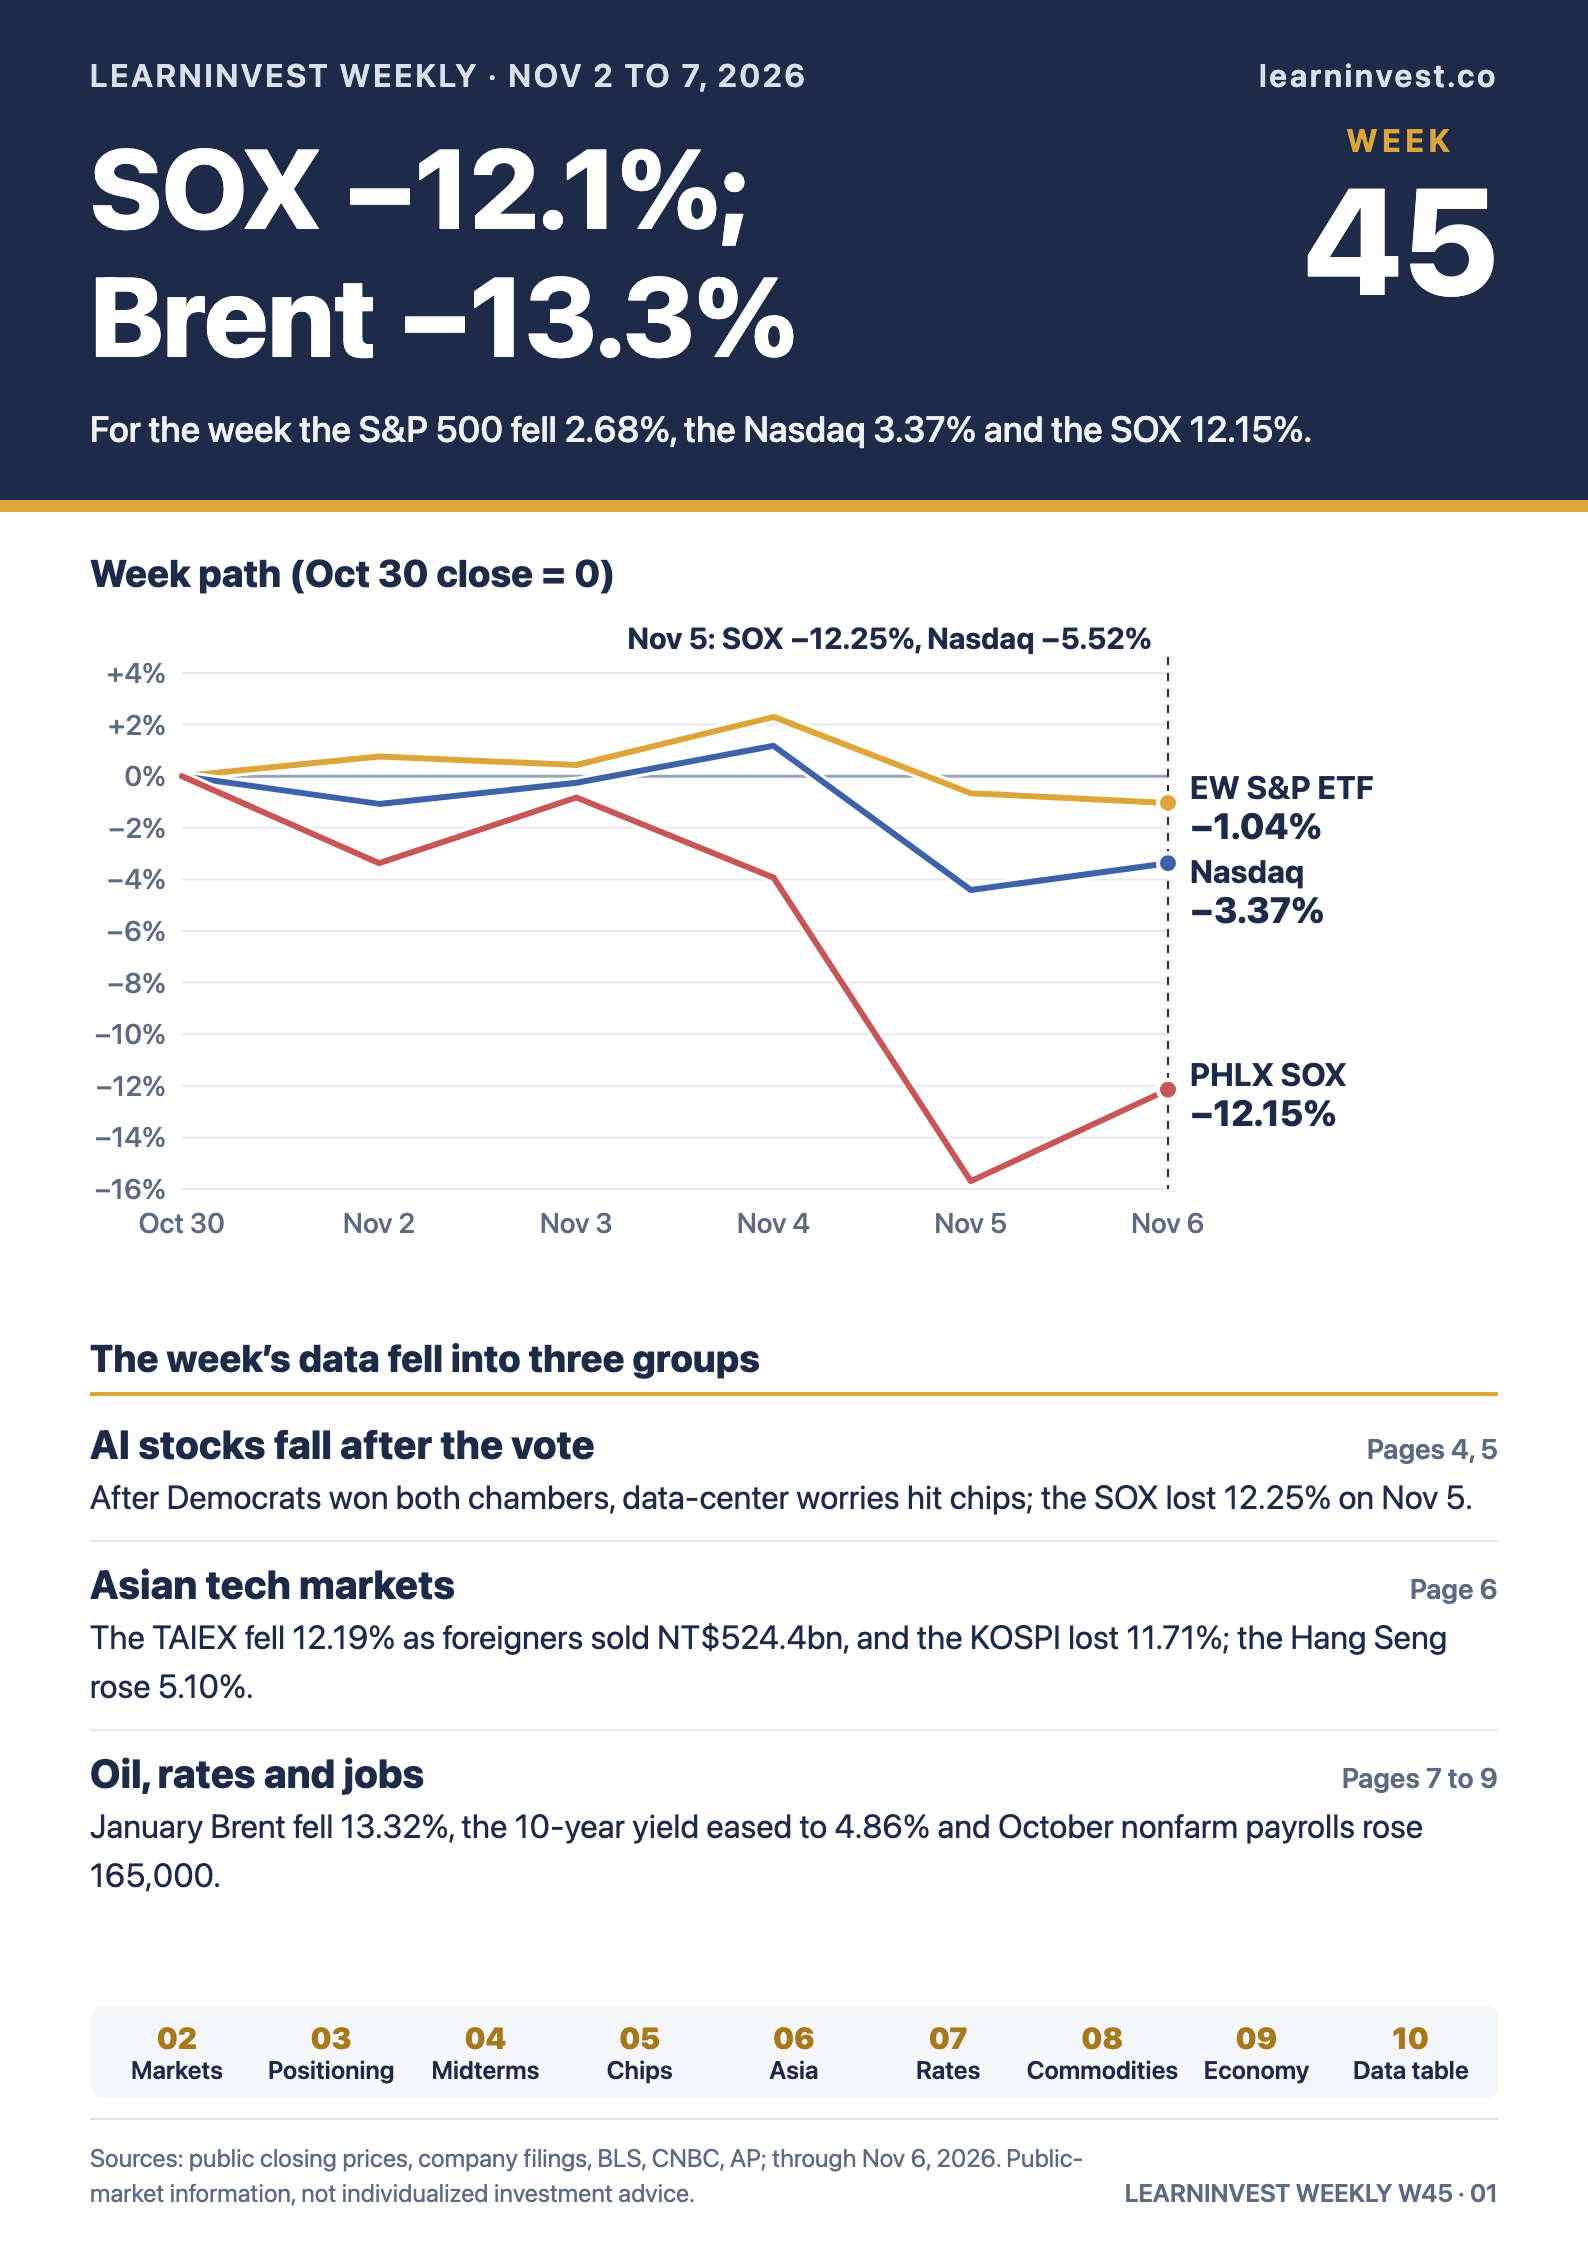
Two days set the week. Democrats won both chambers of Congress in the Nov 3 midterms, and on Nov 4 the Dow gained 1,569.40 points (3.03%) as Microsoft rose 6.68% and Amazon 6.12%. On Nov 5, CNBC said investors feared a slower AI data-center build-out. The S&P 500 fell 4.36%, its largest one-day drop since April 2025, and the Philadelphia Semiconductor Index lost 12.25%, its largest since March 2020.
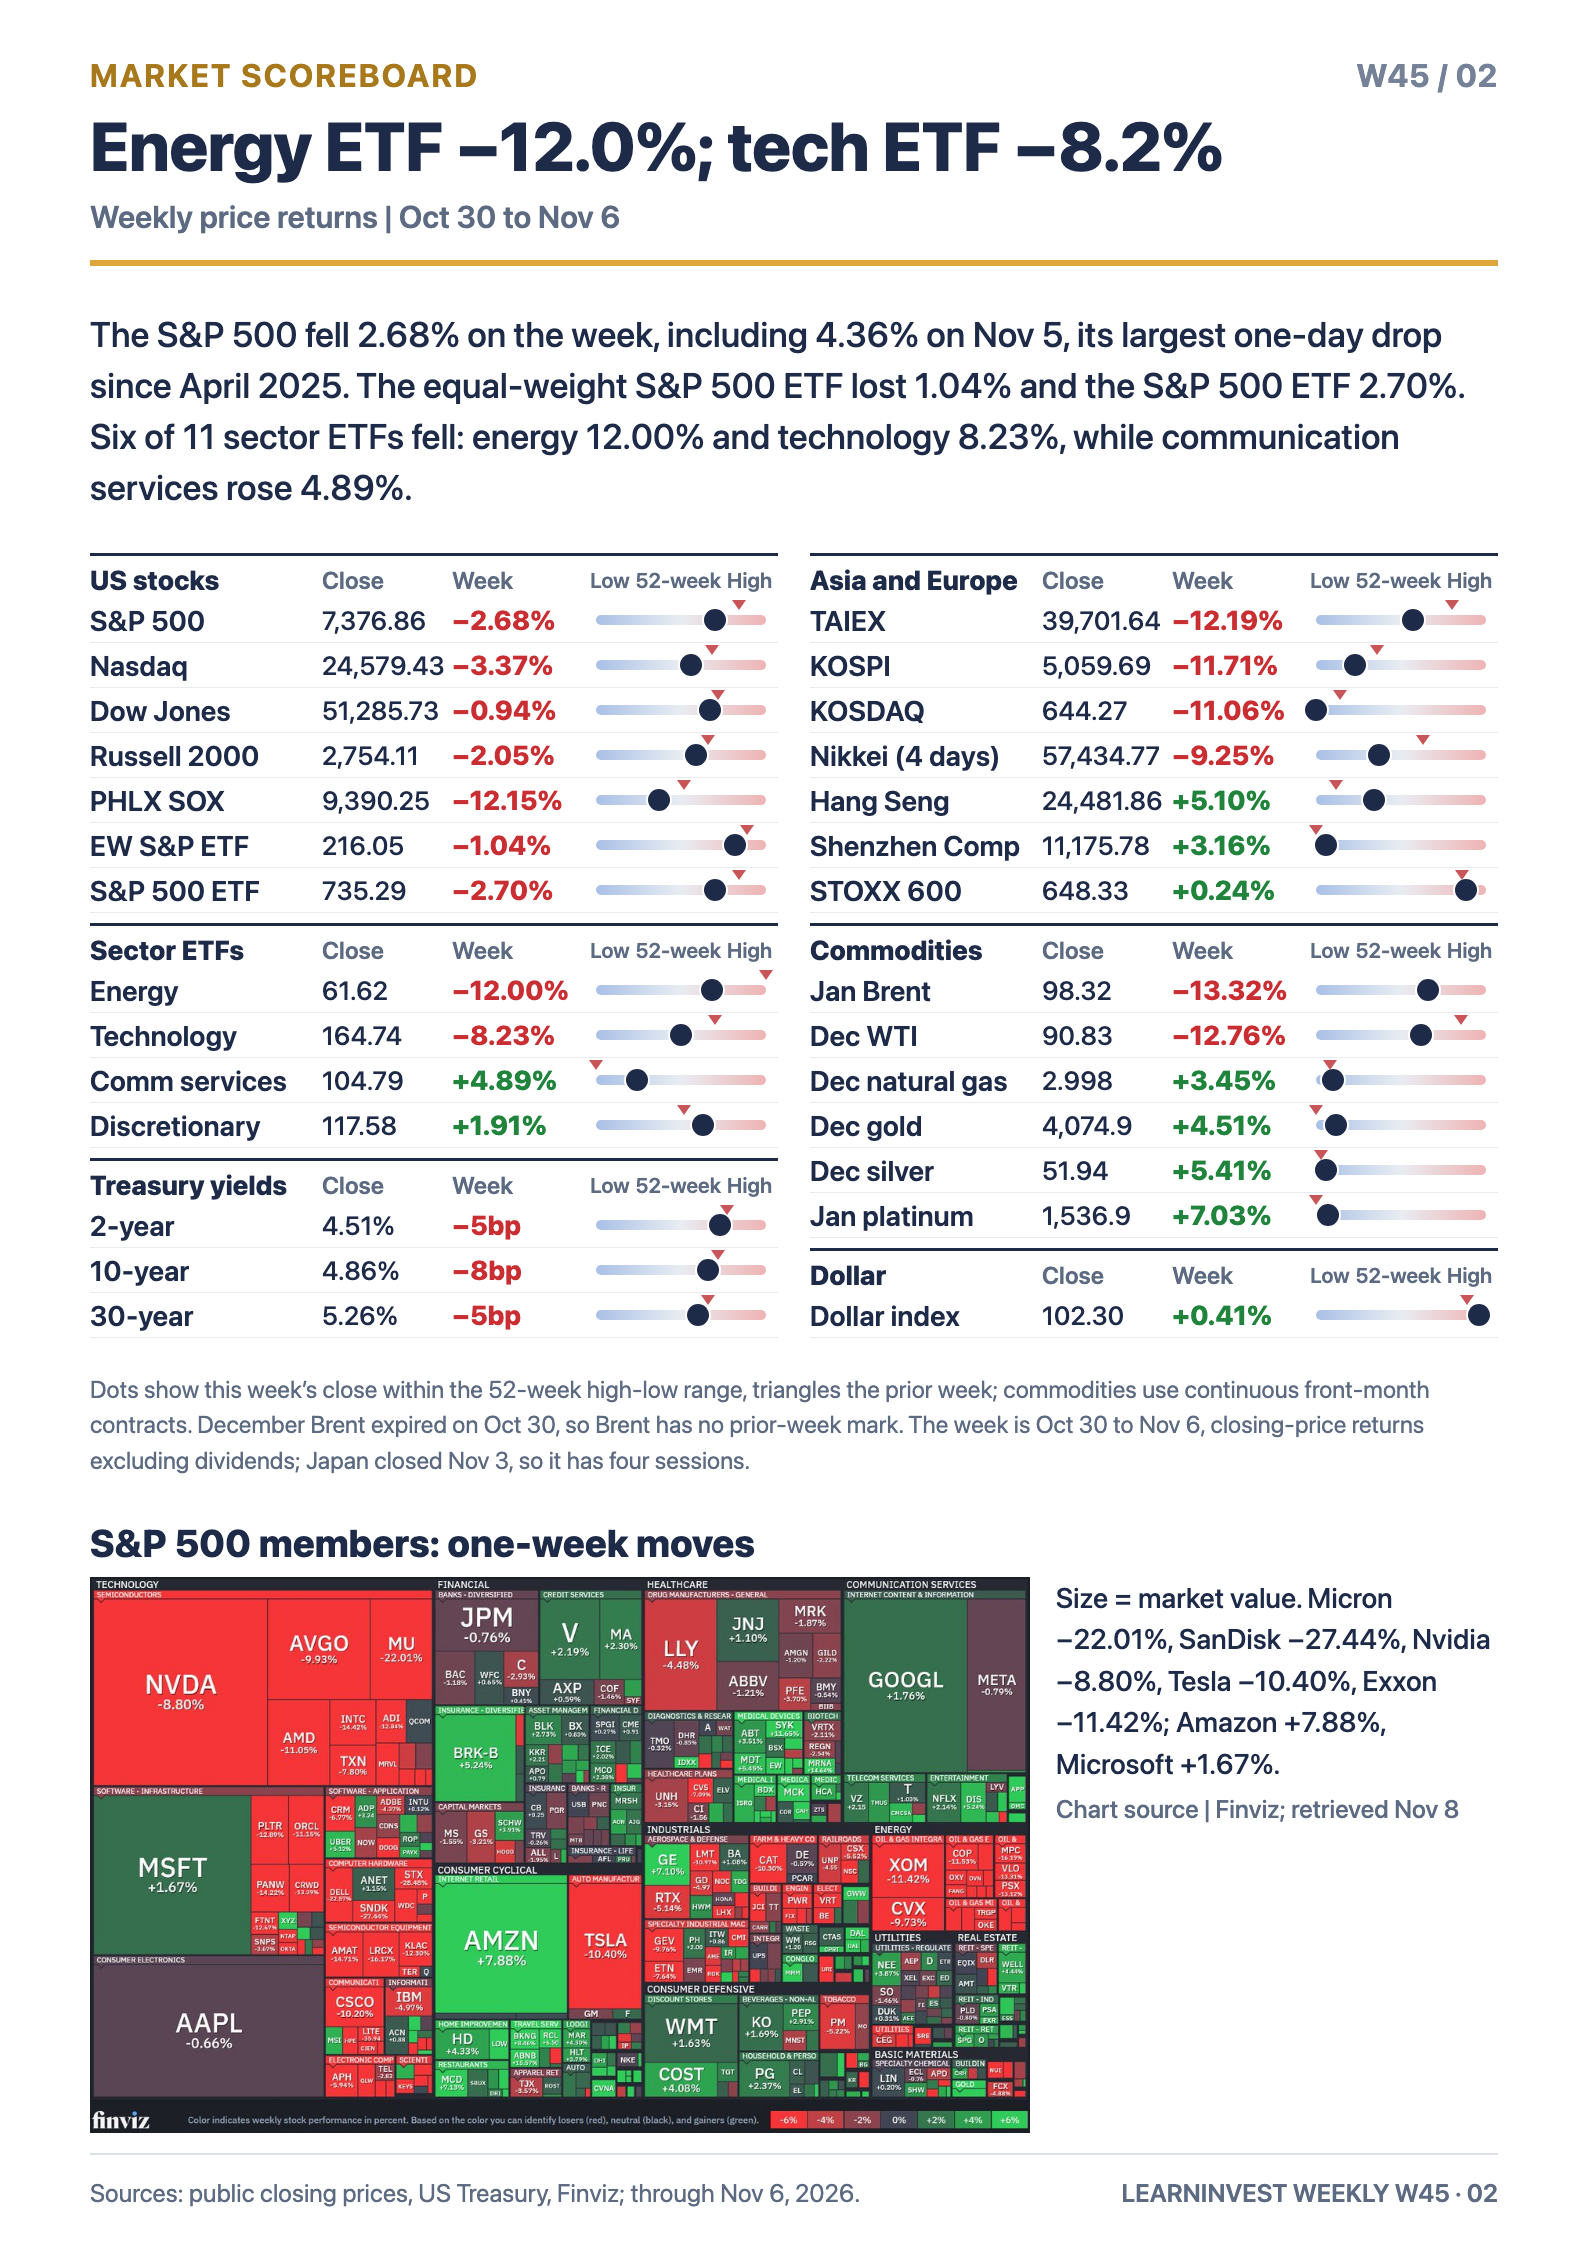
For the week the S&P 500 fell 2.68%, the Nasdaq 3.37% and the SOX 12.15%. The equal-weight S&P 500 ETF lost 1.04% and the S&P 500 ETF 2.70%. Six of 11 sector ETFs fell: energy lost 12.00% and technology 8.23%, while communication services gained 4.89%.
Goldman Sachs estimated that states likely to tighten rules hold about 45% of planned US capacity, with Texas about a quarter, and expects any pauses to be short-lived (reported second-hand). CNBC, citing Ballotpedia, counted 41 local data-center ballot measures in 10 states, with voters opposing data centers in all but one.
Among chip stocks, memory names fell hardest: SanDisk lost 27.44% on the week and Micron 22.01%. AMD reported 97% year-on-year growth in data-center revenue after the Nov 3 close; its shares rose 1.01% on Nov 4 and fell 17.26% in the Nov 5 sell-off. Qualcomm cited higher input costs, including memory, and fell 9.49% that day.
Positioning: the VIX rose from 16.61 to 28.18 on Nov 5, a 69.66% jump. Total put volume across Cboe options was 11.23 million contracts that day, and the equity put/call ratio was 0.89. AAII's weekly survey, reported Nov 4 and taken before the drop, had bears at 48.4% against 34.1% bulls.
Asian tech markets fell hard. Taiwan's TAIEX lost 12.19% on the week and 1,873.08 points on Nov 6, closing 20.31% below its Oct 6 closing high. Over the five sessions foreign investors sold a net NT$524.4 billion while investment trusts bought a net NT$128.8 billion. The KOSPI fell 11.71% and the Nikkei 9.25%, the Nikkei over four sessions, while the Hang Seng rose 5.10%.
Oil had its own story. January Brent futures fell 13.32% to $98.32, with drops of 7.63% on Nov 2 and 8.67% on Nov 4. CNBC reported that US and Iranian leaders signalled openness to talks on Nov 2, and that Vice President Vance posted on Nov 4 that the war cost his party the midterms. December gold futures rose 4.51% to $4,074.90 and the gold miners ETF 13.63%.
Rates eased. The 10-year Treasury yield fell from 4.94% to 4.86%, and the 10-year breakeven from 2.34% to 2.23%. CME FedWatch data from early Nov 6 put the odds of a December quarter-point hike at 76.8%. The Bank of England raised Bank Rate to 4% in an 8-1 vote, and Australia's central bank lifted its rate to 4.85%.
US data ran firm. October payrolls rose 165,000 against a Reuters poll of 65,000, with August and September revised up a combined 84,000 and unemployment at 4.1%. The ISM manufacturing index rose to 55.5 and services eased to 54.5. Preliminary nonfarm business productivity grew at a 3.6% annual rate in the third quarter.
Earnings elsewhere: Airbnb rose 15.57% on the week after 19% year-on-year revenue growth and a buyback of up to $12 billion, and AppLovin gained 71.21% after 55% year-on-year revenue growth. Palantir reported 96% year-on-year revenue growth and a raised full-year guide on Nov 2; its shares fell 1.65% on Nov 3 and 12.89% on the week, most of it in the Nov 5 sell-off. Full report: https://learninvest.co/weekly/2026-w45-overview
Sources: US Treasury, BLS, ISM, University of Michigan, Reuters, CME FedWatch, Cboe, AAII, CNBC, AP, company filings, TWSE, Bank of England, Reserve Bank of Australia and public closing prices. Data through Nov 6, 2026. Equity and ETF returns exclude dividends. Public-market information, not individualized investment advice.