【聯準會的資產負債表又開始變大 🏛️】
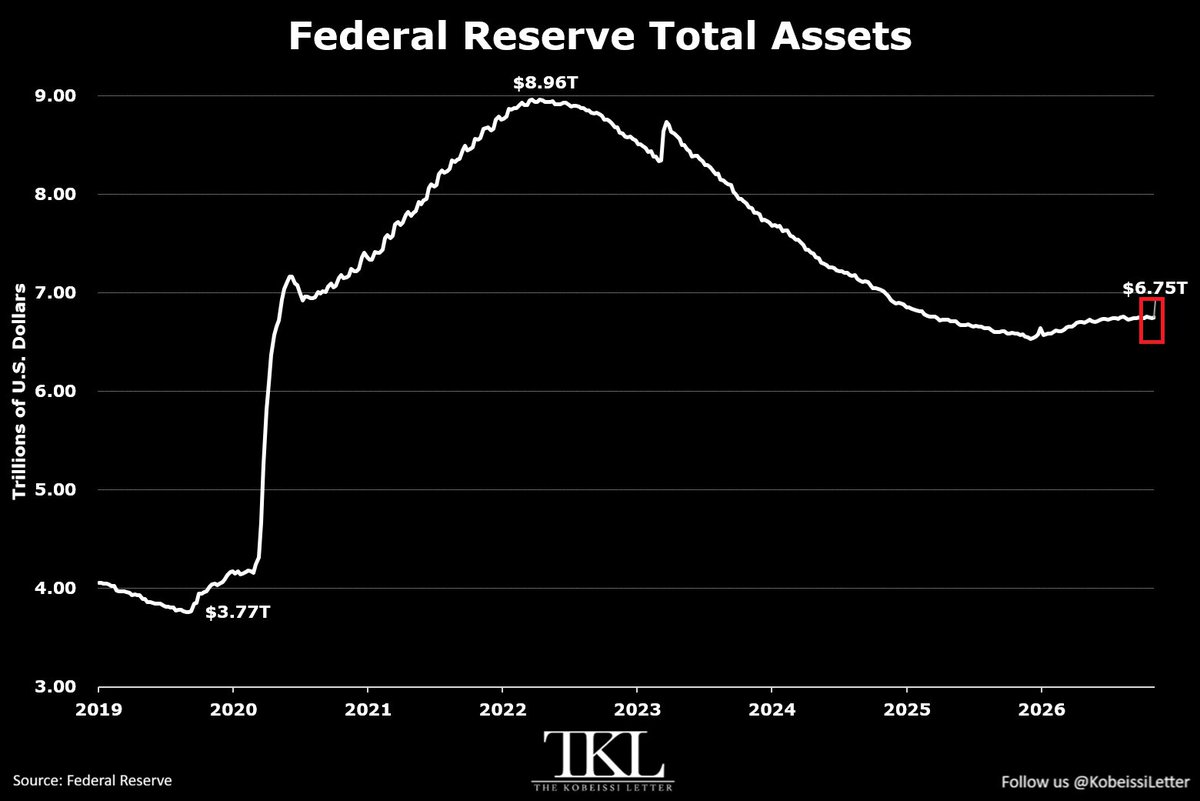
聯準會的總資產回到 6.75 兆美元,比 2025 年 12 月的低點多了約 2,120 億美元。2022 年的高點是 8.96 兆,疫情前是 3.77 兆。
這個回升不是重新印鈔。聯準會在 2025 年底結束了持續約三年半的縮表,接著開始買進一年期以內的短期國庫券,目的是把銀行體系的準備金補回充足水準,而不是壓低長期利率來刺激經濟。兩者買的東西不一樣,想影響的價格也不一樣。
把組成拆開會更清楚。同一段期間,公債持有量增加 3,900 億美元到 4.58 兆,是 2024 年 3 月以來最高;不動產抵押證券減少 1,700 億美元到 1.88 兆,是 2020 年 6 月以來最低。總額只多了兩千億出頭,底下是一邊買進公債、一邊讓房貸相關部位自然到期的交換。
另外,這些準備金管理的買盤其實停了好幾個月。九月和十月聯準會都宣布暫不進場,理由是銀行體系流動性充足,市場原本預期十一月中才會恢復。所謂又開始擴表,描述的是一個時停時走的過程。
真正要盯的不是總額那條線,是準備金的水位。那個數字才會告訴你聯準會是在被動補水,還是真的在放鬆。
資料來源:聯準會資產負債表周報與貨幣政策報告(圖片來自 @KobeissiLetter)
The Fed's Balance Sheet Is Growing Again
Total Federal Reserve assets are back to $6.75 trillion, about $212 billion above the low of December 2025. The 2022 peak was $8.96 trillion and the pre pandemic level was $3.77 trillion.
This is not a return to printing. The Fed ended roughly three and a half years of balance sheet shrinkage at the end of 2025 and began buying Treasury bills maturing within a year, with the aim of restoring bank reserves to an ample level rather than pushing down long term rates to stimulate the economy. The instruments differ, and so do the prices being targeted.
The composition makes it clearer. Over the same period Treasury holdings rose $390 billion to $4.58 trillion, the highest since March 2024, while mortgage backed securities fell $170 billion to $1.88 trillion, the lowest since June 2020. The total rose a little over two hundred billion, and underneath it is a swap: buying government debt while letting housing related holdings run off.
These reserve management purchases have also been paused for months. The Fed said in September and again in October that it would not buy bills for this purpose, citing ample liquidity in the banking system, with markets expecting purchases to resume in mid November. Growing again describes a process that stops and starts.
The line to watch is not the total. It is the level of reserves, which is what tells you whether the Fed is topping up passively or actually easing.
Source: Federal Reserve weekly balance sheet releases and Monetary Policy Report (Image: @KobeissiLetter)