【對沖基金四年買了1.7兆美債,六成是同一筆套利】🏦
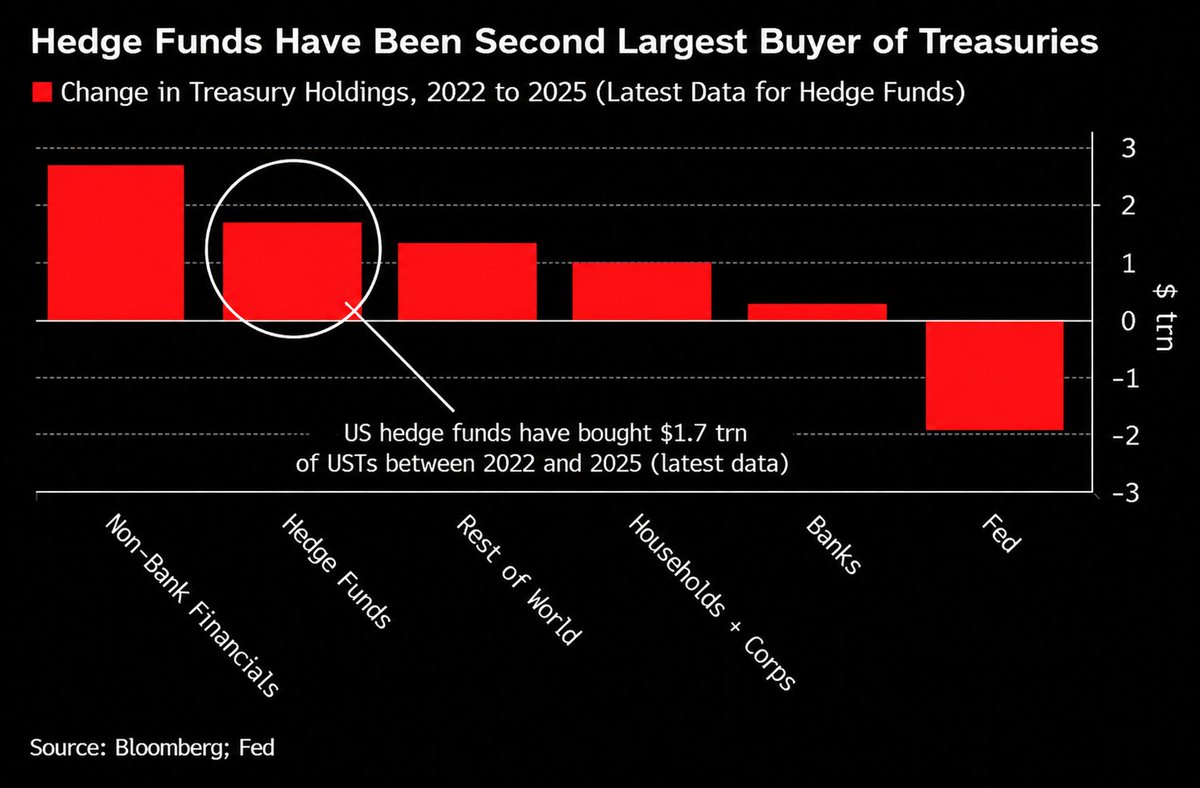
2022 到 2025 年,美國對沖基金增持 1.7 兆美元的美國公債,是所有部門中第二大的買方,僅次於非銀行金融機構。同一段期間,聯準會減持約 1.9 兆美元。
■ 這筆錢不是來長期持有的
聯準會今年 6 月的研究把這些部位拆開來看,大約六成來自現貨與期貨之間的基差交易:買進現貨公債,同時放空對應的公債期貨,賺兩者之間的價差,而買現貨的錢幾乎全部來自隔夜的附買回市場。這是一筆靠短期借款撐起來的槓桿套利,不是把債券買回來長期擺著的配置需求。美國金融研究辦公室估計,對沖基金如今持有約 7% 的可交易公債,2021 年時只有 4%。
這種部位平常很穩,壓力來的時候會一起退場,2020 年 3 月就發生過一次。美國證券交易委員會已經要求合格的公債現貨交易在 2026 年底前集中結算,附買回交易則是 2027 年年中,等於是替這個角色加上一道安全帶。
資料來源: 彭博、聯準會、美國金融研究辦公室 (圖片來自 @GlobalMktObserv)
Hedge Funds Bought $1.7tn of Treasuries, and 60% of It Is One Arbitrage
Between 2022 and 2025 US hedge funds added $1.7 trillion of Treasuries, the second largest increase of any sector behind non-bank financials. Over the same stretch the Federal Reserve shed about $1.9 trillion.
■ This money did not come to hold
A Federal Reserve study published in June broke the positions apart and found roughly 60% of them sit in the cash-futures basis trade: buy the cash Treasury, short the matching futures contract, earn the gap between them, and fund almost the entire cash leg in the overnight repo market. That is leveraged arbitrage built on short-term borrowing, not an investor deciding to own bonds. The Office of Financial Research puts hedge funds at about 7% of the marketable Treasury market today, up from 4% in 2021.
Positions like these are calm most of the time and head for the exit together when they are not, as they did in March 2020. The Securities and Exchange Commission now requires eligible cash Treasury trades to be centrally cleared by the end of 2026 and repo trades by the middle of 2027, which puts a seatbelt on the role these funds have taken.
Source: Bloomberg, the Federal Reserve and the US Office of Financial Research (Image: @GlobalMktObserv)